
Is Luckin Coffee (OTCPK:LKNC.Y) Still Cheap Based On Earnings?
Luckin Coffee has rewarded long term holders with a strong 5 year share price gain, yet recent weakness has many investors asking whether the current valuation still lines up with the company’s earnings power. With the stock now trading around US$33.18, the key issue is how much of its earnings story is already reflected in that price.
- Over the past 5 years, Luckin Coffee has delivered a share price return of 137.2%, which puts real weight on whether current earnings can carry that track record forward.
- The business model relies on scaling store economics and keeping operating costs in check, which can shape how much of each additional yuan of revenue ultimately shows up in earnings.
- Your read on Luckin Coffee is one view; the desks covering it have another. See what analysts think Luckin Coffee's shares could be worth.
The stock's next move may depend on whether Luckin Coffee's current earnings justify the valuation implied by today’s share price.
If you are weighing whether Luckin Coffee’s recent share price weakness matches its earnings profile, it can help to compare it with other businesses screened for 30 high quality undervalued stocks
Is Luckin Coffee Still Cheap on Earnings?
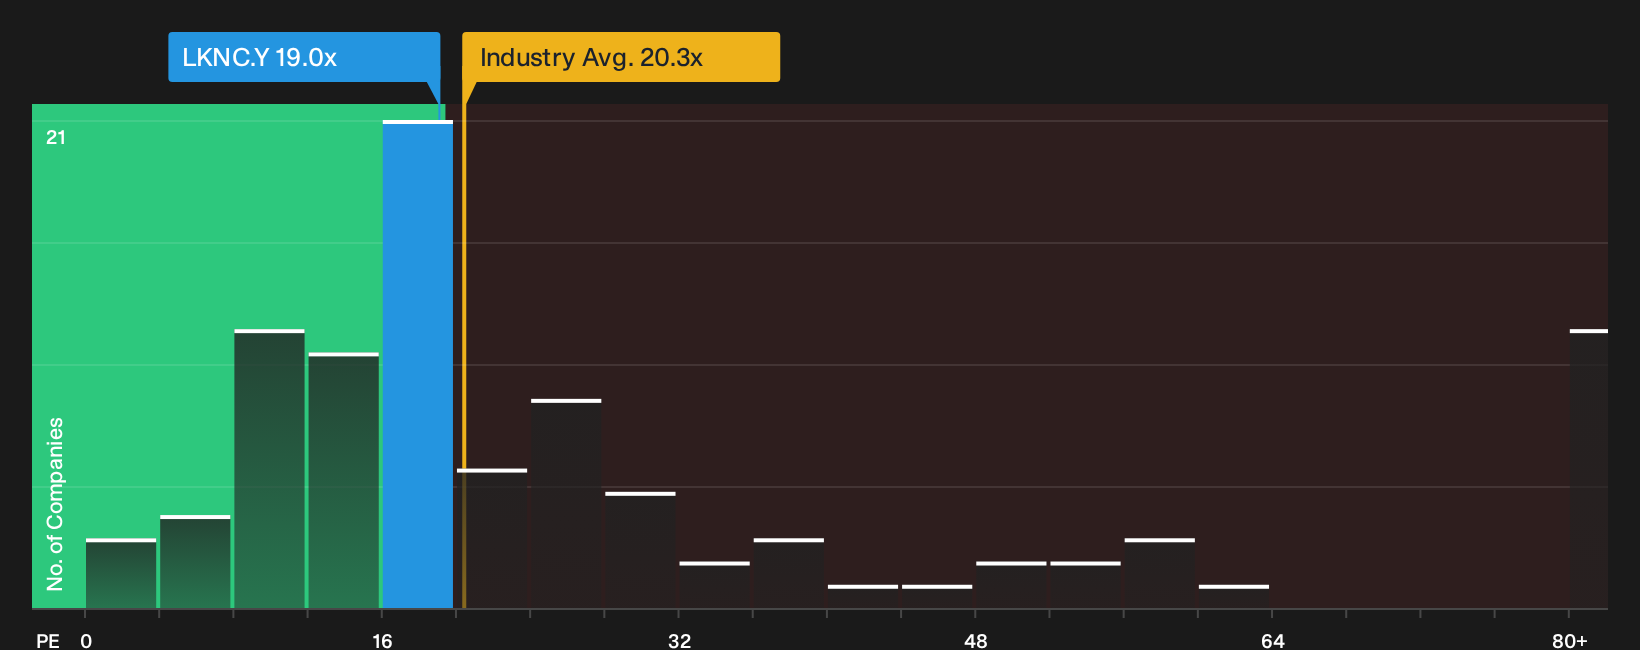
The P/E ratio works well for Luckin Coffee because earnings are now a key driver of how investors frame the story. At roughly 19.0x earnings, the stock trades below both the Hospitality sector average of about 20.3x and the broader peer group near 48.8x. That places the current valuation toward the lower end of where comparable consumer service businesses are priced on profits.
The Fair Ratio model, which adjusts for factors such as growth profile, profitability, size and business risk, points to a higher P/E than where Luckin Coffee trades today. On this framework the current multiple screens as undervalued, so the market is attaching a lower price tag to each unit of earnings than the model suggests. The gap leaves investors weighing whether the earnings record and risks justify that discount or whether the share price is lagging the company’s earnings power. Explore the numbers behind Luckin Coffee's P/E valuation.
The Luckin Coffee Narrative: What Would Justify Today's Price?
Narratives on Luckin Coffee pick up where the P/E debate leaves off by spelling out which paths for revenue growth, margins and earnings would need to play out for the current share price to look meaningfully high or low. Instead of a single output from a ratio or model, they unpack the future that number leans on so you can watch, over time, whether Luckin Coffee's real world progress matches that script, all within Simply Wall St's Community page.
One of the top community narratives on Luckin Coffee: 31% undervalued
"Expanding store presence and digital-first engagement support continued revenue growth and strong customer loyalty through innovation and personalized service..."
Discover why this Narrative puts Luckin Coffee at 31% undervalued.
One more piece of the Luckin Coffee puzzle to check
Before forming a full view on Luckin Coffee, it helps to know that Simply Wall St's broader checks have highlighted specific risk signals that sit alongside the valuation story. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com