
Why CoStar Group (CSGP) Is Back In Focus
Conference appearance puts CoStar Group in focus after index removal
CoStar Group (CSGP) is scheduled to appear at the U.S. All Stars Conference in London on September 22, shortly after its removal from the FTSE All-World Index raised fresh questions for shareholders.
That conference appearance comes at a shaky moment for CoStar Group, with the share price down 15.1% over the past 30 days and 57.6% year to date, while the 1 year total shareholder return has declined 66.5%. This points to fading momentum as investors reassess both growth prospects and risk.
Scan how CoStar Group compares with other real estate and property data players by reviewing our curated list of list of solid balance sheet and fundamentals (23 results).
After a slide of this size and a fresh index exit, CoStar Group now sits at a very different entry point. Does that reset finally tilt the risk reward in buyers’ favour once you run the numbers?
Most Popular Narrative: 25.3% Undervalued
Against a last close of $27.86, the most followed narrative pegs CoStar Group’s fair value at $37.30. This frames the current drawdown as a pricing gap that hinges on how well management turns today’s investments into profitable platforms.
The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform, despite muted bookings, lower revenue guidance and competitive pressure in multifamily advertising.
The current valuation of CoStar Group implies that the market is discounting execution risk around revenue growth, Homes.com scalability and AI disruption more heavily than the recent uplift in margins and record adjusted EBITDA guidance.
See why 27 investors see CoStar Group as 25% undervalued.
Result: Fair Value of $37.30 (UNDERVALUED)
Still, the CoStar Group story can break if muted net new bookings persist and if multifamily advertising pressure continues to squeeze Apartments.com pricing power.
Find out about the key risks to this CoStar Group narrative.
Another view on CoStar Group’s valuation
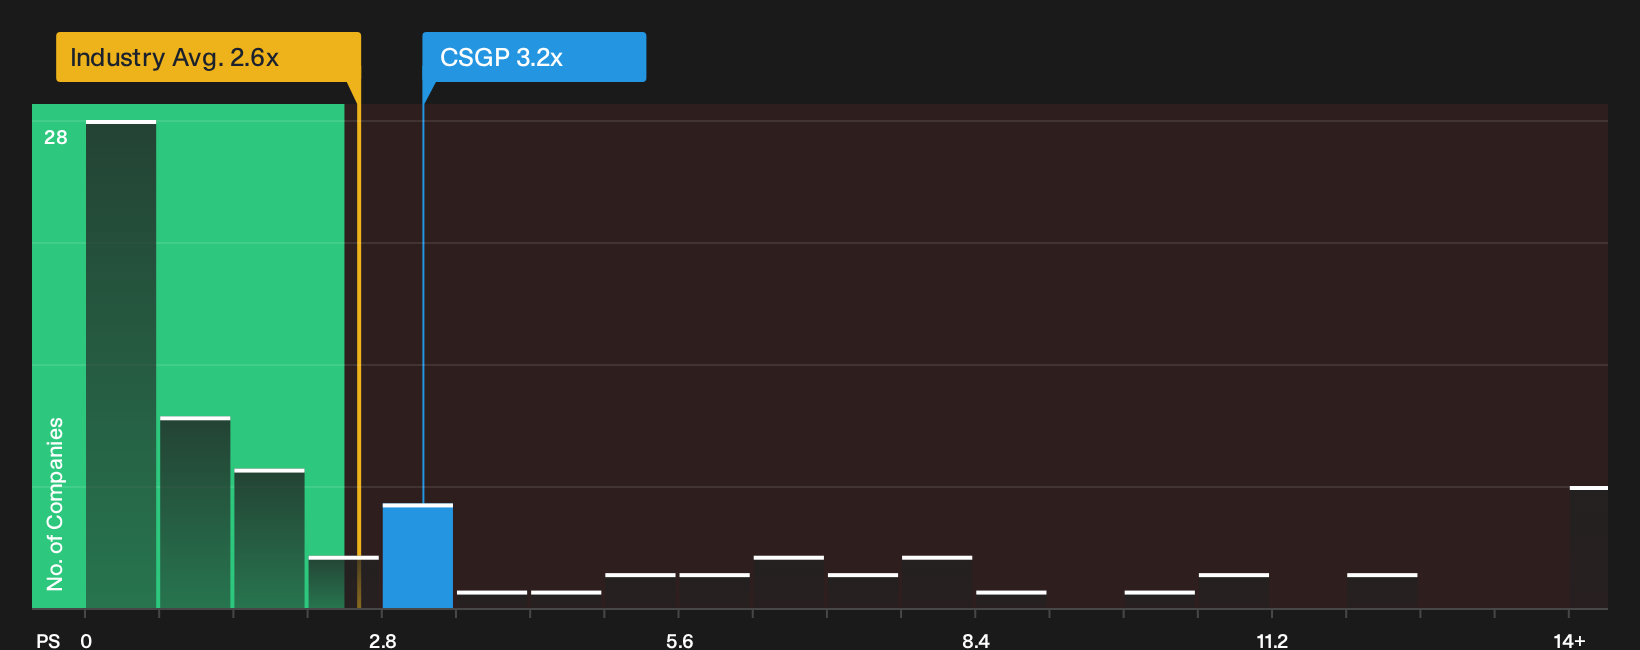
The most followed narrative leans on analyst fair value of $37.30 and an 82.3% discount to that estimate. A different lens looks at CoStar Group’s P/S of 3.2x. That is higher than both peers at 1.2x and the US real estate group at 2.6x, yet below a fair ratio of 3.9x that the market could drift toward over time. Is this a bargain in disguise or just a full price with a bullish story attached?
Before leaning on any single yardstick, it helps to see what the numbers say when you line up that P/S against peers and the fair ratio in detail. Then ask how comfortable you are with the implied valuation risk or room for upside. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around CoStar Group is clearly split, so consider reviewing the full data set yourself and weighing both sides using our breakdown of 2 key rewards and 1 important warning sign.
Looking for more CoStar Group sized investment ideas?
If CoStar Group has sharpened your focus on valuation and risk, do not stop here. Put that curiosity to work and let fresh ideas come to you.
- Target long term value potential by scanning companies that combine quality fundamentals with appealing valuations through 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing 7 dividend fortresses that aim to pair higher yields with resilient business models.
- Control downside risk by filtering for 31 resilient stocks with low risk scores that balance financial stability with measured growth profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com