
New Chip Launch Might Change The Case For Investing In Power Integrations Stock
- Power Integrations recently introduced its fourth generation CAPZero-4 X-capacitor discharge ICs, targeting industrial and consumer AC-DC applications with sub-1 mW consumption, wide temperature operation, and global safety compliance.
- The CAPZero-4 line serves as a drop-in replacement for earlier CAPZero parts, which can lower redesign effort for appliance, adapter, display, and industrial customers that face tighter standby power limits.
- We will now explore how Power Integrations' new ultra low power CAPZero-4 family could influence the broader investment narrative.
Scan other power efficiency players riding the same tightening standby standards theme as Power Integrations with our curated list of 39 power grid technology and infrastructure stocks
Power Integrations Investment Narrative Recap
To own Power Integrations, you need to believe its power conversion technology can keep finding design wins across appliances, industrial gear, and higher value segments like EVs and data centers. The key near term swing factor is how fast demand stabilizes after recent earnings volatility and a period where the stock has lagged sector returns.
The CAPZero-4 launch helps the operational story at the margin by reinforcing the low power, standards driven part of the portfolio, but it does not rewrite the main catalyst or the biggest risk. Execution in newer markets and exposure to trade policy, tariffs, and appliance cycles still drive the real upside and downside.
The CAPZero-4 announcement is most relevant because it touches the established appliance and industrial base that still funds Power Integrations’ push into EV, AI, and renewables. A sub 1 mW device that ships as a drop in replacement can support customer adoption where standby limits are tight without forcing new board layouts or long validation cycles.
For investors, the key question is how this sort of product cycle supports the broader GaN and high voltage roadmap rather than any single revenue spike. Stronger efficiency parts that already ship in volume help maintain relationships with OEMs, which can matter when the company pitches newer 2,200 V PowiGaN platforms into EV and data center programs that carry higher expectations and execution risk.
Power Integrations' current analyst narrative points to revenues of $690.7 million and earnings of $160.0 million by 2029, which aligns with forecast revenue growth of 15.4% per year and an earnings increase of about 6.4x from $25.1 million today.
Uncover why Power Integrations' fair value indicates a 58% potential upside to its current price that could narrow quickly.
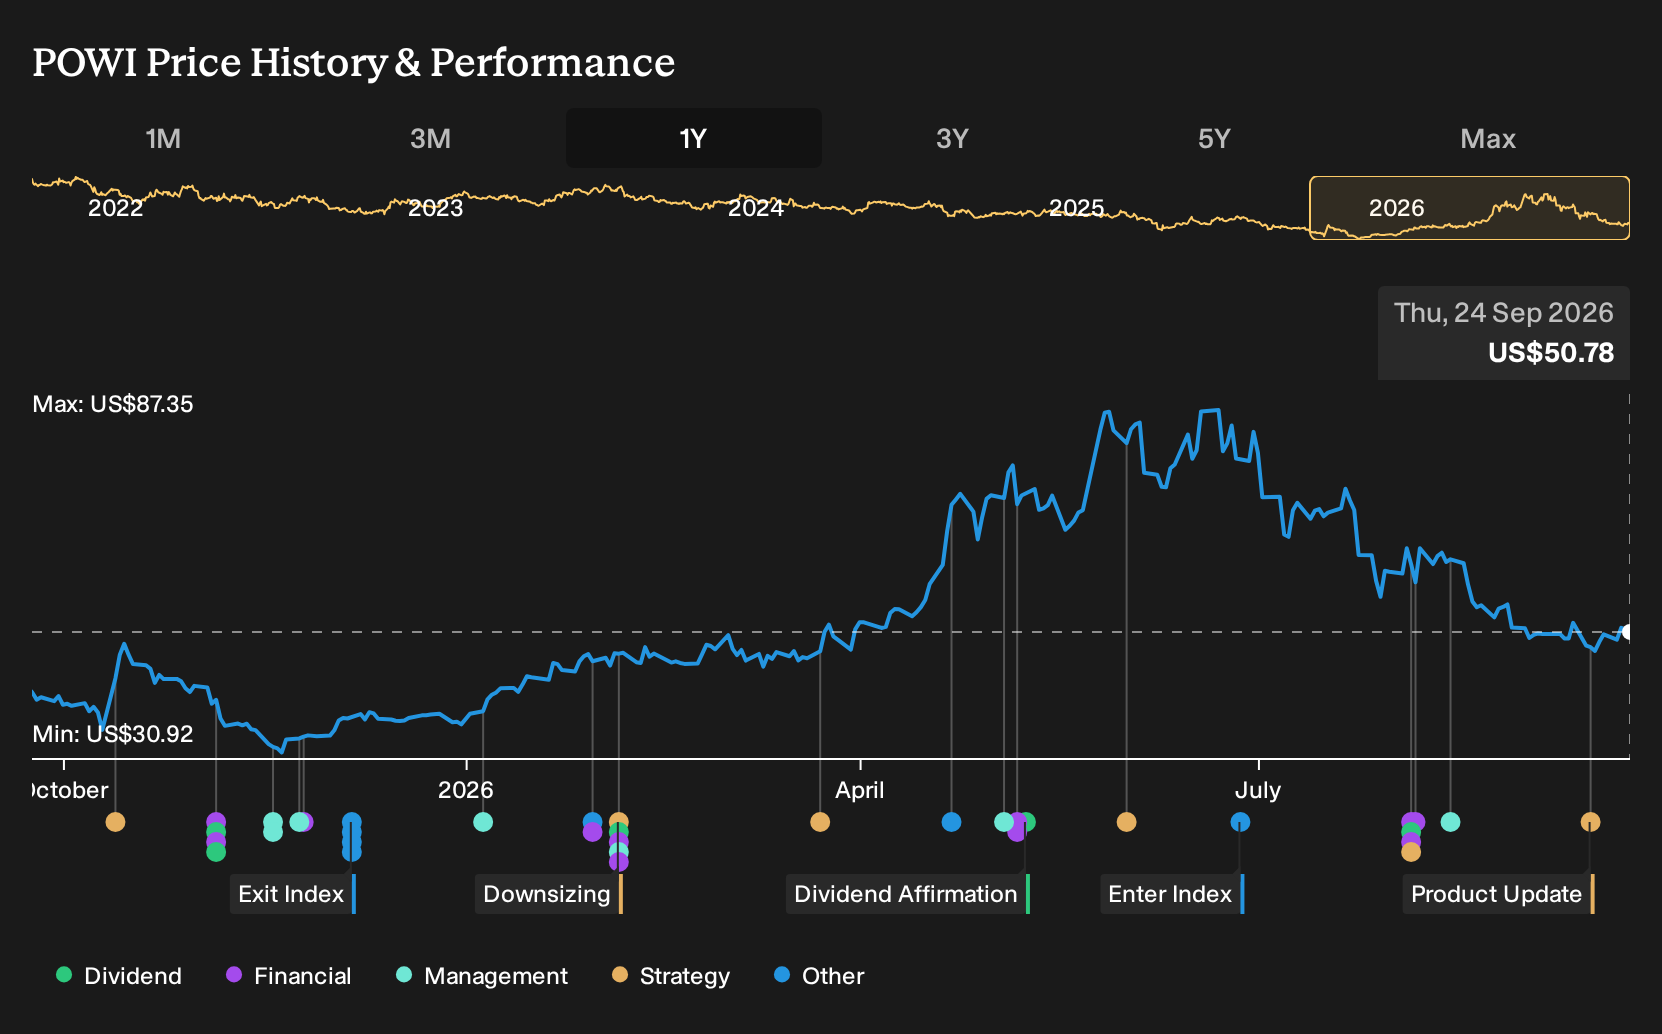
Exploring Other Perspectives
Some of the most optimistic analysts on Power Integrations lean on a different catalyst. They focus on GaN and data center potential, with top projections pointing to about US$733.6 million of revenue and US$165.7 million of earnings by 2029. These views were set before CAPZero-4, so your own read on this launch could shift that story.
Explore 3 other Power Integrations fair value estimates, including one that suggests as much as 67% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Power Integrations research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Power Integrations. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Power Integrations' overall financial health at a glance.
Looking for more investment ideas beyond Power Integrations?
If the Power Integrations story has you thinking about where else tighter standards, stronger balance sheets, or market mispricing could matter, it can help to cast a wider net with a structured stock search.
- For investors who want income to feel less fragile, consider starting with companies that screen as resilient payers through our 7 dividend fortresses.
- If the priority is limiting downside risk while still staying in the market, focus your research on businesses that appear more defensively positioned using the 31 resilient stocks with low risk scores.
- Those hunting for opportunities that the broader market may be overlooking can scan for underfollowed quality using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com