
Workiva (WK) Could Be 9% Undervalued On Its New AI Agent Push
Workiva (WK) put AI front and center at its Amplify 2026 conference, rolling out Agent Studio and new agentic tools that push deeper into regulatory reporting, audit, and governance automation.
For investors tracking Workiva, the Amplify 2026 announcements are landing against a mixed share price record. The stock has rallied, with a 90 day share price return of 45.7%. However, the year to date move is down 13.9%, and the 1 year total shareholder return has declined 14.6%. This points to improving short term momentum against a weaker multi year experience as the market reassesses growth prospects and execution risk around its AI push.
Scan how Workiva's AI push compares with other software players leaning into automation by reviewing the hand picked 37 profitable AI stocks that aren't just burning cash list for potential next ideas.
The AI story at Workiva just had a big upgrade, yet the share price record over 1 and 5 years still looks bruised. Does that mixed backdrop leave the risk reward skewed in buyers' favor or not?
Most Popular Narrative: 9% Undervalued
On the most followed valuation view, Workiva screens below that narrative fair value of $78.73, while the last close sits at $71.48. The gap is not extreme, yet it matters if you think the AI and reporting platform can deliver the growth assumptions baked into that model.
Workiva's focus on multi-solution platform deals and larger contracts, particularly with Fortune 50 and Fortune 100 companies, is anticipated to drive revenue growth through increased account expansion and higher contract values. There is a strong demand for Workiva's sustainability reporting solutions in light of new regulations like the CSRD in Europe, along with a growing market for science-based target reporting, which is expected to enhance their subscription revenues significantly.
See why 7 investors see Workiva as 9% undervalued.
Result: Fair Value of $78.73 (UNDERVALUED)
Still, the Workiva narrative can break if European sustainability rules shift materially, or if partner led deployments disappoint customers and curb the platform expansion story.
Find out about the key risks to this Workiva narrative.
Another View On Workiva’s Valuation
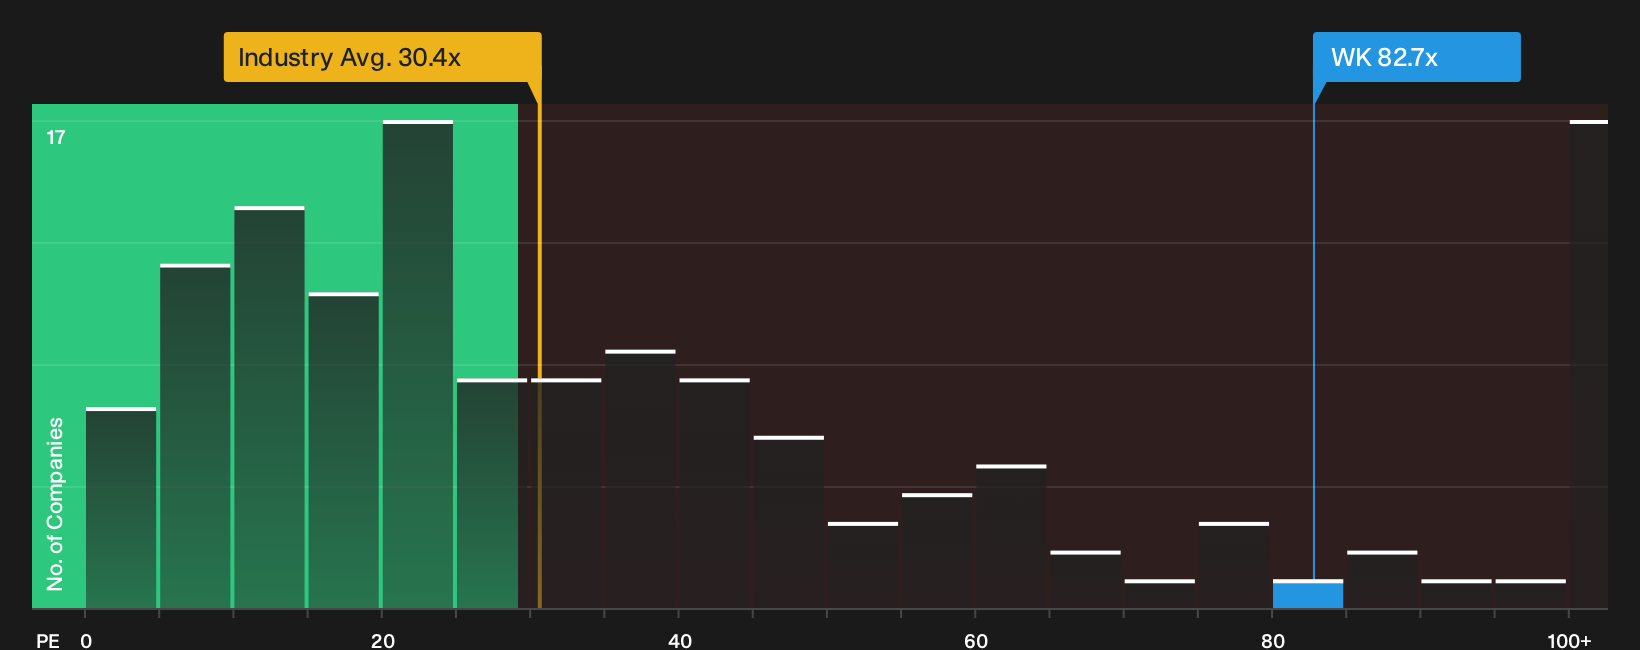
Workiva might screen as 9% below that $78.73 fair value in the narrative model, but the market’s current P/E of 82.7x tells a sharper story. The US Software group sits around 30.4x, peers cluster near 44.7x, and the fair ratio is 41.1x.
That means Workiva trades at roughly double the fair ratio level that regression work points to as a possible anchor. This can leave less room for error if growth or margins fall short. Is this a premium worth paying, or a signal to demand stronger evidence first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Workiva's valuation and AI push can feel messy. Move quickly and pressure test the data for yourself using the 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Workiva?
Workiva might be on your radar now, but your next strong move could come from widening the opportunity set across different styles of listed businesses.
- Chase potential outperformance by reviewing the 16 high quality undiscovered gems that combine strong fundamentals with lower investor attention.
- Strengthen portfolio resilience by scanning the list of solid balance sheet and fundamentals (23 results) to find businesses with sturdier financial footing.
- Dial down portfolio volatility by assessing the 31 resilient stocks with low risk scores that score well on stability metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com