
FTI Consulting (FCN) Stock Looks Like A Bargain Following Its 28% Slide
FTI Consulting has seen its share price slide over recent months, and that drop puts a spotlight on a simple question. Are investors now paying a price that matches what the company actually earns?
- Over the past 3 years, the stock has fallen 28.4%, which puts the current share price and its link to earnings firmly under the microscope.
- The recent appointment of Eileen Fargis to lead work in power, renewables and energy transition may support expectations for how FTI Consulting earns and times future fee income in those areas.
- The analysts covering FTI Consulting have run their own numbers. See what analysts think FTI Consulting's shares could be worth.
The issue now is whether FTI Consulting's current share price of US$130.45 is adequately supported by the earnings the business is generating.
If you are weighing FTI Consulting against other opportunities focused on value and earnings, it can help to see how it compares with 30 high quality undervalued stocks.
Is FTI Consulting a Bargain on Earnings?
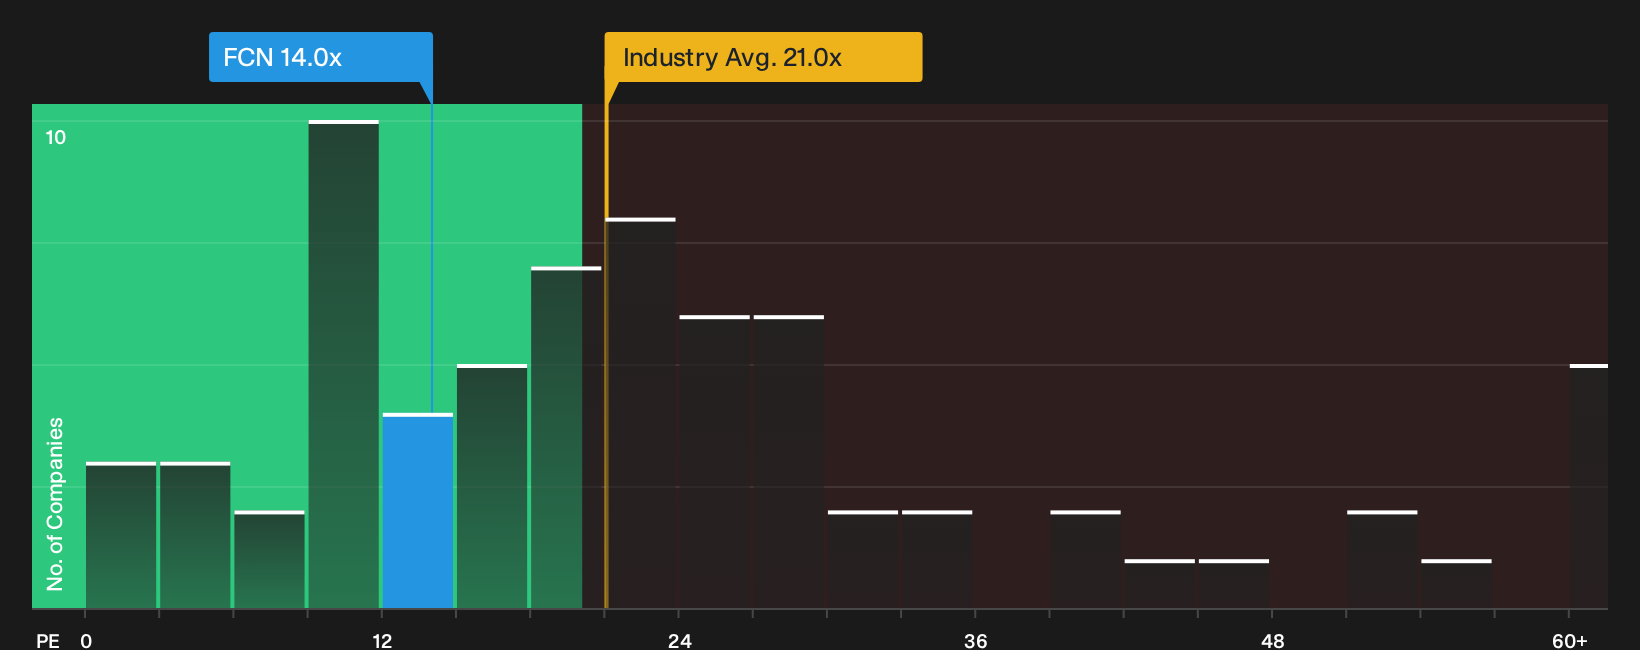
The P/E ratio is a useful way to think about FTI Consulting because the business is built around relatively steady fee income rather than heavy asset swings. At a P/E of 14.0x, the stock trades at a discount to both the Professional Services industry average of 21.0x and the peer group, which is nearer 20.3x.
On Simply Wall St's fair multiple framework, which blends factors such as profitability, scale and sector risk, FTI Consulting also trades below the P/E that model would imply. Because the recent appointment of Eileen Fargis expands its advisory reach into power, renewables and energy transition, this lower earnings multiple comes despite the company leaning into areas many investors watch closely. That gap between current and modelled P/E is what you would weigh to judge whether the shares look undervalued on this measure alone. Explore the numbers behind FTI Consulting's P/E valuation.
The FTI Consulting Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for FTI Consulting pick up where the valuation puzzle leaves off by spelling out which future growth, margin and earnings paths would need to play out for the stock to be worth materially more or materially less than today's share price. Each narrative treats FTI Consulting's fair value as a hypothesis about the business that you can revisit over time, rather than a one-off snapshot, and they sit on the company’s Community page.
One of the top community narratives on FTI Consulting: 26% undervalued
"The current valuation, alongside record share repurchases, reduced share count and ongoing capital returns, implies the market assigns limited credit…"
Discover why this Narrative puts FTI Consulting at 26% undervalued.
One more side of FTI Consulting that deserves your attention
Valuation only tells part of the story for FTI Consulting, and the research checks behind this article have flagged specific areas of concern that are worth weighing before you decide what to do next. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com