
What Sunbelt Rentals Holdings Stock's FTSE All World Addition Means For Shareholders
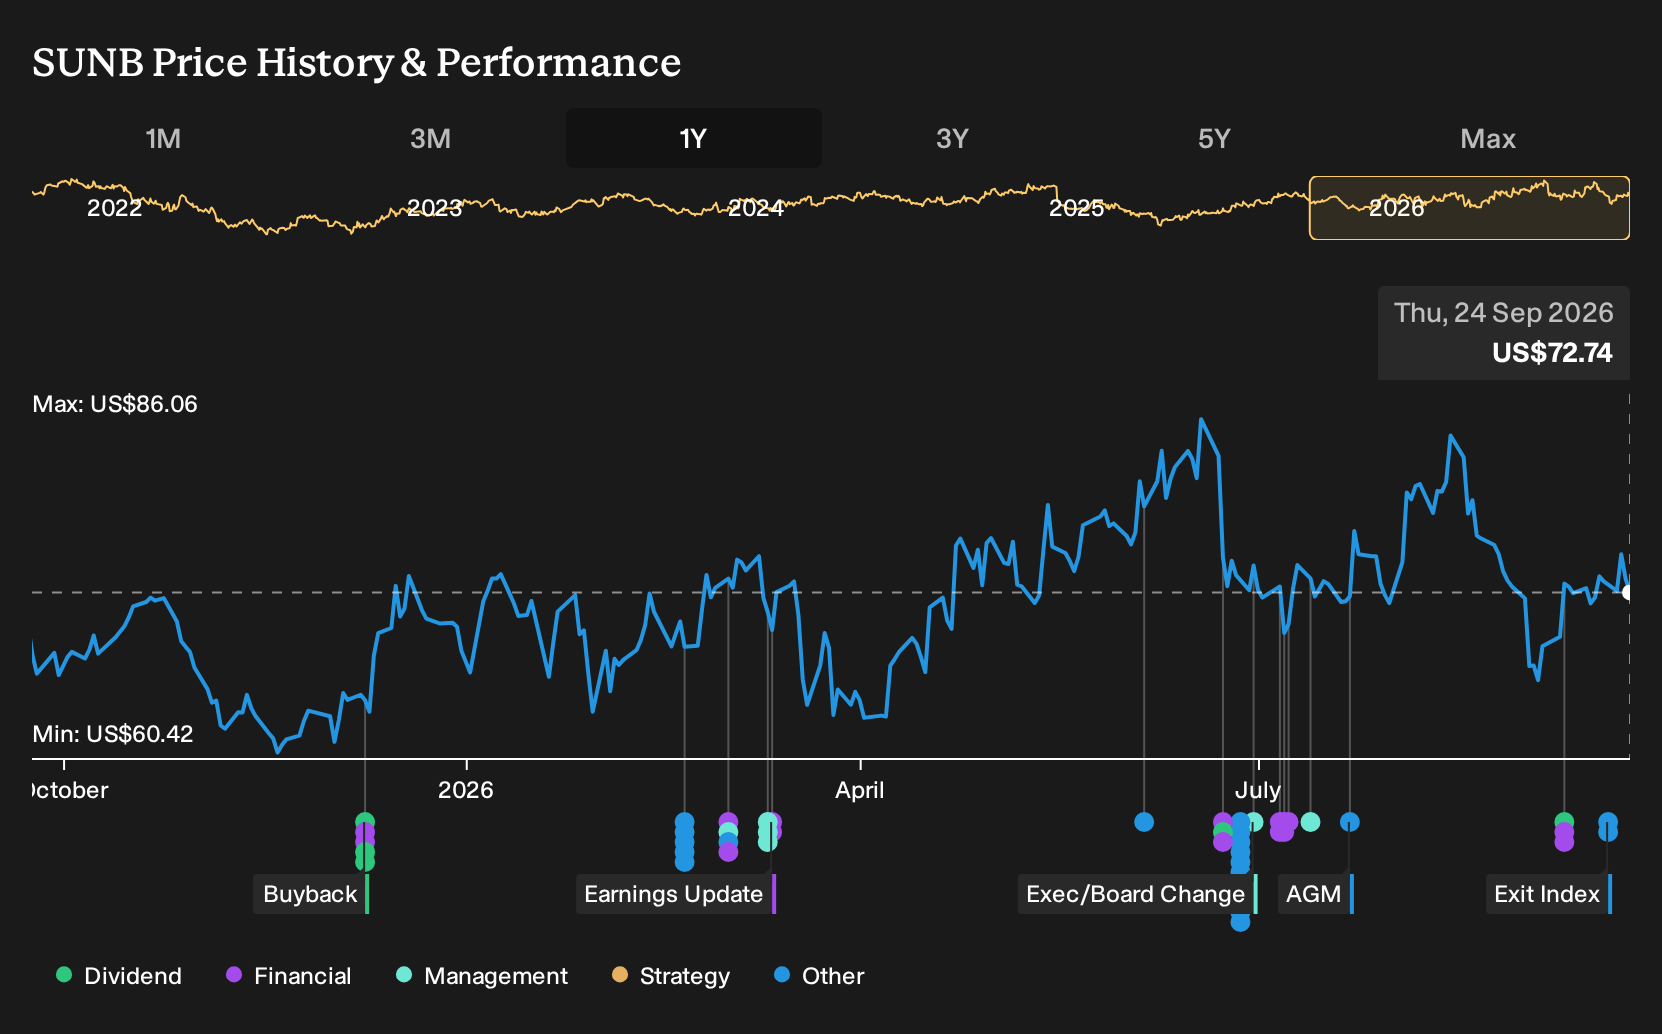
- Sunbelt Rentals Holdings shifted index exposure in September 2026, leaving the FTSE All-World Index in its LSE form and entering the same benchmark through its NYSE listing under ticker SUNB.
- This index reclassification matters for Sunbelt Rentals Holdings because benchmark tracking funds may now access the US listing more directly. This can reshape where liquidity concentrates across the group without altering the underlying equipment rental fundamentals.
- We will now explore how Sunbelt Rentals Holdings' NYSE based FTSE All-World inclusion could influence the existing investment narrative around project driven rental demand.
Compare Sunbelt Rentals Holdings' index shift with other equipment and infrastructure related opportunities by scanning our hand picked 39 power grid technology and infrastructure stocks poised to benefit from large scale project demand.
Sunbelt Rentals Holdings Investment Narrative Recap
To own Sunbelt Rentals Holdings, you need to believe in long duration rental demand from mega projects, specialty services and a broad North American footprint. In the near term, the story still leans on keeping fleet utilization healthy while managing debt and capital spending. The biggest swing factor remains how effectively Sunbelt executes its Sunbelt 4.0 efficiency and Specialty mix ambitions.
The main risk right now sits around leverage, falling net profit margins compared with last year and the sensitivity of construction activity to weaker project starts. The index switch between LSE and NYSE listings does not alter those fundamentals in a material way, although it may subtly change how liquidity and investor attention cluster around SUNB.
The most relevant development is the FTSE All World Index change itself, which drops Sunbelt Rentals Holdings from the index through its LSE shares and adds it back via the NYSE ticker. For you, the key question is where index tracking money and liquidity concentrate. That can affect trading spreads and how quickly news is reflected in the US listing.
Operationally, the thesis still turns on mega project exposure, Specialty growth and the ability to turn Sunbelt 4.0 initiatives into higher EBITDA margins and free cash flow. Index inclusion through NYSE does not create new contracts, but it can make SUNB more visible to US based benchmark funds, which may influence how the stock responds to future project wins or weaker construction indicators.
Sunbelt Rentals Holdings is modeled to reach US$13.5b in revenue and US$2.0b in earnings by 2029. This implies 6.7% yearly revenue growth and an earnings increase of about US$0.7b from US$1.3b today.
Uncover why Sunbelt Rentals Holdings' fair value indicates a 7% potential upside to its current price, which may represent a discount that could narrow faster than expected.
Exploring Other Perspectives
One alternative view on Sunbelt Rentals Holdings focuses on mega projects tying up equipment for long periods and limiting flexibility. The most cautious analysts were already baking in slower 6.0% annual revenue growth and earnings of about US$2.0b by 2029. These estimates came before the index switch, so opinions on risk and opportunity may shift.
Explore 2 other Sunbelt Rentals Holdings fair value estimates, including one that suggests there could be as much as 34% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sunbelt Rentals Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sunbelt Rentals Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sunbelt Rentals Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Sunbelt Rentals Holdings?
If the Sunbelt Rentals Holdings story has sharpened your thinking around project driven demand and index flows, it can be useful to stress test that framework against a wider watchlist. The Simply Wall St Screener helps you filter the market by balance sheet strength, income potential and valuation factors so you can line up Sunbelt alongside other candidates that fit your preferences.
- If capital preservation is front of mind, start with a focus on resilience and check out 31 resilient stocks with low risk scores that score strongly on financial risk metrics.
- For investors who care about fundamentals and staying power, build a watchlist from a list of solid balance sheet and fundamentals (23 results) that already meet strict debt and liquidity filters.
- If you want to hunt for less crowded opportunities, scan a 16 high quality undiscovered gems that combine quality traits with relatively low attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com