
Is Everforth (EFOR) Undervalued On Its Expanded Microsoft AI And Cloud Partnership?
Everforth (EFOR) stock is in focus after the company detailed an expanded Microsoft partnership that aligns its commercial and federal operations under a single model to deliver AI and cloud solutions at enterprise scale.
Recent trading tells a mixed story for Everforth. The share price has climbed 65.37% over the past 90 days and 2.76% over the last month, yet the year-to-date share price return is down 30.50% and the 1 year total shareholder return is down 31.48%, indicating a rebound in short-term momentum after a much tougher multi-year stretch.
Scan how Everforth's AI and cloud push with Microsoft compares to peers by reviewing the hand picked 84 AI infrastructure stocks now shaping large scale digital transformation projects.
Everforth has already staged a sharp 90 day rebound, yet the multi year drawdown and a flagged intrinsic discount of about 49% tell a different story. Is most of the upside still ahead, or already in the rearview mirror as valuation resets?
Most Popular Narrative: 19% Overvalued
The most followed narrative pegs Everforth's fair value at $27.33, which sits below the last close of $32.43. As a result, the story leans toward a valuation stretch that hinges on how the AI, cloud, and cybersecurity push converts into earnings.
Ongoing investments in cloud, AI, and cybersecurity solutions, supported by robust demand from both commercial and federal clients, are driving a growing pipeline of high-margin consulting contracts, positioning ASGN to benefit from clients' digital modernization roadmaps, which is likely to accelerate future revenue growth and improve overall net margins.
See why 3 investors see Everforth as 19% overvalued.
Result: Fair Value of $27.33 (OVERVALUED)
Still, the narrative wobbles if Commercial demand stays soft or if the federal contract mix keeps skewing to lower margin work, which would pressure Everforth’s earnings story.
Find out about the key risks to this Everforth narrative.
Another Take On Everforth’s Valuation
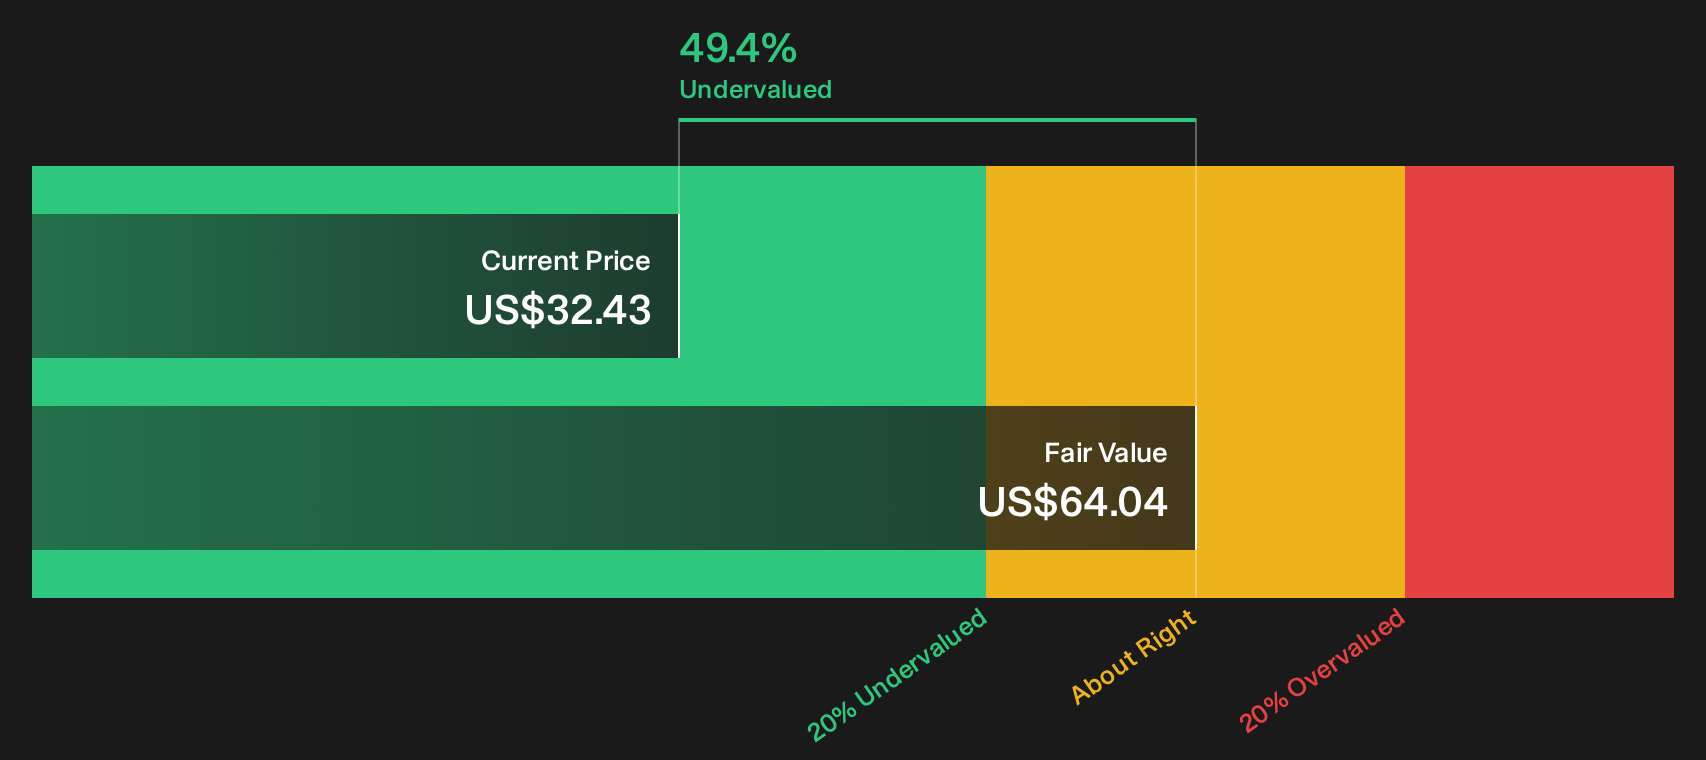
Analysts see Everforth as roughly 19% overvalued based on their $27.33 fair value, yet Simply Wall St’s DCF model points the other way. On that cash flow view, EFOR at $32.43 trades at a steep discount to a $64.04 estimate. Which lens do you trust more for a long term call?
Look into how the SWS DCF model arrives at its fair value.Look into how the SWS DCF model arrives at its fair value.
Next Steps
Everforth's mixed sentiment leaves plenty of room for debate, so move fast, pull up the data, and pressure test your own thesis against the 3 key rewards and 4 important warning signs.
Looking for more Everforth investment ideas?
Do not stop your research with Everforth. Use the Simply Wall St screener to spot fresh opportunities before they move and keep your watchlist one step ahead.
- Target potential mispricings by scanning a focused universe of 30 high quality undervalued stocks that combine quality fundamentals with attractive pricing signals.
- Prioritize resilience by reviewing 31 resilient stocks with low risk scores that score well on financial strength and volatility, so capital is working in steadier territory.
- Hunt for tomorrow's stories early by combing through 16 high quality undiscovered gems that have solid underlying metrics before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com