
Should Ima Gas Project Approval Require Action From TotalEnergies Stock Investors?
- TotalEnergies and partner AMNI have already taken final investment decision on the Ima offshore gas field in Nigeria, planning a single platform tied by a 22 km pipeline to Nigeria LNG and targeting about 350 million cubic feet of gas per day from 2028.
- The Ima project is framed as a low cost, low emissions development with strong Nigerian content, supplying roughly one third of the gas for Nigeria LNG’s Train 7 expansion while relying heavily on local contractors and community hiring.
- The next step is to assess how TotalEnergies’ investment narrative could be influenced by this low cost Nigerian LNG supply decision.
Scan for other energy stocks pursuing lower cost, lower emissions growth by reviewing the curated 230 resilient stocks with low risk scores, which may offer resilient balance sheets alongside measured expansion plans.
TotalEnergies Investment Narrative Recap
To hold TotalEnergies, you need to believe its blend of oil, gas, LNG and power can stay cash generative even if global oil demand or pricing soften and if earnings expectations for the next three years remain muted. The Ima gas FID reinforces this mix by adding future LNG linked to an existing export hub, but the impact on near term results and on the key LNG growth story looks modest given the 2028 start date.
The bigger short term swing factor still comes from commodity prices and refining and chemicals margins, where structural overcapacity can squeeze profitability. On the risk side, Ima underlines ongoing exposure to higher risk regions and heavy capital needs. Any delay to farm downs, disposals or big projects would keep financial pressure and could limit flexibility for shareholder payouts if conditions weaken.
The most relevant related move is the partnership with Global Infrastructure Partners, part of BlackRock, around African oil and gas infrastructure. That deal brings a €1.8b capital injection in exchange for a throughput based tariff over up to 15 years, which gives TotalEnergies extra balance sheet room while it lines up new LNG volumes such as Ima.
For you as a shareholder, the link is simple. More capital from an infrastructure partner can help fund lower cost, lower emissions gas developments without stretching gearing, while still keeping exposure to volumes and tariffs. The trade off is a long term payment obligation and continued concentration in politically sensitive regions, which keeps execution, regulatory and operational risk firmly on the table.
TotalEnergies' narrative projects US$199.2b revenue and US$19.4b earnings by 2029. This assumes relatively flat yearly revenue trends and an earnings increase of about US$1.6b from the current US$17.8b level.
Uncover why TotalEnergies' fair value indicates a 4% potential upside to its current price that could narrow quickly.
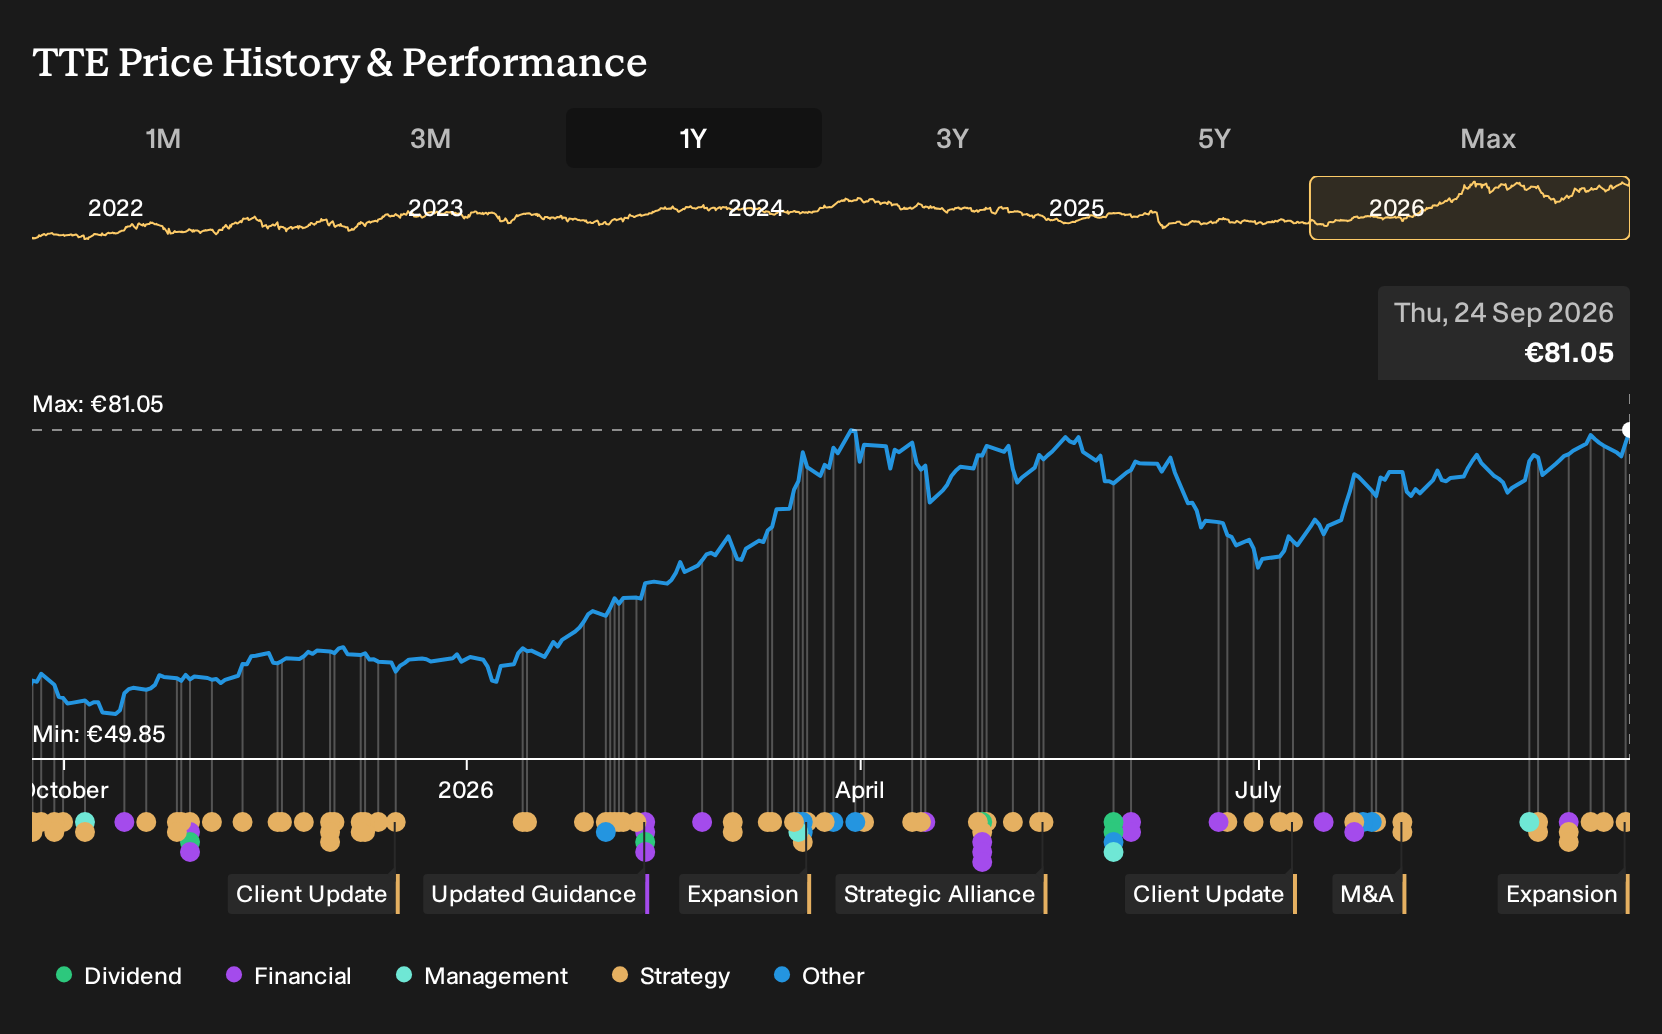
Exploring Other Perspectives
You can also consider the sharper risks highlighted by bearish analysts who see TotalEnergies facing shrinking hydrocarbon demand and possible stranded assets. They were estimating revenue of about US$141.5b and earnings near US$16.2b by 2029. The Ima gas FID could prompt those assumptions to change, so weigh both perspectives carefully before forming a view.
Explore 8 other TotalEnergies fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TotalEnergies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TotalEnergies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TotalEnergies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TotalEnergies?
If the TotalEnergies story has sharpened your thinking about risk, returns and balance sheet strength, it can be useful to compare it with other stocks that share some of the same qualities. The Simply Wall St Screener lets you quickly filter for different profiles so you can build a watchlist that actually fits your own tolerance for volatility, income needs and time horizon.
- If you care most about financial resilience, start with a curated list of solid balance sheet and fundamentals (200 results) that can help you find businesses with room to handle shocks without aggressive leverage.
- If value is your priority, scan through the 179 high quality undervalued stocks that filters for companies combining healthier fundamentals with prices that may not fully reflect them.
- If income is front and centre for you, review the 157 dividend fortresses that focuses on higher yielding dividend payers with an eye on stability as well as payout size.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com