
How Investors May Respond To Synaptics (SYNA) Isaac Sim Touch Integration
- Synaptics announced that its first CTS module powered by the SN6012T touch controller is now supported in NVIDIA Isaac Sim, enabling simulated contact and pressure sensing for dexterous robotic hands, grippers, and other Physical AI systems.
- The CTS module’s high taxel density, fast response sensor design, and native support for NVIDIA’s Newton physics engine position Synaptics’ Astra Edge AI processors as a coordination hub for touch, vision, and motor control in complex robotics projects.
- We will now see how Synaptics’ tighter integration of tactile sensing with NVIDIA Isaac Sim could influence the broader Edge AI investment narrative.
Scan beyond Synaptics and this Isaac Sim partnership by lining up other Physical AI and robotics plays through the curated 93 robotics and automation stocks.
Synaptics Investment Narrative Recap
To own Synaptics, you need to believe the pivot toward Core IoT and Edge AI can offset pressure from older product lines and move the business toward consistent profitability. The Isaac Sim support for its CTS module fits that story, because it puts Synaptics directly into higher value Physical AI and robotics workflows rather than just selling standalone components.
In the near term, the key swing factor is execution on that solutions push and scaling the customer base beyond a small group of early adopters. The biggest risk stays the same. Management still has to trim or repurpose lower return categories while carrying debt that is not well covered by operating cash flow.
The Astra Edge AI processor platform that underpins this CTS module integration is the announcement that matters most here. It aggregates touch, vision, and motion into unified streams and hands them off to NVIDIA Holoscan. For you as an investor, that is Synaptics trying to sell into full systems where its silicon content and software matter, not just single chips.
This also sits alongside the firm’s wider Core IoT focus, where analysts already flag a solid pipeline of Wi Fi 7 and edge AI products. Execution risk does not go away. Synaptics still needs better channels, more industrial IoT traction, and disciplined R&D spending. The Isaac Sim alignment simply gives one more concrete use case to watch as a proof point for that broader thesis.
Synaptics' current analyst narrative points to forecast revenues of US$1.6b and earnings of US$21.2 million by 2029. That path assumes revenue growth of 9.4% per year and an earnings swing of roughly US$512 million from a loss of US$490.8 million today to the projected profit. The move from current results to the consensus forecast is framed as a multi hundred million dollar turnaround rather than a modest tweak to the income statement.
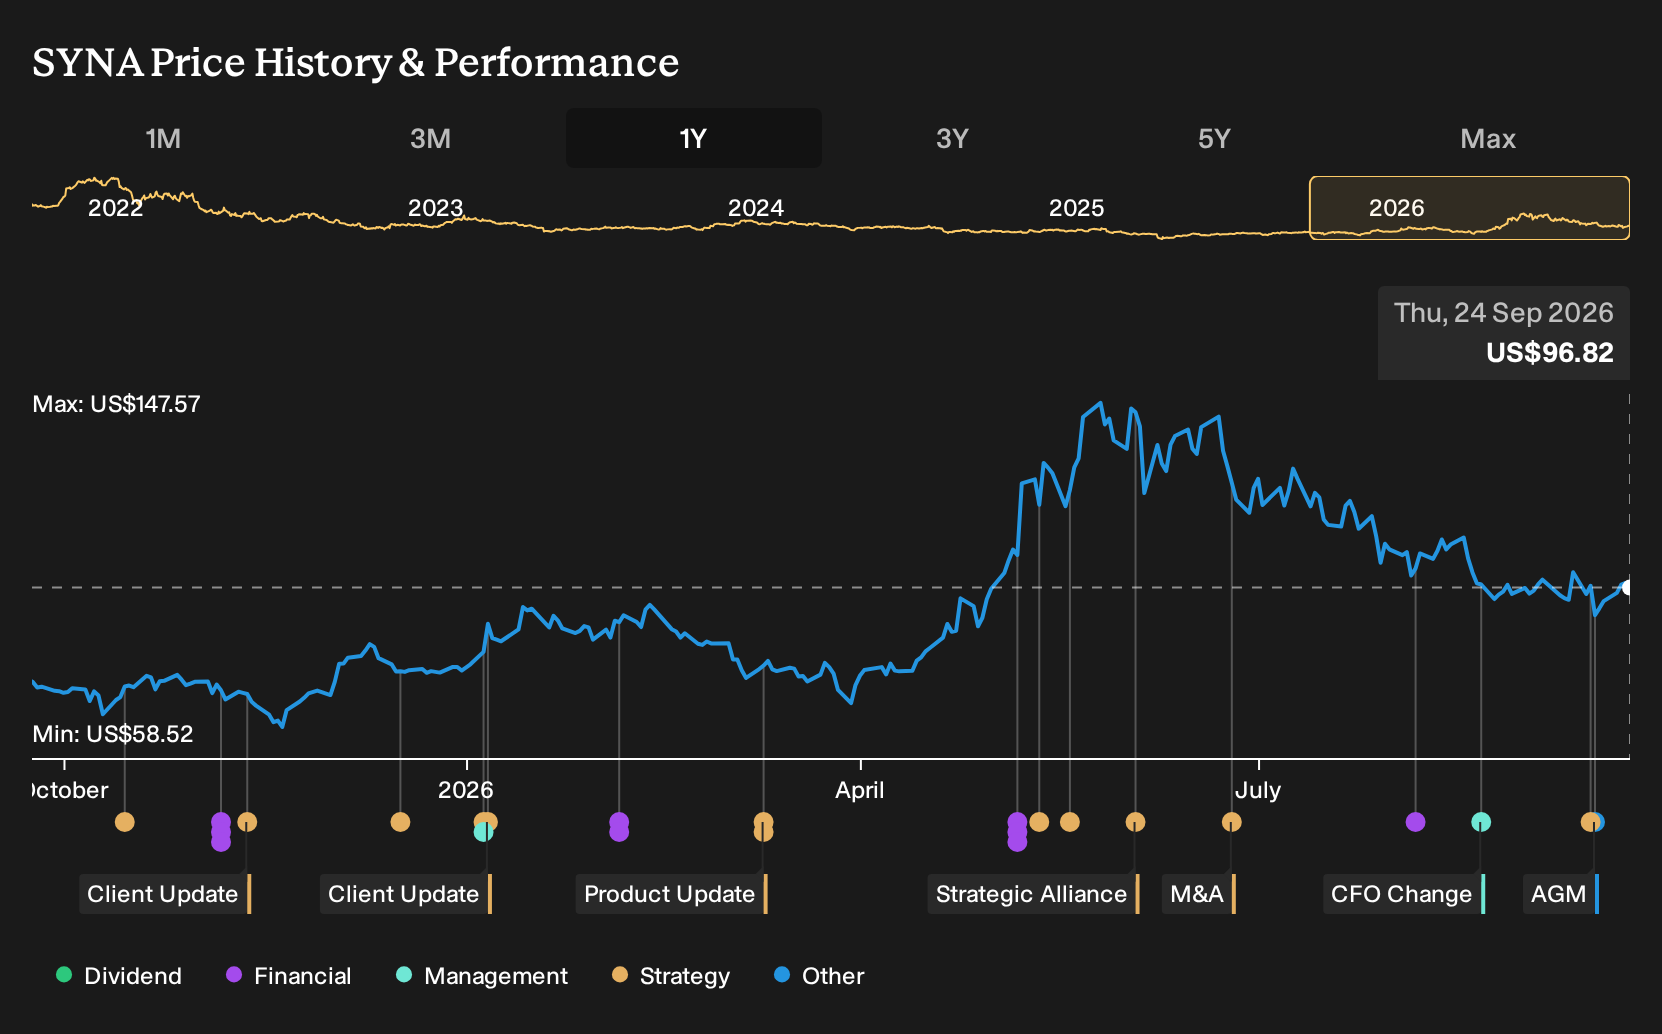
Uncover why Synaptics' fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Synaptics as a Physical AI and robotics winner, with forecasts of US$1.7b in revenue and US$190.4 million in earnings by 2029. You now have this Isaac Sim touch sensing link on top. That could push expectations higher, or serve as a reminder that opinions can differ widely, so explore several viewpoints before deciding where you sit.
Explore 4 other Synaptics fair value estimates, including one that suggests as much as 74% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so follow your instincts.
- A great starting point for your Synaptics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Synaptics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synaptics' overall financial health at a glance.
Looking For More Ideas Beyond Synaptics?
Once you have a view on Synaptics, it often helps to compare it with a few other candidates that fit different roles in a portfolio. The Simply Wall St Screener can surface a mix of resilience, income, and under-the-radar potential in a few clicks.
- If capital preservation sits high on your list, filter for steadier profiles using the 30 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors focused on income, scan for potential yield opportunities through the 7 dividend fortresses that might help support regular cash flows.
- Those hunting for potential mispriced opportunities can cast a wider net with the 30 high quality undervalued stocks that highlight companies with quality fundamentals at compressed valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com