
Liquidity Services (LQDT), The Latest Update Raises A Bigger Question
The latest move in Liquidity Services (LQDT) is tied to analysts lifting earnings estimates, alongside a strong rating and solid momentum metrics that together appear to be drawing fresh investor attention.
The recent 1-day share price return of 1.58% leaves Liquidity Services trading at $43.40. This caps a strong year-to-date share price return of 46.65% and a 1-year total shareholder return of 58.49%, which together point to building momentum as earnings expectations reset higher.
Scan how Liquidity Services fits into a broader watchlist and compare its momentum against a hand picked group of 30 high quality undervalued stocks that also pair strong performance with solid fundamentals.
Bulls see Liquidity Services as a reset story as earnings forecasts climb and the share price follows, while bears worry the move already reflects the good news. Which case does the current valuation actually support?
Price-to-Earnings of 40.9x: Is it justified?
Valuation is where the Liquidity Services story gets more complicated, because the stock trades on a P/E of 40.9x while our model suggests the shares are trading at a discount to estimated fair value.
The P/E multiple compares Liquidity Services' current share price with its earnings per share, so a higher figure often signals that investors are willing to pay more today for each dollar of profit. For a business that runs online marketplaces for surplus assets and retail returns, that can reflect expectations for earnings to keep improving as more volume moves through its platforms.
For Liquidity Services, the P/E of 40.9x is described as expensive relative to both the US Commercial Services industry average of 18x and the estimated fair P/E of 23.6x. That gap is wide. This implies the market is already pricing in a strong earnings path and a relatively clean execution story, and any wobble in profit delivery could see that premium move closer to the fair ratio level.
Explore the SWS fair ratio for Liquidity Services.
Result: Price-to-Earnings of 40.9x (OVERVALUED)
Still, Liquidity Services depends heavily on US revenue concentration and continued profitability. As a result, any segment stumble or contract loss could quickly challenge that premium story.
Find out about the key risks to this Liquidity Services narrative.
Another view on Liquidity Services valuation
The P/E looks rich, yet the SWS DCF model paints a different picture. On that view, Liquidity Services trading at $43.40 sits about 20.9% below an estimated future cash flow value of $54.83. Is this a genuine pricing gap or just a different way of looking at the same risk?
Look into how the SWS DCF model arrives at its fair value.
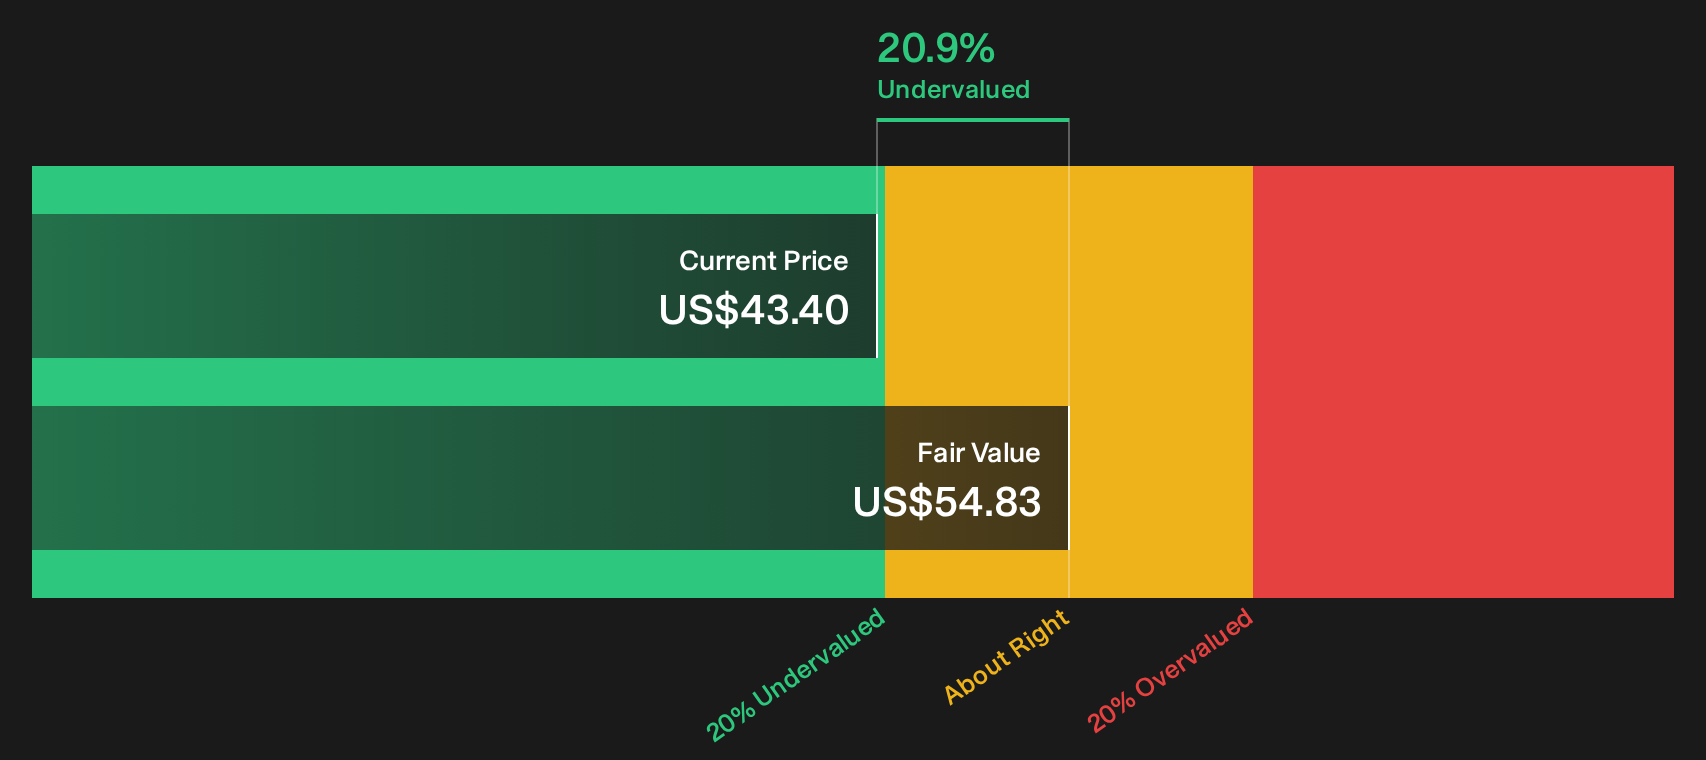
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Liquidity Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone on Liquidity Services so far leaves you undecided, review the underlying data yourself and act quickly to form your own view with the 3 key rewards
Looking for more investment ideas beyond Liquidity Services?
Do not stop your research with Liquidity Services alone. Broaden your watchlist and pressure test your thesis against other opportunities that could fit your style and risk comfort.
- Target potential mispricings early by scanning a curated pool of 30 high quality undervalued stocks that combine quality fundamentals with room for sentiment to catch up.
- Strengthen capital protection by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with healthier finances.
- Get ahead of the crowd by searching through a 16 high quality undiscovered gems that surfaces lesser-known opportunities before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com