
Why Digi International (DGII) Is Getting Fresh Attention
Particle by Digi International (DGII) has secured Skylo certification for its M635e module, a move that formalizes satellite plus cellular connectivity for IoT projects and tightens the link between Digi’s product roadmap and real world deployment needs.
The Skylo certification comes at a time when Digi International’s shares have strong momentum, with a 7-day share price return of 5.63% and a year-to-date share price return of 77.83%. The 1-year total shareholder return of 107.80% and 5-year total shareholder return of 265.13% indicate continued investor appetite for the story.
Scan for more IoT and connectivity plays showing similar momentum to Digi International by running a curated screen of 84 AI infrastructure stocks in the current market backdrop.
Digi International’s run and the Skylo certified launch put fresh momentum on the table. The practical question now is whether that justifies paying today’s price or waiting for a calmer entry. This is considered before the numbers section that follows.
Most Popular Narrative: 10.1% Undervalued
Digi International’s most followed valuation story pegs fair value at $85.40 against a last close of $76.75, which puts the current debate on whether that gap is justified or fragile.
The accelerating transition of customers to Digi's subscription-based and recurring revenue solutions, including higher attach rates on IoT products such as cellular routers and infrastructure management devices, points to ongoing double-digit annual recurring revenue (ARR) growth and improved profit margins, boosting both revenue stability and long-term earnings.
See why 3 investors see Digi International as 10% undervalued.
This widely followed framework uses an 8.88% discount rate and assumes Digi International can grow revenue from $506.2m to $646.4m by 2029 while expanding profit margins from 9.6% to 18.1% and reaching earnings of $117.2m. For that path to line up with the $85.40 fair value, the shares would need to trade on a 37.8x P/E on those 2029 earnings, compared with a current multiple of 57.4x that sits above the 31.3x P/E cited for the wider US Communications industry.
Those numbers leave you weighing two main questions. First, how comfortable you are with the reliance on recurring revenue and margin expansion at a time when management has flagged flat year over year revenue for 2025 and regional softness in areas like APAC and parts of Europe. Second, whether a higher future P/E than the sector average feels reasonable if competition, tariff shifts or a slower hardware to software mix change end up squeezing the earnings trajectory that underpins this narrative.
Result: Fair Value of $85.40 (UNDERVALUED)
Still, the narrative can break if recurring revenue slows while management is guiding to flat 2025 sales, or if APAC and European softness lasts longer than expected.
Find out about the key risks to this Digi International narrative.
Another View: Digi International Through The P/E Lens
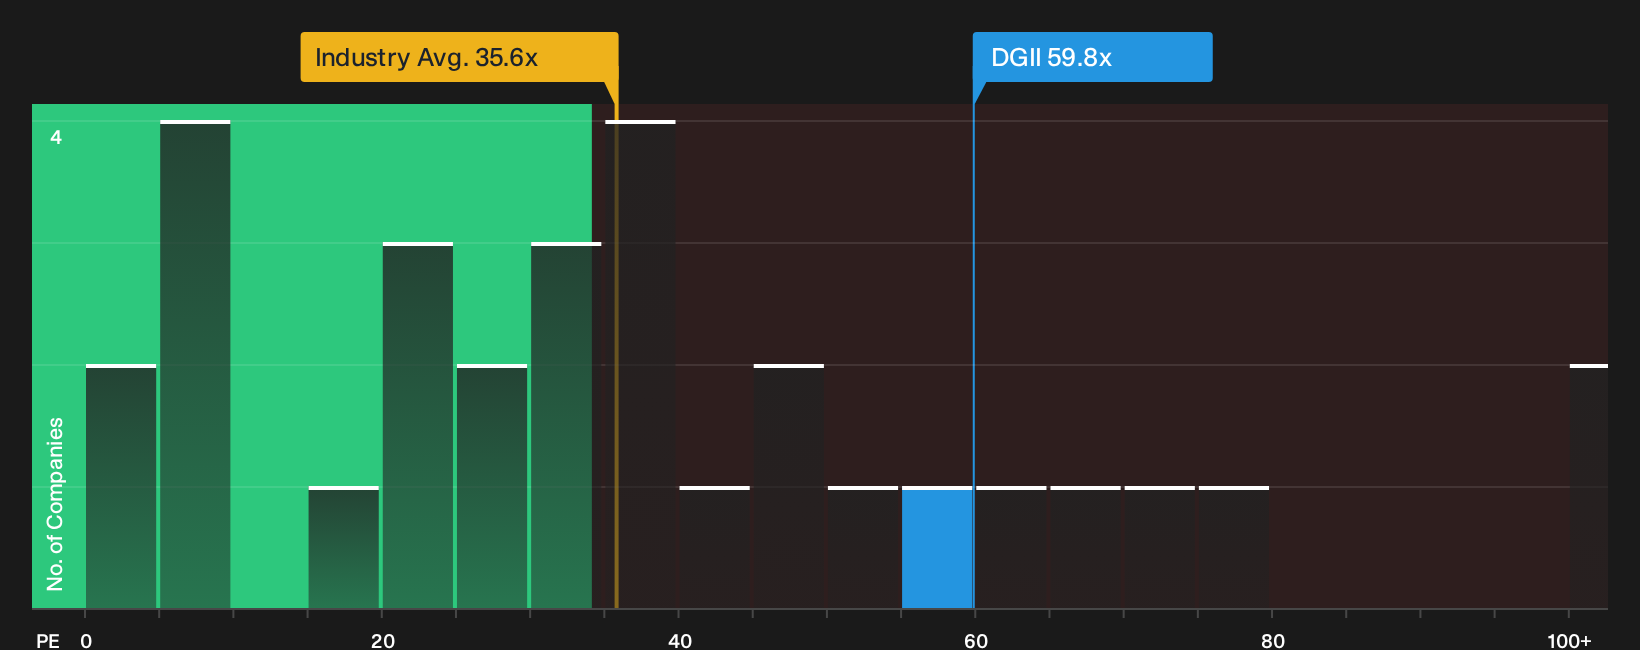
The first story cast Digi International as 10.1% undervalued based on future earnings and cash flows. A simple P/E check paints a tougher picture. The stock trades on 59.8x earnings versus 35.6x for the US Communications group, 36.9x for peers and a fair ratio of 31.7x. That is a wide premium. The question is whether you see that gap as justified strength or valuation air that could compress.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong optimism can cut both ways, so it helps to check the underlying data yourself and decide where you stand while sentiment is hot. To see what the current set of positives looks like in detail, review the 3 key rewards.
Looking for more Digi International style ideas?
If Digi International has sharpened your focus, do not stop here. Use the Simply Wall St Screener to spot other opportunities before the crowd moves first.
- Target potential mispricing by scanning a 30 high quality undervalued stocks that pairs stronger balance sheets with cash generation.
- Build income-focused watchlists by checking a 7 dividend fortresses that filters for higher yields with payout support.
- Protect your downside by reviewing a 30 resilient stocks with low risk scores that scores companies on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com