
What NetApp (NTAP)'s Buccaneers Partnership Means For Shareholders
- NetApp announced it became an Official Partner of the Tampa Bay Buccaneers, extending its NFL relationship as the league's Official Intelligent Data Infrastructure Partner and deploying its Keystone subscription service to support fan experience and football operations data.
- The Buccaneers' move to NetApp Keystone highlights how subscription-based, hybrid cloud storage is being used in demanding, real-time sports workloads. This gives investors a concrete example of how NetApp's as-a-service model is applied beyond traditional enterprise IT.
- We will now look at how NetApp's expanded Buccaneers partnership and Keystone deployment could influence the overall investment narrative.
Scan how NetApp’s NFL data push compares with other infrastructure driven opportunities by reviewing the hand picked 84 AI infrastructure stocks now shaping digital workloads across sectors.
NetApp Investment Narrative Recap
To stay comfortable as a NetApp shareholder, you need to believe the shift toward hybrid cloud, AI workloads, and subscription storage continues to support its software and services mix, even as traditional hardware revenue faces pressure. The Buccaneers deal is helpful branding for Keystone and real time workloads, but it does not materially change the near term demand picture.
The key short term swing factor remains execution in public cloud and Keystone, where growth and margins are watched closely against hyperscaler pressure. The biggest risk still sits in further weakness in legacy product sales and tougher pricing, which could weigh on overall revenue growth and profitability if mix does not keep improving.
Among the recent disclosures, the amended and restated charter and bylaws in September 2026 appear most significant for governance around this NFL and Keystone push. Officer exculpation, clarified indemnification limits, and tighter rules on stockholder associated persons all relate to how NetApp manages legal exposure as deal flow and partnerships scale.
For you, this connects directly back to catalysts and execution risk. A firm leaning into complex cloud partnerships, AI workloads, and large entertainment or sports clients may benefit from clearer board authority and committee powers, but investors still need to watch how these governance changes balance accountability, especially with significant insider selling reported over the past three months.
NetApp's current analyst framework points to US$9.3b in revenue and US$1.9b in earnings by 2029. That view implies 8.1% yearly revenue growth and an earnings increase of about US$500m from US$1.4b today.
Uncover why NetApp's fair value is aligned with its current price.
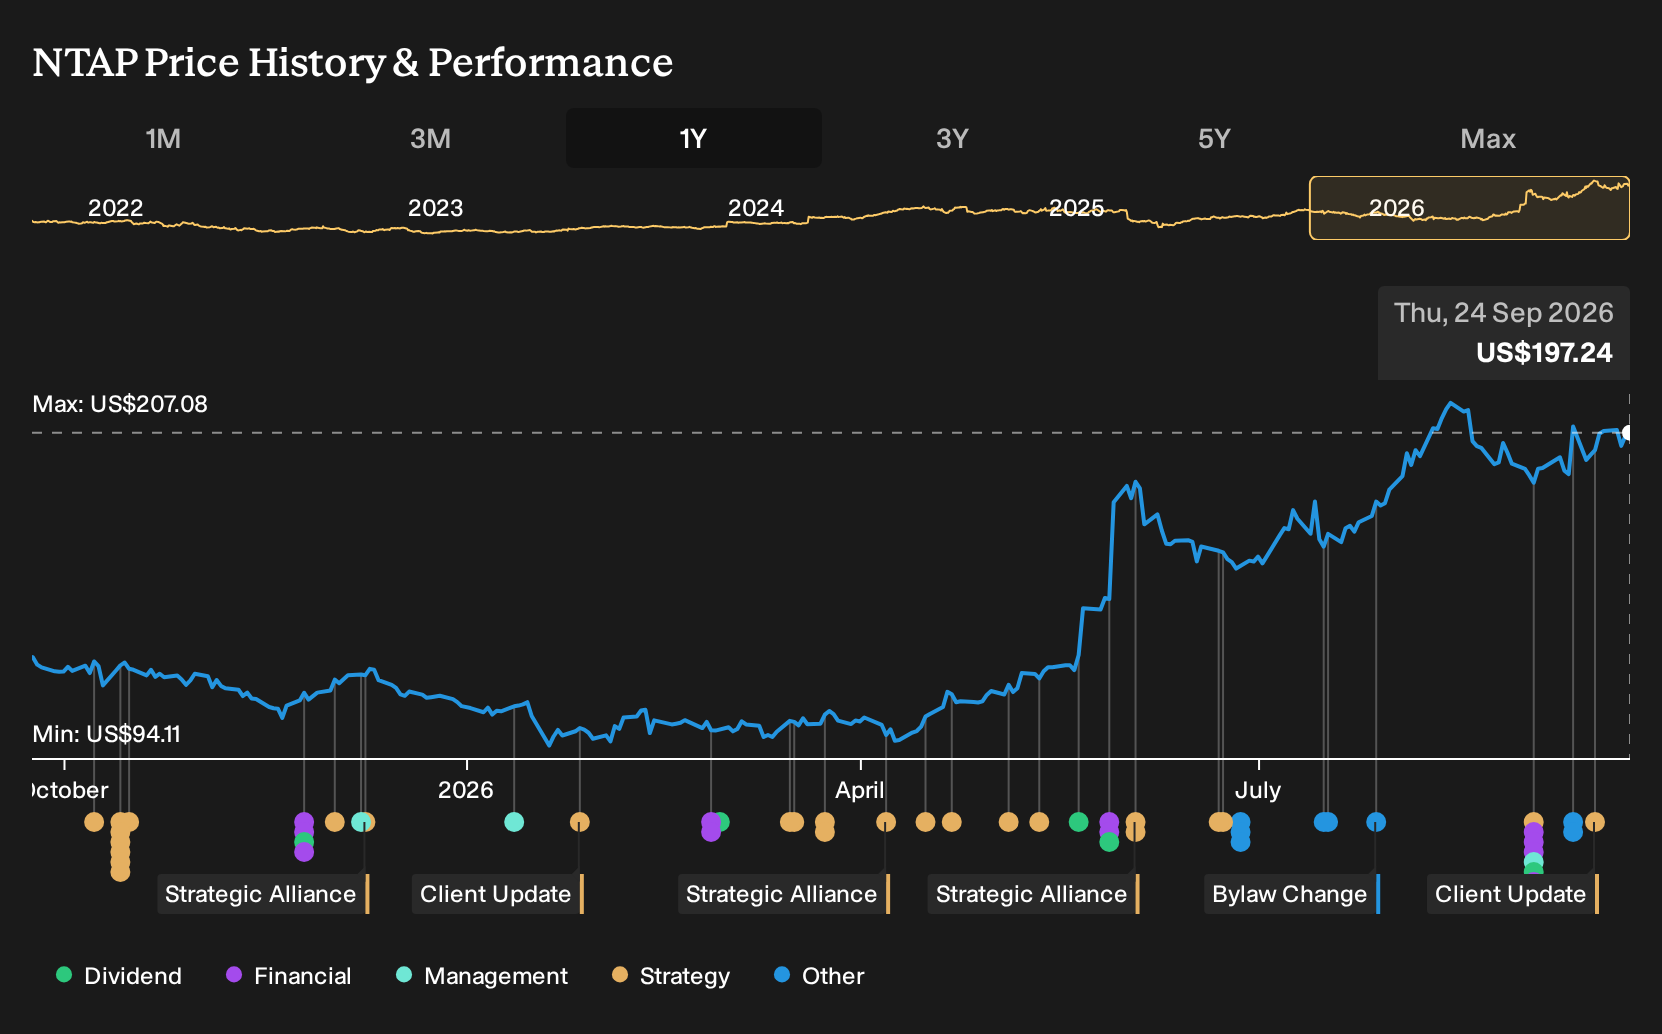
Exploring Other Perspectives
For NetApp, the alternate view leans hard into Keystone as a catalyst. The most optimistic analysts were already modeling about US$8.6b in revenue and US$1.7b in earnings by 2029 before this Buccaneers deal, so you might see those expectations rise further or be challenged as fresh data points reshuffle opinions.
Explore 3 other NetApp fair value estimates, including one that suggests potential upside of up to 21% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment performance rarely comes from following the herd, so trust your own analysis.
- A great starting point for your NetApp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetApp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetApp's overall financial health at a glance.
Looking for more NetApp sized opportunities?
If this NetApp story has you thinking about where else subscription models, strong balance sheets, or income potential might matter, it can help to scan a broader set of companies that fit clear, data backed filters using the Simply Wall St Screener.
- For investors focused on financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (24 results). These companies can handle shocks while still funding growth plans.
- If income is a priority and you want yields that may support your portfolio’s cash flow, zero in on 7 dividend fortresses. These combine payout strength with underlying fundamentals.
- When you want growth potential without paying up for hype, look across a 16 high quality undiscovered gems. These have solid metrics but limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com