
3 European Stocks That May Be Undervalued By Up To 23.3%
European markets have recently experienced volatility due to escalating Middle East tensions, which drove energy prices higher and reinforced inflation concerns. Despite these challenges, opportunities may exist for investors seeking undervalued stocks that could benefit from stabilizing conditions and strategic positioning in the market. Identifying such stocks often involves assessing their intrinsic value relative to current market prices, especially in sectors that may recover as macroeconomic pressures ease.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Sulzer (SWX:SUN) | CHF150.50 | CHF264.85 | 43.2% |
| Promotica (BIT:PMT) | €2.98 | €5.79 | 48.5% |
| Marimekko Oyj (HLSE:MEKKO) | €9.48 | €16.81 | 43.6% |
| KSB SE KGaA (XTRA:KSB) | €882.00 | €1758.42 | 49.8% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.97 | €23.11 | 48.2% |
| Frequentis (XTRA:FQT) | €66.90 | €113.83 | 41.2% |
| Embla Medical hf (CPSE:EMBLA) | DKK27.35 | DKK46.66 | 41.4% |
| DWS Group GmbH KGaA (XTRA:DWS) | €71.35 | €126.82 | 43.7% |
| Boliden (OM:BOL) | SEK518.00 | SEK1012.65 | 48.8% |
| Apator (WSE:APT) | PLN24.70 | PLN48.77 | 49.4% |
Below we spotlight a couple of our favorites from our exclusive screener.
Vestas Wind Systems (CPSE:VWS)
Overview: Vestas Wind Systems A/S is involved in the design, manufacture, installation, and servicing of wind turbines across the United States, Denmark, and internationally with a market capitalization of DKK195.75 billion.
Operations: The company's revenue is primarily derived from Power Solutions, which generated €16.67 billion, and Service, which contributed €3.63 billion.
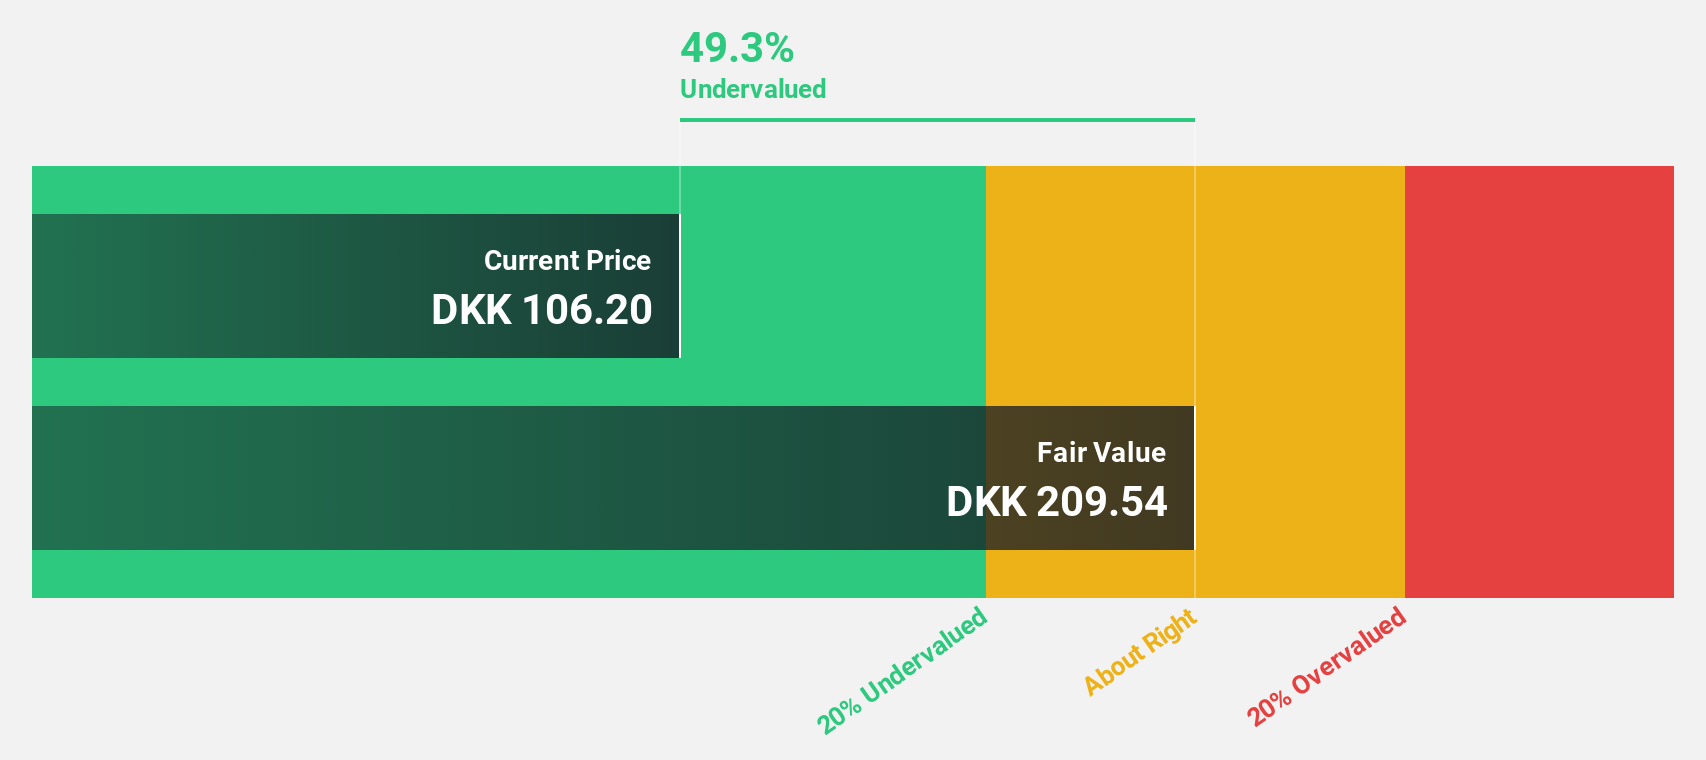
Estimated Discount To Fair Value: 23.3%
Vestas Wind Systems is trading at 23.3% below its estimated fair value, with its stock price significantly undervalued relative to future cash flow projections. Recent earnings results show substantial growth, with second-quarter net income rising to €280 million from €32 million a year ago. The company has raised its EBIT margin guidance for 2026, reflecting improved operational efficiency. Despite volatile share prices and modest revenue growth forecasts, Vestas offers strong relative value compared to peers.
- Insights from our recent growth report point to a promising forecast for Vestas Wind Systems' business outlook.
- Take a closer look at Vestas Wind Systems' balance sheet health here in our report.
Auto Partner (WSE:APR)
Overview: Auto Partner SA imports and distributes parts for passenger cars, delivery vans, and motorcycles in Poland, with a market cap of PLN3.86 billion.
Operations: The company's revenue is primarily derived from the sale of spare parts and accessories to motor vehicles, totaling PLN4.67 billion.
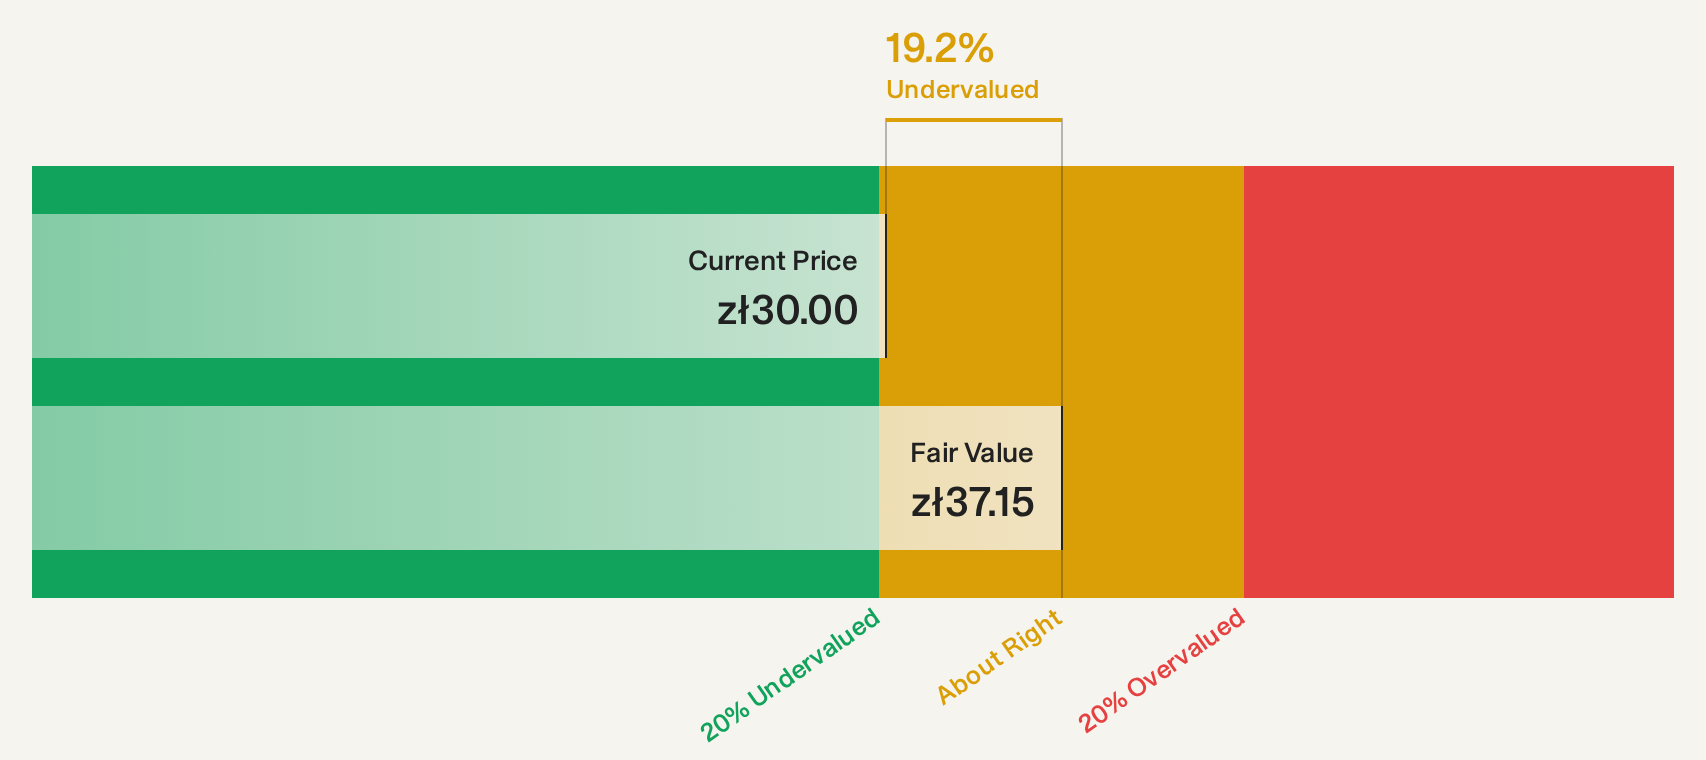
Estimated Discount To Fair Value: 20.6%
Auto Partner is trading at 20.6% below its estimated fair value, with a notable undervaluation against future cash flow estimates of PLN 37.23 per share. Recent earnings results show strong performance, with second-quarter net income increasing to PLN 94.14 million from PLN 57.94 million a year ago. Despite forecasted revenue growth of only 10.2% annually, slower than significant levels, the company offers good relative value compared to peers and industry standards in Poland.
- Our expertly prepared growth report on Auto Partner implies its future financial outlook may be stronger than recent results.
- Click here and access our complete balance sheet health report to understand the dynamics of Auto Partner.
Develia (WSE:DVL)
Overview: Develia S.A., with a market cap of PLN4.20 billion, operates in Poland's real estate development sector through its subsidiaries.
Operations: Develia generates revenue from its operations in the real estate development sector within Poland.
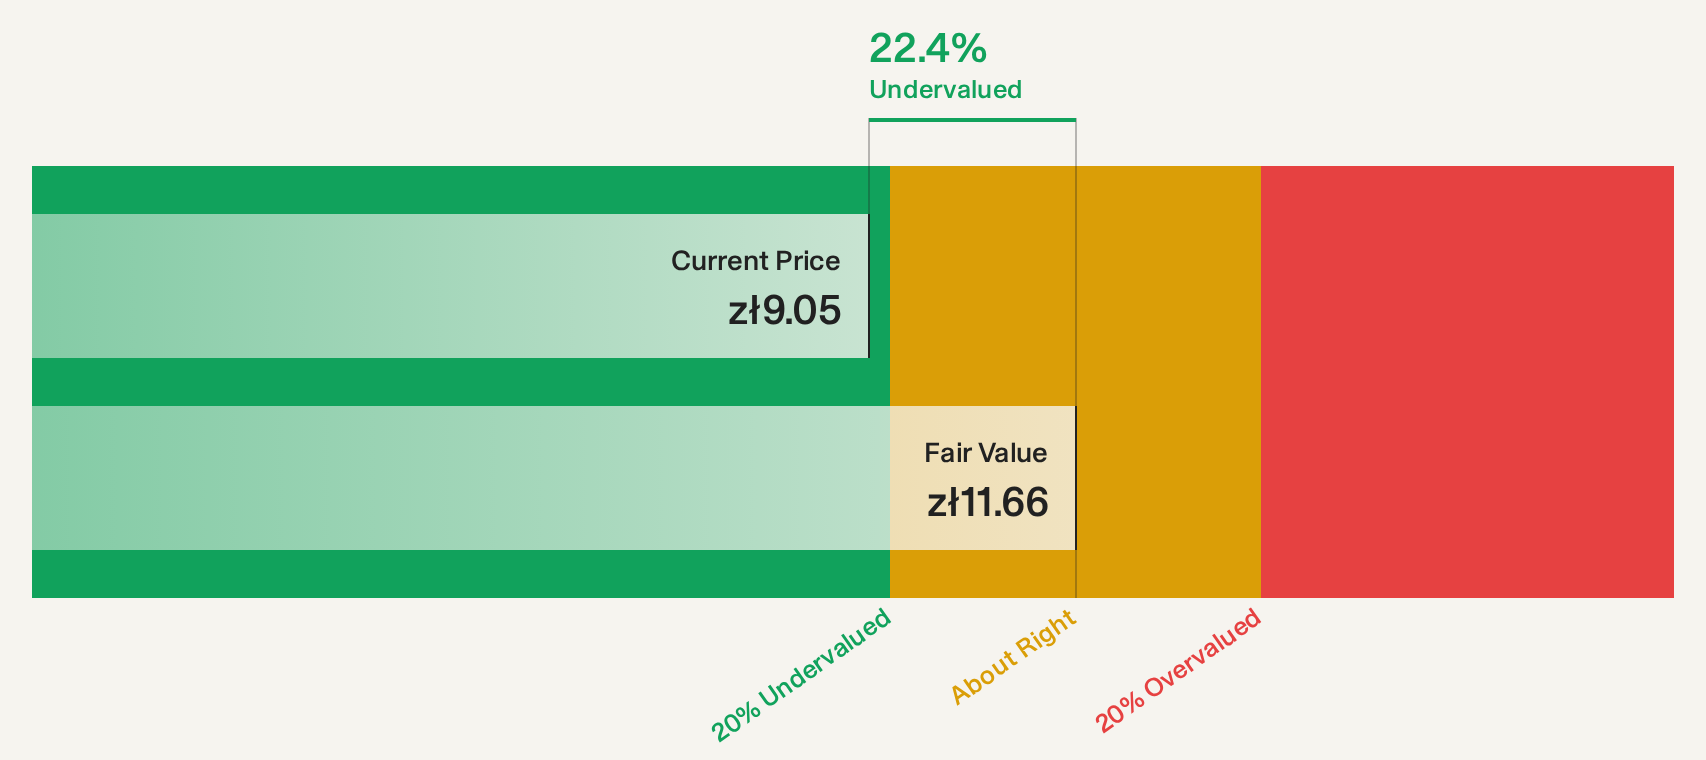
Estimated Discount To Fair Value: 23.1%
Develia is trading at 23.1% below its estimated fair value, with a significant undervaluation against future cash flow estimates of PLN 11.64 per share. Recent earnings results show robust growth, with second-quarter net income rising to PLN 141.97 million from PLN 108.44 million a year ago. Despite forecasts of declining earnings over the next three years and slower revenue growth compared to the Polish market, Develia remains competitively valued within its industry.
- Our earnings growth report unveils the potential for significant increases in Develia's future results.
- Click here to discover the nuances of Develia with our detailed financial health report.
Taking Advantage
- Delve into our full catalog of 23 Undervalued European Stocks Based On Cash Flows here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com