
How Investors May Respond To Belden (BDC) India Switch Manufacturing Move
- Belden announced that select RUCKUS Networks ICX Ethernet switches will now be manufactured at its Pune, India facility, linking RUCKUS hardware directly into Belden’s existing production and supply chain footprint.
- This shift pulls RUCKUS hardware into Belden’s India ecosystem across R&D, customer success and production, which could influence cost structure, lead times and local market access for networking products.
- We will now look at how Belden's India-based RUCKUS manufacturing integration could affect the broader investment narrative around execution and margins.
Belden Investment Narrative Recap
To own Belden, you need to believe the shift toward higher value networking and connectivity solutions can outweigh pressure in more commoditized cabling and hardware. The key near term swing factor is execution on that solutions mix while managing input costs like copper and the required ongoing OpEx. The Pune RUCKUS move supports this story but on its own looks incremental, not transformational.
The biggest operational risk still sits in integration and cost control. Belden carries a high level of debt and is investing to grow software enabled and Smart Infrastructure revenue, so any slowdown in orders or delayed digital projects could hit margins. The India manufacturing step modestly helps the execution case if it improves efficiency and supply resilience.
The RUCKUS manufacturing integration in India lines up most clearly with Belden’s push to win multi year work in data centers, broadband and industrial automation, where local supply and tighter lead times can be a practical advantage. Management is trying to use existing plants and logistics instead of building parallel footprints, which can matter for returns on capital.
For you as a shareholder, the interesting angle is how this ties into the goal of growing higher margin, solutions oriented business while keeping earnings quality intact. If Belden can keep leveraging its global network in similar ways, that supports the execution of its connectivity and automation awards and may help reduce some M&A and integration risk that analysts already flag in the story.
What The Current Belden Forecasts Assume
Belden's current analyst narrative points to forecast revenue of US$3.3b and consensus earnings of US$370.1m by 2029. That projection rests on annual revenue growth of 5.9% and an earnings rise of about US$133.5m from current earnings of US$236.6m.
Uncover why Belden's fair value indicates a 37% potential upside to its current price that could narrow quickly.
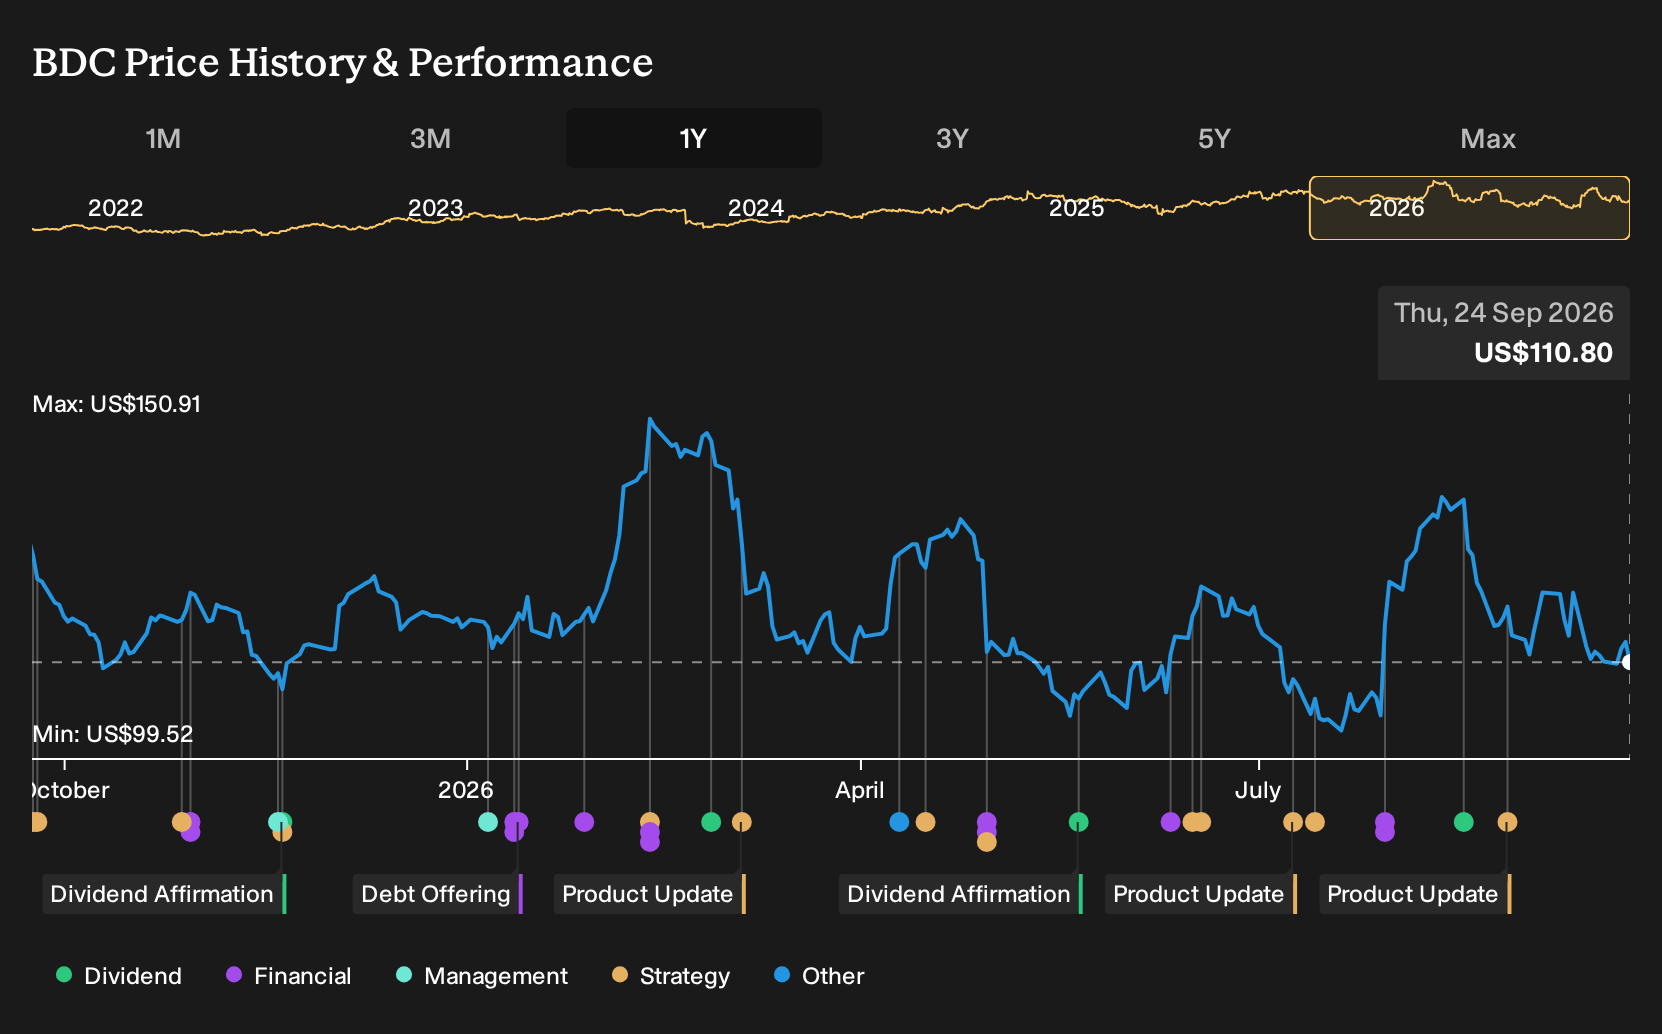
Exploring Other Perspectives
Community views on Belden already span a wide fair value band, from US$152 up to about US$346, across 2 separate estimates from the Simply Wall St Community. That spread sits beside real execution questions around input costs, integration work and macro driven order risk. Opinions are likely to diverge, and readers may wish to explore several alternative viewpoints.
Explore another Belden fair value estimate, including one that suggests it could be worth just $152.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Belden research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Belden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Belden's overall financial health at a glance.
Looking For More Investment Ideas Beyond Belden?
If the Belden story has you thinking about where else networking, infrastructure and balance sheet quality could matter, it can help to broaden the watchlist with other stocks that fit clear, fundamental themes. The Simply Wall St Screener lets you filter by financial strength, income potential and valuation so you are not just following headlines but building a list that matches your own risk and return preferences.
- For investors who care most about quality at a reasonable entry point, scan a curated set of companies that screen as attractively priced and financially robust through the 30 high quality undervalued stocks.
- If a resilient profile matters more than rapid expansion, filter for businesses with steadier fundamentals and more measured risk scores using the 30 resilient stocks with low risk scores.
- Readers who prefer to hunt for potential under-the-radar opportunities can build a watchlist from a focused group of less followed yet fundamentally strong stocks via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com