
How Investors Are Reacting To Beach Energy Stock After Index Removal
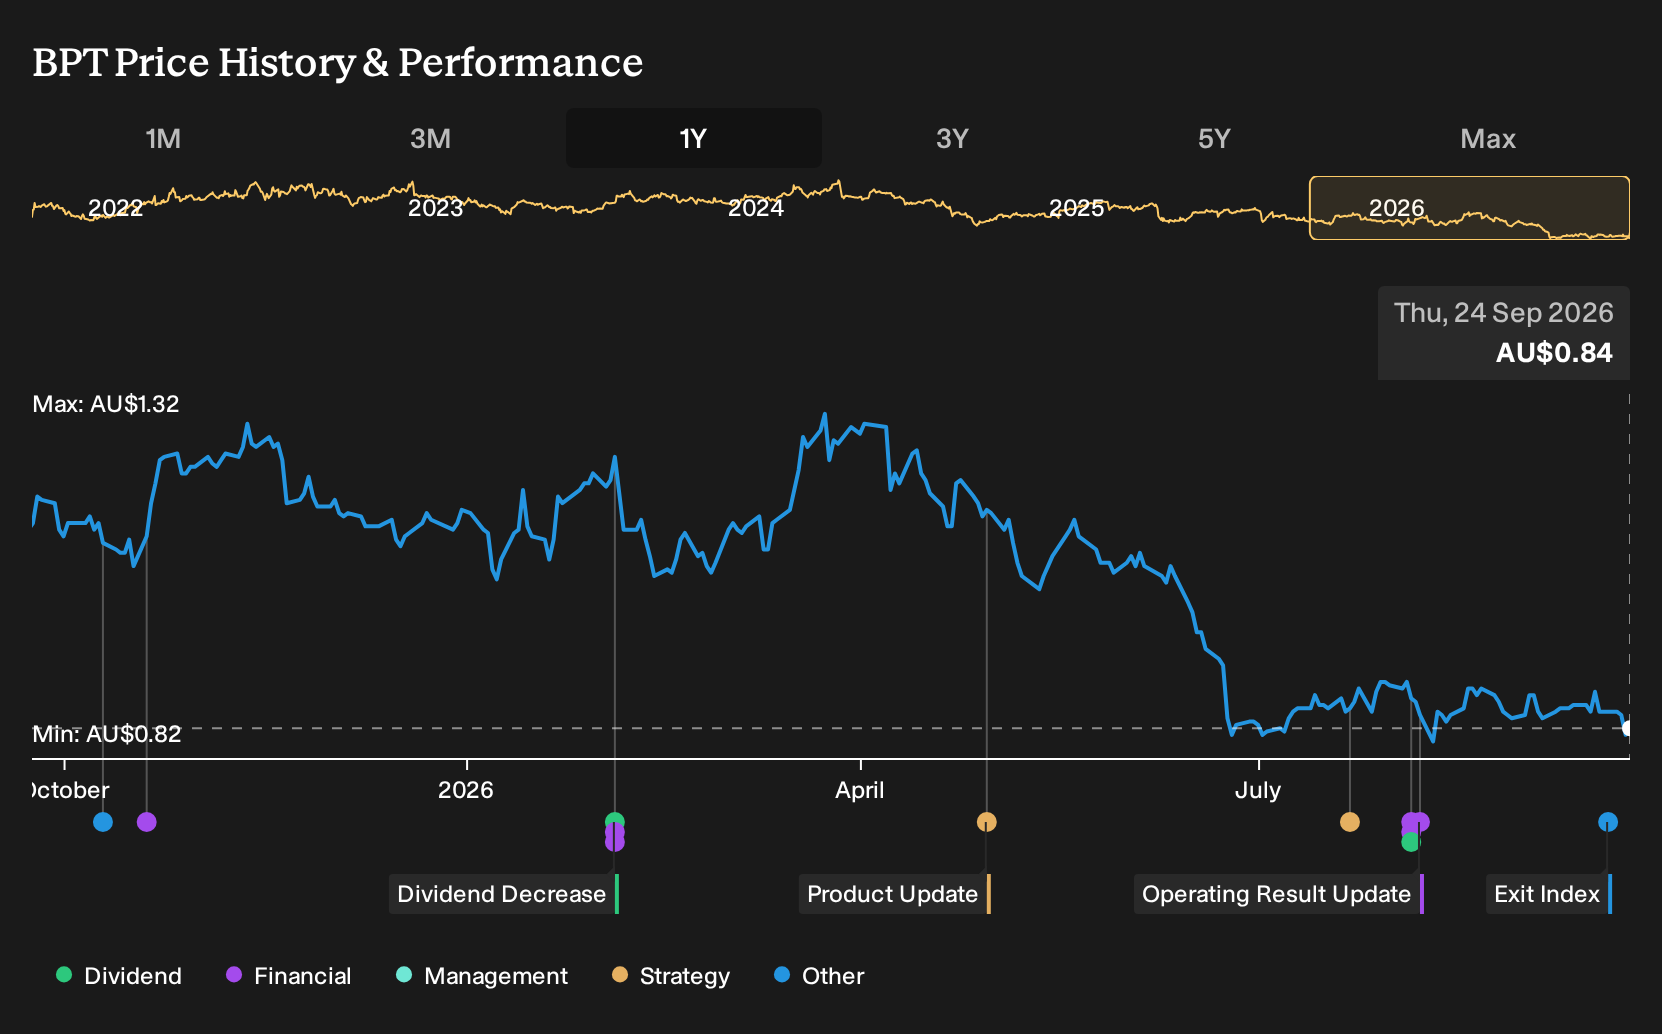
- Beach Energy Limited was removed from the FTSE All-World Index in September 2026, a change that affects its inclusion in global equity benchmarks and may alter how some institutional and passive investors gain exposure to the stock.
- This index exit narrows Beach Energy's automatic funding channel from index-tracking portfolios. It can sharpen the market's focus on project delivery, reserve life and cost discipline as the main drivers of future capital access and liquidity.
- We will now explore how Beach Energy's investment narrative, including LNG growth ambitions, may be reshaped by its recent removal from the FTSE All-World Index.
Scan beyond Beach Energy and see how other under-the-radar opportunities stack up in our hand picked 16 high quality undiscovered gems as index reshuffles push some stocks off the main stage.
Beach Energy Investment Narrative Recap
For Beach Energy, the big picture is simple. You need to believe the gas portfolio can offset a reserve life of just over seven years through successful drilling or sensible deals, while keeping project execution tight. The FTSE All World exit mostly affects index flows rather than rigs, wells or contracts, so the day to day operating story is intact.
The key near term swing factor is delivery on projects like Waitsia and domestic gas contracts without cost blowouts or delays that eat into margins and cash generation. The biggest risk sits in further reserve downgrades or value destructive M&A if organic opportunities fail to materialise.
Recent commentary around the Waitsia Gas Project is the clearest reference point when thinking about this index change. Beach Energy is working to ramp up LNG exposure and higher value domestic volumes. That is where operational execution can offset some loss of visibility with passive global funds and keep capital providers focused on project quality.
On the flip side, the same Waitsia and broader portfolio plans amplify risk if timelines slip or reservoirs underperform. Any stumble here would compound existing concerns about reserve life, future acquisitions and exposure to rising ESG costs. For investors watching catalysts, the operational scorecard on these projects matters far more than index membership.
Beach Energy Consensus Expectations After Index Exit
Beach Energy's current analyst narrative points to A$2.0b in revenue and A$454.2m in earnings by 2029, built on an assumed 1.8% yearly decline in revenue and a very large uplift in profitability from a loss of A$115.9m today.
Uncover why Beach Energy's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor after Beach Energy’s index exit is long term demand risk. The most cautious analysts were already assuming revenue drifts to about A$1.5b and earnings fall toward A$229.5m by 2029. That is far below consensus and could shift again once this index change is fully reflected in models.
Explore 5 other Beach Energy fair value estimates, including one that suggests it could be worth just A$1.02!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Beach Energy research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Beach Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beach Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Beach Energy?
If the Beach Energy story has you thinking about portfolio balance, use this moment to widen the lens and compare it with other companies that fit different risk, income and quality profiles.
- For investors who want potential upside without paying rich valuations, check out a hand picked set of companies screened as 6 high quality undervalued stocks that might warrant a closer look.
- If resilience and capital preservation sit high on your priority list, focus on businesses filtered for sturdier financial footing in our 7 resilient stocks with low risk scores.
- For those aiming to build a steadier income stream, you can review stocks with higher yields through the curated 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com