
SFL (SFL) Extends Hapag Lloyd Charters As Valuation Looks About Right
SFL (SFL) extended its relationship with Hapag-Lloyd by signing seven-year charters for six 15,400 TEU container ships, adding about US$750 million to its fixed-rate backlog through 2035-2036.
Recent trading tells a story of strong momentum for SFL, with a 1-day share price return of 2.04% and a 90-day share price return of 23.27%. The 1-year total shareholder return of 83.60% and 5-year total shareholder return of 145.81% point to gains that extend well beyond this latest charter extension news.
Spot other shipping plays with similar contract visibility by scanning our handpicked list of solid balance sheet and fundamentals (24 results).SFL now carries a longer, richer charter book and a much higher share price. The question is whether the recent rerating already reflects that or if the valuation still leaves meaningful upside on the table.
Most Popular Narrative: 1% Undervalued
The most followed narrative sees SFL trading just below its assessed fair value of $13.17, with the last close at $12.98 and only a small implied discount. That puts the spotlight squarely on whether contracted cash flows and fleet renewal can justify even modest optimism from here.
SFL's diversified fleet structure with significant exposure to container vessels and strong, long-term charters to investment-grade counterparties provides stable recurring revenue streams, high fleet utilization (98%+), and resilience against market volatility, underpinning predictable earnings and dividend coverage.
See why 15 investors see SFL as 1% undervalued.
Result: Fair Value of $13.17 (ABOUT RIGHT)
Still, SFL’s heavy exposure to container shipping and sizeable US$850 million newbuild commitments could pressure cash flows if charter demand or financing conditions weaken.
Find out about the key risks to this SFL narrative.
Another View: SFL Through The P/E Lens
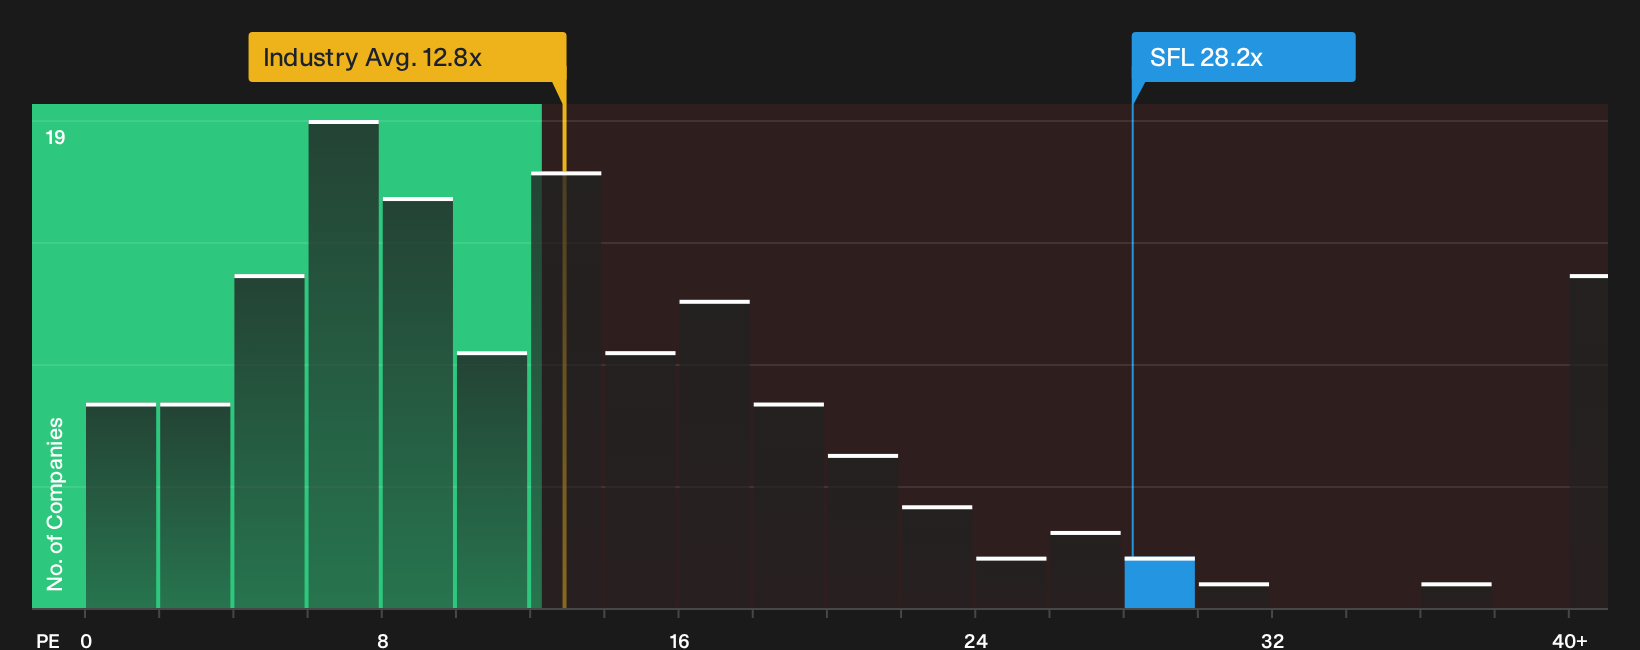
On the flip side of that fair value story, SFL trades on a P/E of 28.2x. That is well above both the US Oil and Gas industry at 12.6x and peers at 11x, and also ahead of its own fair ratio at 24.4x. The gap points to valuation risk if sentiment cools.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around SFL feels familiar, take it as a prompt to act quickly and review the numbers yourself. Weigh the potential advantages against the concerns by reviewing the 2 key rewards and 2 important warning signs.
Looking for more SFL-sized investment ideas?
Do not park all your attention on SFL and call it a day. Use the Simply Wall Street Screener to uncover fresh opportunities before others catch on.
- Target stability first, then growth by scanning companies with healthier finances on the 30 resilient stocks with low risk scores built around resilient balance sheets and lower risk scores.
- Hunt for mispriced potential by checking the 16 high quality undiscovered gems that combine strong fundamentals with limited current market attention.
- Build income-focused exposure by reviewing the 7 dividend fortresses that offer higher yields with an emphasis on consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com