
A. O. Smith (AOS) Pulls Back As Its Water Heater Narrative Faces A Valuation Test
A. O. Smith (AOS) drew investor attention after a recent share price pullback, with the stock down about 7% over the past month and roughly 17% over the past year.
That recent pullback sits within a wider slide, with A. O. Smith’s year to date share price return down 15.5% and its 1 year total shareholder return declining 17.4%, which points to fading momentum even as investors reassess both growth prospects and risk.
Compare A. O. Smith’s recent pullback with other quality industrial names by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that may be weathering similar pressures differently.
Bulls see A. O. Smith’s pullback as a reset on a profitable, globally diversified water heater business. Bears see a value trap forming as momentum cools. Which story fits the current valuation workup?
Most Popular Narrative: 4.9% Overvalued
A. O. Smith last closed at $57.70, while the most followed narrative on the stock pegs fair value around $55. That gap is small in percentage terms, but it still raises the question of whether investors are paying a bit extra for a high quality water heater franchise with a few unresolved issues.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control more than 90% of the market, the product is a non-discretionary emergency replacement in more than 80% of cases, and prices have risen above inflation for twelve consecutive years. The company generates around $550M in free cash flow annually against a market capitalisation of roughly $8B, has paid a growing dividend for 34 consecutive years, and has reduced its share count nearly 10% over five years.
See why 2 investors see A. O. Smith as 5% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, two issues could unsettle that fair value story for A. O. Smith if the China review drags on or if the 2029 heat pump mandate reshapes its distribution edge.
Find out about the key risks to this A. O. Smith narrative.
Another View On A. O. Smith’s Value
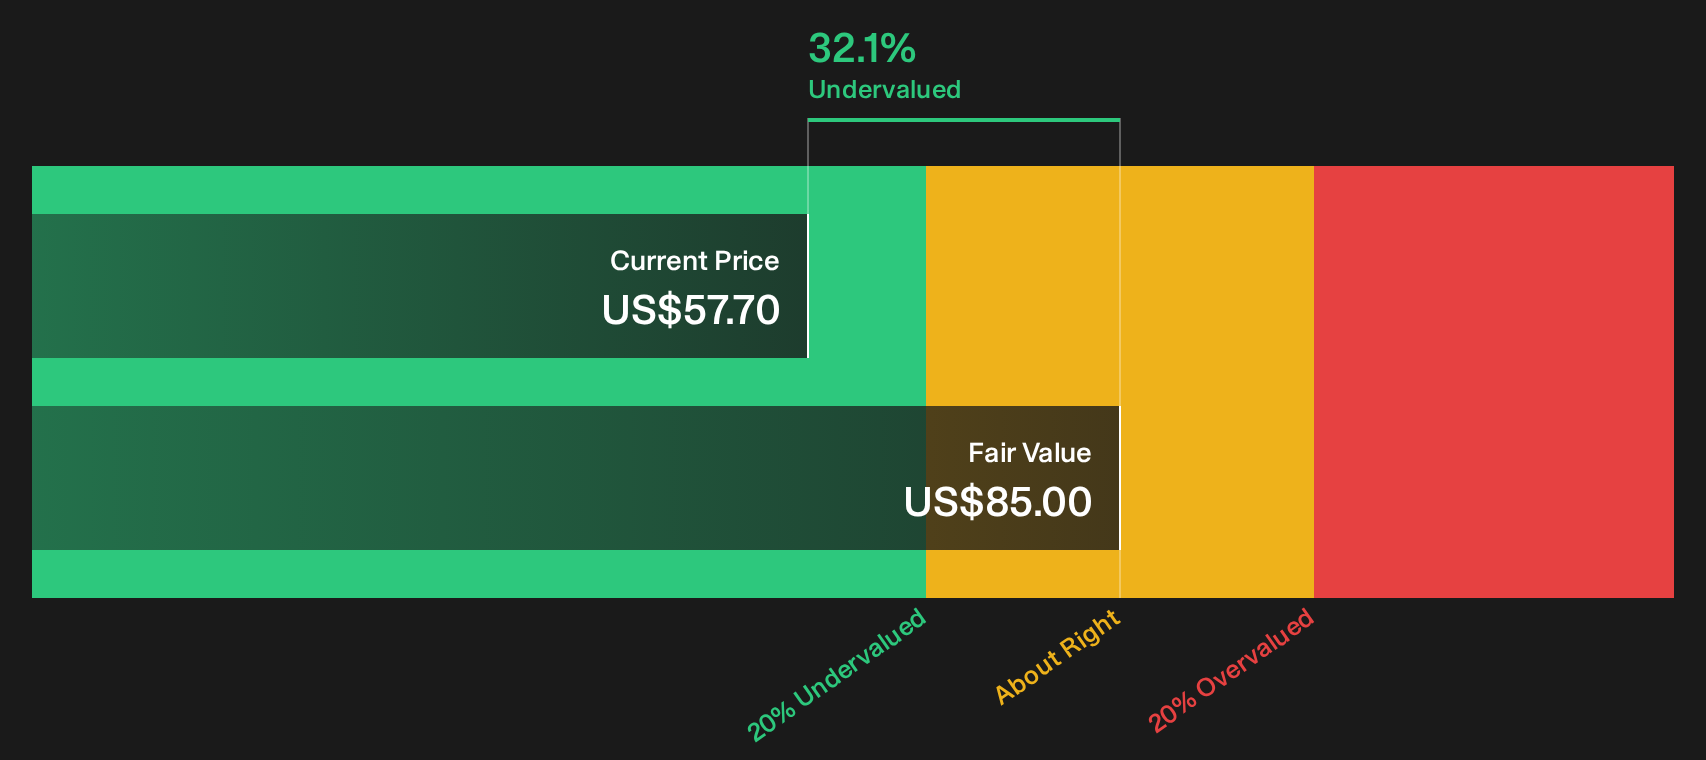
While the leading narrative sees A. O. Smith as about 4.9% overvalued at $57.70 versus a $55 fair value, the SWS DCF model points the other way. On that approach, the shares are trading roughly 32.1% below an $85 future cash flow estimate, which implies a very different risk reward balance.
When one framework says slightly rich and a full cash flow model points to a discount, which signal do you treat as the anchor for your own work?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around A. O. Smith is split, which is exactly why fresh eyes on the raw numbers matter. Act quickly, review both the risks and the upside potential, and then weigh those views against the 5 key rewards.
Looking for more ideas beyond A. O. Smith?
If A. O. Smith sharpened your focus on price versus quality, do not stop here. Broaden your watchlist with targeted ideas built from the same disciplined framework.
- Target income resilience by scanning companies built to defend their payouts through thick and thin with the 7 dividend fortresses.
- Hunt for quality at a discount by checking companies that pair robust fundamentals with reasonable pricing using the 30 high quality undervalued stocks.
- Spot potential future leaders early by reviewing financially sound under-the-radar opportunities through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com