
Materion (MTRN) Following Semiconductor Demand Hopes Still Looks Undervalued
Materion (MTRN) has drawn fresh attention after recent share price moves, with the stock closing at $256.14 and posting a mixed return pattern over the past month and the past 3 months.
The recent 10.17% 1 month share price return, alongside a 7 day move of 2.26%, comes after a softer period where the 3 month share price return declined 10.76%. As a result, momentum in Materion now looks to be rebuilding following a very strong year to date share price return of 99.28% and a 1 year total shareholder return of 117.81%.
Spot other materials players showing similar momentum and long-term total return profiles by scanning our hand picked list of solid balance sheet and fundamentals (24 results).Materion now trades at a clear markdown to both analyst targets and estimated fair value, even after this sharp run. Is that a genuine opportunity, or is the market signalling justified caution about what investors are paying for here?
Most Popular Narrative: 15% Undervalued
On the most followed narrative, Materion screens as undervalued, with a fair value estimate of $301.19 against the last close of $256.14, even after a strong run in the share price.
Accelerating demand in the semiconductor sector, driven by increasing wafer starts, growth in data storage and communication devices, and the recent acquisition of Konasol (expanding footprint in Asia), positions Materion to capture a higher share of a rapidly expanding global market and supports sustained top line revenue growth over the next several years as new capacity ramps by 2026.
See why 11 investors see Materion as 15% undervalued.
Result: Fair Value of $301.19 (UNDERVALUED)
Still, Materion’s reliance on specialty metals and its concentrated exposure to semiconductor and defense customers means that any supply disruption or demand slowdown could quickly challenge this upbeat narrative.
Find out about the key risks to this Materion narrative.
Another View: Materion Looks Expensive On Earnings
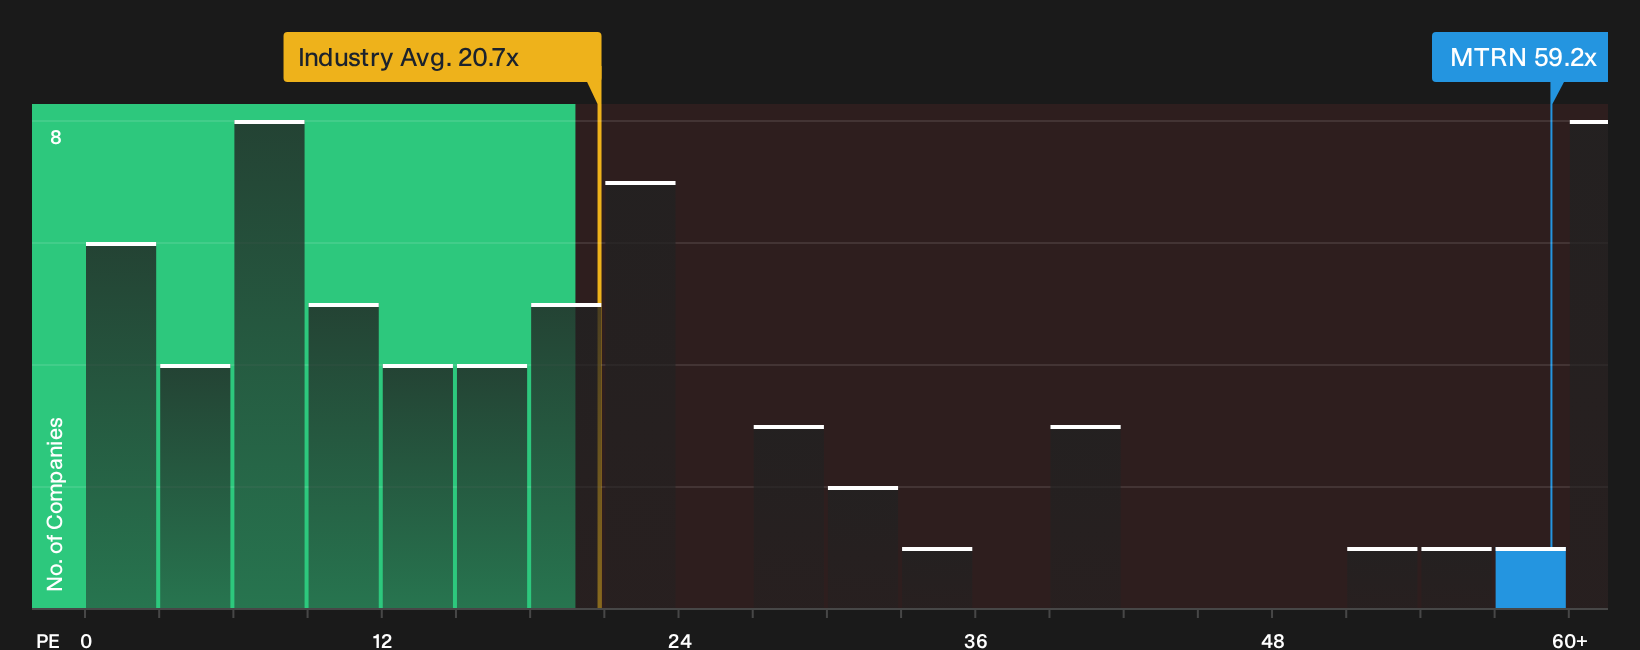
The first narrative leans on cash flow and analyst assumptions to argue Materion is undervalued. A very different picture appears when you look at simple earnings ratios. The stock trades on a P/E of 59.2x against a fair ratio of 33.6x, which suggests investors are already paying a heavy premium for each dollar of profit.
That multiple is also far richer than both peer levels at 28.5x and the broader US Metals and Mining sector on 20.9x. If sentiment cools or expectations reset, the P/E could drift toward that fair ratio, so the key question for holders is whether Materion can sustain the kind of earnings profile that keeps this premium in place.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Materion’s value and risk profile can pull opinions in opposite directions, so weigh both sides, act promptly if timing matters to you, and base your view on the data by checking the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Materion?
If Materion has sharpened your focus, you could broaden your opportunity set with a few curated stock ideas that align with different goals and risk levels.
- Explore a focused group of higher risk, higher reward opportunities through the 8 elite penny stocks with strong financials.
- Review companies that combine certain fundamentals with specific valuations using the 30 high quality undervalued stocks.
- Consider businesses that may offer relative stability through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com