
Illumina (ILMN) Stock May Be Near Fair Value After Raised Guidance
Illumina has seen a sharp reset in market expectations over the past year, which puts a spotlight on a simple question for investors. Does the current share price reflect what the company’s cash flows can reasonably support, or has sentiment moved ahead of the underlying economics?
- Illumina has returned 198.7% over the past 12 months, so a lot of future cash generation now needs to be justified by the business rather than share price momentum.
- Recent updates around stronger demand for sequencing platforms and clinical consumables can support higher expectations for future revenue and, by extension, potential cash flow capacity.
- Prefer to judge Illumina on earnings? See why Illumina's 50.2x P/E tells a different valuation story.
The stock’s next move may depend on whether a Discounted Cash Flow (DCF) view of Illumina’s cash streams supports the valuation implied by today’s price.
If you want more ideas that start from the same question of whether current prices line up with future cash potential, a focused screener of 30 high quality undervalued stocks.
Is Illumina Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at what Illumina can return to shareholders based on its projected cash generation. Latest twelve month free cash flow sits at about $942.9 million, and the model assumes that this figure increases over time rather than contracts, with free cash flow expected to be above $1 billion within a few years and continue growing through the next decade.
Those rising cash projections leave Illumina trading at a price of $273.90 that the DCF output suggests is broadly in line with what its forecast cash flows can support. Because management recently reported 9.5% year on year revenue growth and stronger demand across sequencing platforms and clinical consumables in the Q2 2026 update, the market now appears to be pricing in that healthier cash profile rather than a stressed one. That balance between improving fundamentals and an already aligned valuation is what the intrinsic value model is flagging for this stock today. Find out what Illumina could be worth using our Discounted Cash Flow (DCF) estimate.
The Illumina Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Illumina's DCF puzzle leaves off by outlining which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price, and they are available on the Community page. Each narrative treats Illumina's estimated worth as a hypothesis about how the business develops over time, so you can see how that view holds up as new information becomes available.
One of the top community narratives on Illumina: 105% overvalued
"The numbers imply that Illumina's share price already reflects optimistic assumptions on revenue growth, consumables pull through, and margin expansion…"
Discover why this Narrative puts Illumina at 105% overvalued.
Illumina’s price is only one signal, insider behavior is another
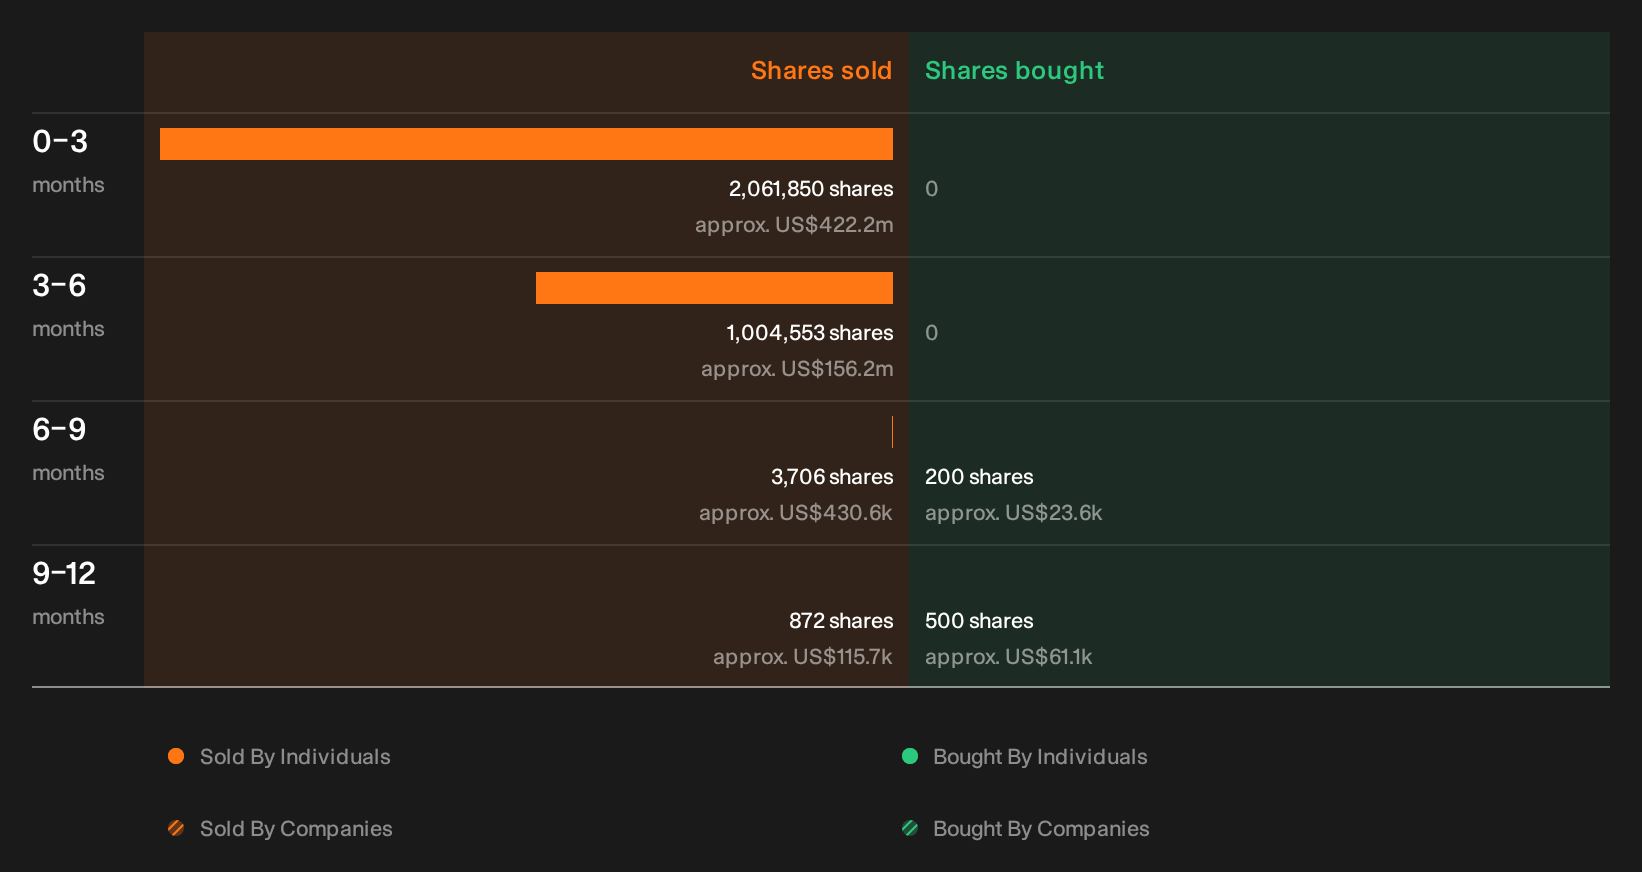
DCF outputs and market moves tell part of the Illumina story, but recent insider share sales flagged by our checks raise a separate question about incentives and timing that deserves a closer look. See the recent insider selling flagged for Illumina.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com