
Moderna (MRNA) Stock Looks Overvalued Against Its Current Sales Base
Moderna has delivered a very large 1 year gain, which naturally raises a question for you as a shareholder or potential buyer. Is the current share price mainly a story about momentum, or does it line up with what the company is generating through its sales base today?
- With the stock up about 7x over the past year, any new position now leans heavily on whether the underlying sales can support this kind of re-rating.
- Recent headlines around Moderna's mRNA products, from an approved flu vaccine to ongoing patent disputes, may influence how investors think about future revenue durability and pricing power.
- There is a second opinion on Moderna worth weighing. See what analysts think Moderna's shares could be worth.
The issue now is whether Moderna's current market value is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you want to stress test the same sales based valuation question that Moderna now faces across a wider set of biotech and pharma stocks, take a look at 38 healthcare AI stocks.
Does Moderna Look Pricey on Sales?
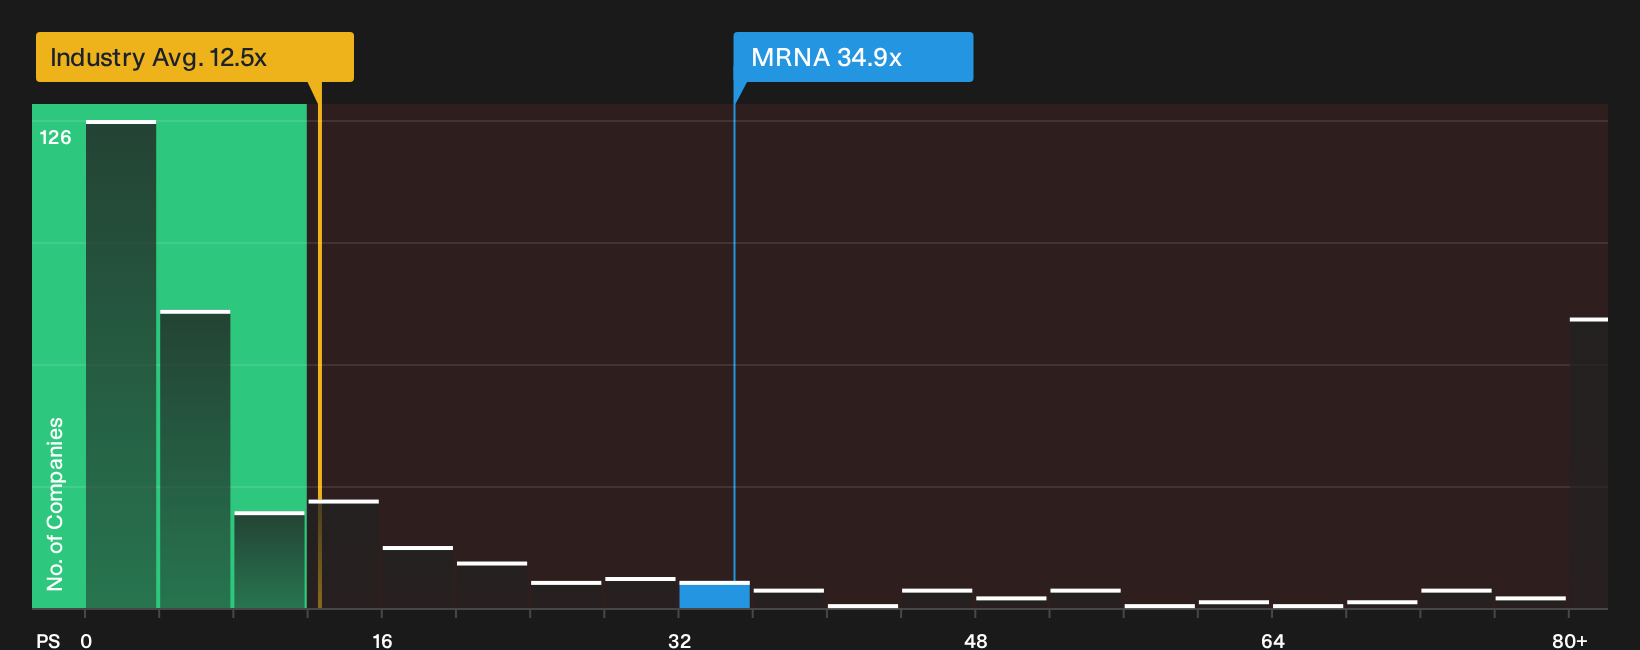
P/S is a cleaner lens for Moderna right now because earnings remain negative while sales give you a clearer anchor for what the market is paying for its mRNA platform. On this measure, the stock trades at about 34.9x trailing revenue, compared with roughly 12.5x for the wider biotech industry and about 6.8x for its peer group. That is a very steep premium for each dollar of current sales.
The Fair Ratio, which adjusts the P/S multiple for factors such as growth profile, margins, scale and risk, flags Moderna as overvalued and it points to an especially wide gap rather than a small overshoot. The model is heavily penalising the present loss making profile and the quality of recent revenue, so the high P/S reads more as a warning signal than a precise target. Despite the recent approval and rollout of the mFlusiva mRNA flu vaccine, the market is still pricing Moderna stock at a level that assumes very strong future conversion of its pipeline into durable sales. Explore the numbers behind Moderna's P/S valuation.
The Moderna Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Moderna pick up where this valuation question leaves off. They spell out which combinations of future growth, margins and earnings would need to hold for Moderna's share price to look meaningfully higher or lower than it does today. Instead of a single P/S or Fair Ratio output, each narrative lays out its own underlying assumptions so you can compare them with actual results on the Community page as they arrive.
One of the top community narratives on Moderna: 63% overvalued
"Bullish analysts point to the positive Phase 3 melanoma readout as a major validation of Moderna's oncology efforts, with several describing it as a watershed moment…"
Discover why this Narrative puts Moderna at 63% overvalued.
One more Moderna check that belongs beside the price tag
Before you decide how this valuation sits with you, it can help to see where professional analysts expect Moderna to be a few years from now and how that path lines up with today’s pricing. Explore where analysts expect Moderna to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com