
BioNTech (NasdaqGS:BNTX) Stock May Look Fully Valued On Fresh Lung Cancer Trial Data
BioNTech has seen its share price fall 63.3% over the past 5 years, yet fresh clinical data and shifting revenue expectations keep raising the same issue for investors: whether the current valuation is still in line with what the business is generating from its sales. With a stock that has moved this much over a multi year stretch, the link between the quoted price and the company’s actual revenue base deserves a closer look.
- The 63.3% decline over 5 years has materially reset expectations. This puts extra focus on how much sales power is now being reflected in BioNTech's share price.
- The recent Phase 3 lung cancer trial result for gotistobart, which nearly doubled median overall survival versus chemotherapy, may support higher long term revenue expectations if the treatment progresses successfully through further evaluation and potential commercialization.
- Your read on BioNTech is one view; the desks covering it have another. See what analysts think BioNTech's shares could be worth.
The stock's next move may depend on whether BioNTech's current market value can be squared with what investors are paying for its existing and anticipated sales base.
If you want to balance BioNTech’s story with other ideas tied to solid financial footing, a focused stock screen built around solid balance sheet and fundamentals stocks screener (24 results) can be a useful next step.
Has BioNTech Run Too Far on Sales?
P/S fits BioNTech reasonably well because revenue remains the clearest anchor while earnings and cash flow move around with R&D and trial spending.
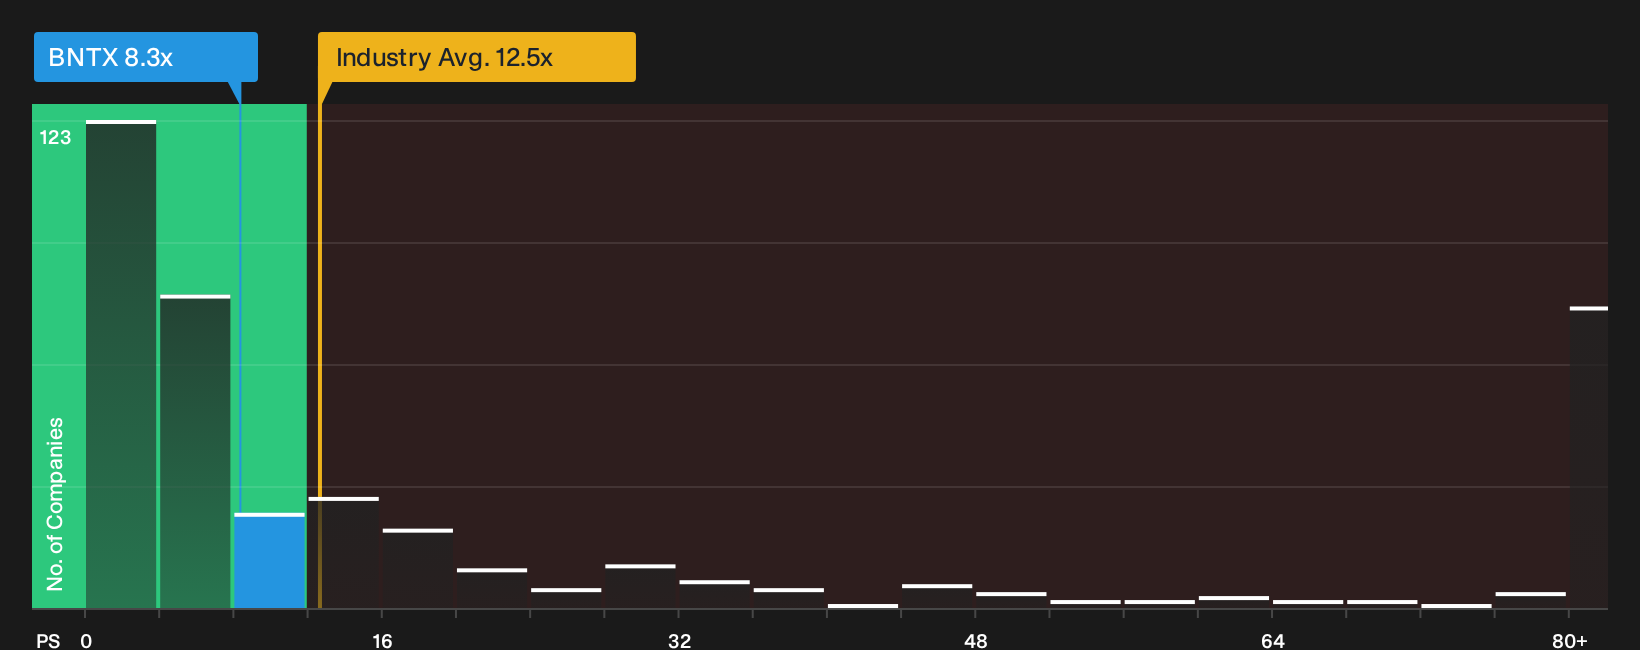
On this lens, BioNTech trades at about 8.3x P/S. The broader Biotechs group sits closer to 12.5x, while the direct peer set clusters around 12.3x, so the stock changes hands at a lower revenue tag than many comparables. Based on the tailored fair multiple, which blends the group’s growth profile, profitability record, size and risk, the current ratio screens as overvalued relative to what that framework would suggest. Because the recent Phase 3 lung cancer data has already lifted sentiment, the valuation still asks investors to pay a premium to that internally modelled range despite the lower headline P/S versus the sector.
That gap means anyone considering BioNTech needs to decide whether the drug pipeline and oncology potential justify paying more per unit of sales than the fair multiple implies, or whether it makes sense to wait for the share price or revenue base to move closer to that benchmark. Explore the numbers behind BioNTech's P/S valuation.
The BioNTech Narrative: What Would Justify Today's Price?
BioNTech’s valuation puzzle only really comes into focus once you spell out the future behind the numbers. That is what Simply Wall St Narratives aim to do on the Community page by turning that P/S discussion into explicit assumptions about future growth, margins and earnings that would have to hold for the shares to be worth materially more or less than today’s price. Where a ratio or model offers a single figure, these scenarios lay out the economic path that figure relies on so you can watch how reality lines up over time.
Community views on BioNTech are split between those who see the oncology pivot as underappreciated and those who think vaccine headwinds and execution risks matter more.
Bull case: 16% undervalued
"Robust pipeline expansion in oncology with multiple late stage clinical trials for BNT327 and mRNA cancer immunotherapies across high prevalence cancers positions BioNTech to launch multiple new products…"
Discover why this Narrative puts BioNTech at 16% undervalued.
Bear case: 18% overvalued
"Falling COVID-19 vaccine demand in core markets, including ongoing declines in U.S. vaccination rates and increased vaccine hesitancy globally, is expected to materially reduce long term revenue from BioNTech's main commercial franchise…"
Explore why this Narrative puts BioNTech at 18% overvalued.
The BioNTech valuation still leaves one crucial piece off the table
Everything so far has focused on what BioNTech looks like today. Yet professional forecasts for where this business could be a few years out offer a separate reality check that is hard to ignore. Explore where analysts expect BioNTech to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com