
Samsung Electronics (KOSE:A005930) Stock May Still Offer Value After A 339% Run
Samsung Electronics has delivered huge gains in recent years, so the live question for anyone looking at the stock today is whether those earnings genuinely support the current share price.
- Over the past 3 years, Samsung Electronics has returned about 339.1%, which puts a lot of weight on whether its earnings can carry that kind of move.
- The group’s scale in semiconductors and consumer electronics can shape how efficiently it turns revenue into profit, which feeds directly into how much investors may be willing to pay for each unit of earnings.
- There is a second opinion on Samsung Electronics worth weighing. See what analysts think Samsung Electronics's shares could be worth.
The issue now is whether Samsung Electronics’ current price is justified by its earnings when set against a Fair Ratio benchmark.
If you are weighing whether Samsung Electronics’ earnings justify this kind of run, it can help to compare that question across 179 high quality undervalued stocks.
Is Samsung Electronics Still Cheap on Earnings?
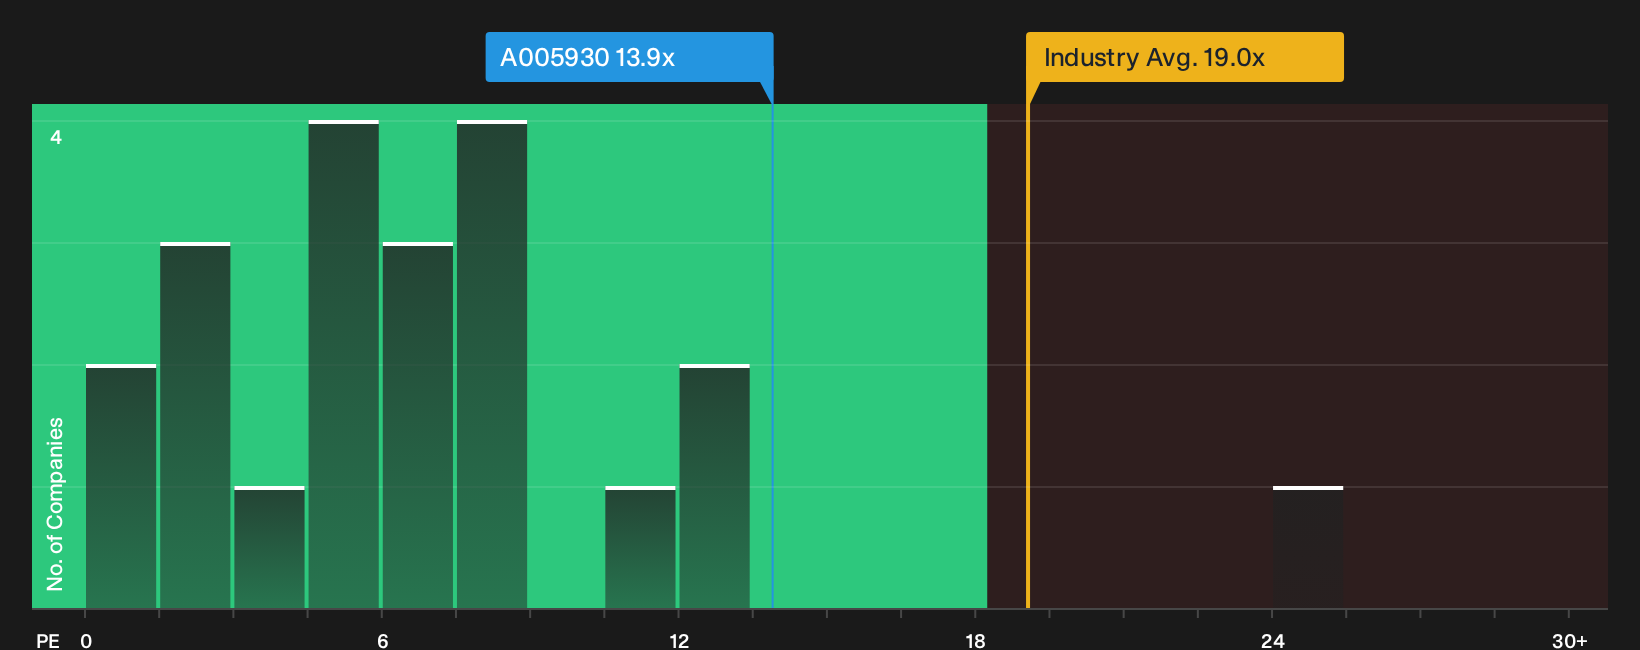
The P/E ratio fits Samsung Electronics well because earnings remain a central yardstick for how investors frame this kind of large, diversified tech group. On that metric, the stock trades on about 13.9x earnings, which is below the wider tech sector average of roughly 19.9x and far under the peer group level of about 62.6x. That gap indicates the market is pricing Samsung Electronics at a lower earnings multiple than many comparable tech stocks.
The Fair Ratio model, which looks at factors such as growth potential, profitability, size and risk to estimate a more tailored P/E yardstick, points to a higher level than the current 13.9x. That places the shares below the multiple implied by those fundamentals, so the market is not assigning as rich an earnings premium as that framework would suggest. For anyone assessing Samsung Electronics today, a key consideration is whether its future earnings profile and competitive position support that discount or leave it unchanged. Explore the numbers behind Samsung Electronics's P/E valuation.
The Samsung Electronics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E and Fair Ratio discussion leaves off by explaining which paths for Samsung Electronics' growth, margins and earnings would need to occur for the stock to appear meaningfully higher or lower than today's price. Each scenario links a fair value estimate to a specific combination of potential catalysts and risks, so you can track over time which version of Samsung Electronics' story seems closest to reality on the Community page.
The community is split on Samsung Electronics, with one camp seeing a discounted giant and the other arguing recent gains already price in a lot of good news.
Bull case: 43% undervalued
"Samsung's competitors like TSMC, SKHY, MU, and INTC are not capable of what Samsung can, these companies have gaps…"
Discover why this Narrative puts Samsung Electronics at 43% undervalued.
Bear case: 15% overvalued
"Since 1996 there have been six completed memory booms, all six died, each within roughly two years…"
Explore why this Narrative puts Samsung Electronics at 15% overvalued.
One more angle on Samsung Electronics that could shift how you see today's price
Valuation only shows what the market is paying today, while professional coverage sketches where this business might be a few years down the road and how that lines up with the current multiple. Explore where analysts expect Samsung Electronics to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com