
Learn Why The Bull Case For Amerigo Resources Stock Could Change Following Special Dividend പ്രഖ്യാപation
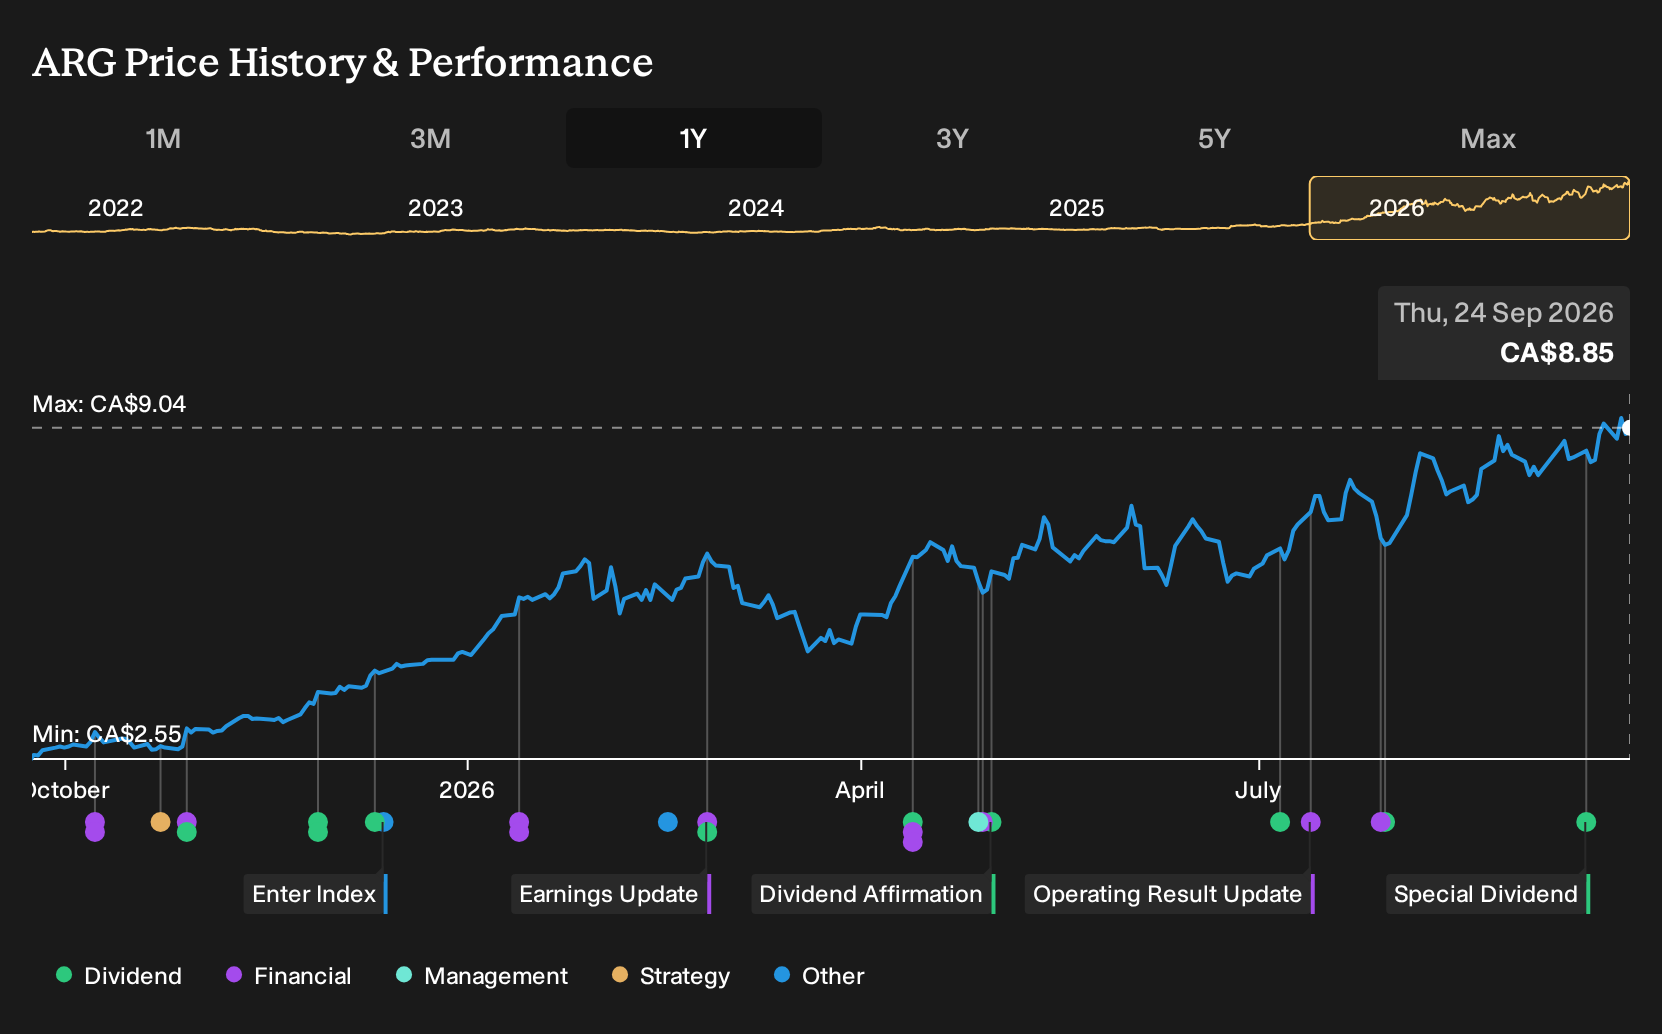
- Amerigo Resources declared a special performance cash dividend of C$0.21 per share, with the ex dividend date on 16 September 2026 and payment scheduled for 14 October 2026 to shareholders of record on 21 September 2026.
- This performance dividend indicates that Amerigo Resources is returning a specific pool of surplus cash to investors. This can influence how shareholders weigh capital allocation choices, including growth projects, balance sheet priorities, and potential future distributions.
- Attention will now turn to how Amerigo Resources' investment narrative is shaped by this performance dividend and what it may suggest about future capital returns.
What Is Amerigo Resources' Investment Narrative?
To own Amerigo Resources, you need to be comfortable with a focused copper tolling business in Chile that leans heavily on execution, contract stability and copper pricing rather than broad diversification. Operations are tied to producing copper and molybdenum concentrates from El Teniente, which keeps capital intensity more about maintaining and upgrading processing capacity than building new mines. Earnings growth of 259.1% over the past year and a 20.9% net margin show what strong throughput and pricing can do when things line up.
The performance dividend and upcoming ex dividend date signal that management sees enough surplus cash today to return CA$0.21 per share, while still running the plant and meeting obligations. That move interacts directly with two of the nearer term questions: how sustainable any payout is given an unstable dividend track record, and how a business with expected revenue decline of 16.4% per year balances distributions against funding needs, especially when 100% of liabilities come from higher risk sources of financing.
Even so, there is a less obvious pressure point in the Amerigo Resources story that only becomes clear when you look at ...
There's only one way to know the right time to buy, sell or hold Amerigo Resources. Head to Simply Wall St's company report for the latest analysis of Amerigo Resources's Fair Value.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently frame Amerigo Resources between about C$3.95 and C$10.02 per share, which is a wide gap for such a small sample. With those views set before the C$0.21 performance dividend news, you should expect opinions to shift and should explore multiple fresh takes before leaning on any single valuation anchor.
Explore another Amerigo Resources fair value estimate, including one that suggests potential upside of as much as 13% from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amerigo Resources research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amerigo Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amerigo Resources' overall financial health at a glance.
Looking For More Ideas Beyond Amerigo Resources?
If this Amerigo Resources performance dividend has you rethinking how you source income and value, it can help to widen the lens and scan a broader set of opportunities using the Simply Wall St screener.
- For investors who care most about dependable balance sheets and fundamental strength, start with the list of solid balance sheet and fundamentals (7 results) that passes rigorous financial health filters.
- If you want a head start on potential mispricings, focus on businesses that combine quality with pricing support by checking out the 5 high quality undervalued stocks.
- Those hunting for overlooked stories with room to gain traction can review the 9 high quality undiscovered gems that meet strict quality and fundamentals criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com