
Is Nu Holdings (NU) A Bargain Following Nu Global Expansion And A New Legal Chief?
New legal chief joins as Nu Global expands reach
The latest move at Nu Holdings (NYSE:NU) is not about products or pricing. Nubank has hired Sarah Wilson as Chief Legal Officer, stepping into a key governance role as cross border ambitions widen.
Wilson joins at a moment when Nu Global is opening access to customers across more than 35 countries, with fee free transfers and interest bearing dollar and euro balances. Her background spans public listings, M&A and regulatory work across highly regulated sectors.
For investors, the appointment intersects with a business that reports revenue of US$8.4b and net income of US$3.6b, supported by a digital banking model and an efficient cost base. The question is how this legal leadership role fits into Nu Holdings' next phase of expansion.
Nu Holdings has seen its share price retreat 10.44% over the past month and 20.33% year to date to US$13.56, even though the 3 year total shareholder return of 86.01% still points to a very strong earlier run. Recent weakness signals cooling momentum as investors reassess how cross border expansion, including Nu Global and new leadership hires, reshapes both growth potential and risk.
Compare Nu Holdings' cross border push with other digital finance players by scanning our hand picked 21 cryptocurrency and blockchain stocks that could be riding similar payment and remittance trends.
Nu Holdings now trades at a clear discount to both analyst targets and some fair value estimates after that sharp pullback. Is the market prudently pricing in execution risk on Nu Global, or leaning too far into caution?
Most Popular Narrative: 40% Undervalued
Against the last close at $13.56, the most followed narrative around Nu Holdings points to a fair value of $22.74 based on a 13% discount rate. This frames the recent pullback as a pricing gap rather than a business reset.
The first is that Nu Holdings is currently trading at a historically low multiple relative to its growth profile. At $12.20 per share, the market is assigning it a 2026 forward P/E of just 13.7x, based on an estimated earnings per share of $0.89, for a company growing that same earnings figure at roughly 48% annually. The 36% decline from its January highs ($18.98) has been driven by higher credit loss provisions in the first quarter and macroeconomic deterioration in Brazil, not by any change in the quality of the business model. That potentially creates an attractive entry window.
See why 99 investors see Nu Holdings as 40% undervalued.
Result: Fair Value of $22.74 (UNDERVALUED)
Still, the Nu Holdings story could be knocked off course if Brazil’s credit cycle worsens and if U.S. expansion or Nu Global execution stumbles.
Find out about the key risks to this Nu Holdings narrative.
Another View on Nu Holdings Valuation
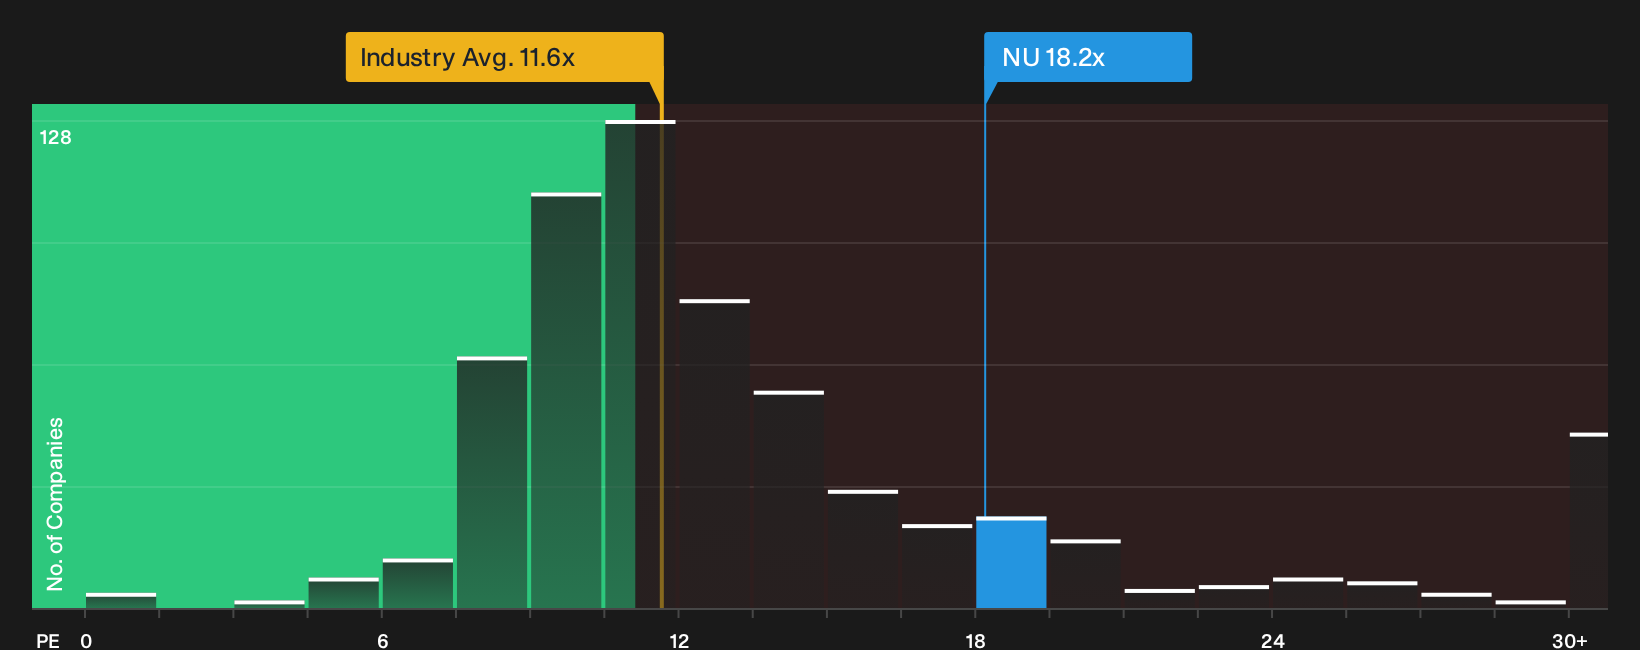
The first narrative around Nu Holdings leaned heavily on earnings power and a fair value of $22.74. Using simple P/E math tells a trickier story. NU trades on about 18.2x earnings versus 14.8x for peers and 11.6x for the broader US Banks group, even though a fair ratio suggests 19x.
That gap means the stock carries less of a blunt bargain tag on earnings alone and a bit more multiple risk if sentiment sours again. The fair ratio hints that the current P/E could still be reasonable if the business keeps executing, but it also raises a blunt question for investors: Is this discount about value, or just about growth expectations already priced in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Nu Holdings attracts both optimism and concern, and that mix is exactly why you should pressure test the numbers yourself, then weigh up the 4 key rewards and 2 important warning signs.
Looking for more Nu Holdings investment ideas?
If you stop with Nu Holdings, you only see one angle. Use the screeners below to quickly surface other opportunities that might fit your style.
- Target potential mispricings by scanning a curated pool of companies that combine quality and value through the 30 high quality undervalued stocks.
- Build a steadier income stream by hunting for reliable payers using the 8 dividend fortresses.
- Dial down portfolio stress by focusing on sturdier balance sheets and fundamentals in the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com