
Will Record Backlog Change Enerflex (TSX:EFX) Narrative
- Enerflex reported Q2 2026 results with a record engineered systems backlog of about US$1.5b and a book to bill ratio of 1.6, alongside lower revenue and net earnings compared with the prior year.
- The update highlighted firm demand for natural gas infrastructure and ongoing balance sheet repair, including credit facility extension and selective asset sales in Asia. Taken together, these developments may reshape how investors evaluate the mix of growth and risk in Enerflex's business.
- We will now look at how Enerflex's record engineered systems backlog could reshape the broader investment narrative around the business.
Scan how Enerflex’s natural gas backlog story compares with other infrastructure heavyweights by reviewing our hand picked 39 power grid technology and infrastructure stocks moving on similar long term capital projects.
Enerflex Investment Narrative Recap
To own Enerflex, you have to buy into a story where natural gas infrastructure and services remain in demand long enough for the current project pipeline and high margin service work to matter. The record US$1.5b engineered systems backlog supports that view, even though recent revenue and net earnings were lower and profit margins sit near 2.1%.
In the near term, execution on that backlog and stabilization of margins look like the main swing factors. The biggest risk is that margin pressure and the still fresh management bench turn a strong order book into weaker cash conversion. The recent update does not remove that concern, but it does not materially worsen it either.
The clearest operational takeaway from the recent update is the combination of a record engineered systems backlog and Enerflex’s emphasis on balance sheet repair. Management extended the credit facility and is simplifying its footprint through asset sales in parts of Asia, all while supporting a book to bill ratio of 1.6.
For you as a shareholder, that mix ties directly into the catalysts. A fuller backlog can support future activity if projects are delivered on time and on budget, while lower leverage may give Enerflex more room to handle cyclicality in compression and processing demand. Execution on those two fronts will likely shape how much of that backlog turns into durable earnings rather than another round of compressed margins.
Enerflex’s analyst narrative points to revenues of about $2.9b and earnings of $259.1 million by 2029, based on revenue growing at 3.4% a year and earnings rising from $83.0 million today. This implies roughly a 3.1x increase in profit from current levels.
Uncover why Enerflex's fair value indicates a 35% potential upside to its current price that could narrow quickly.
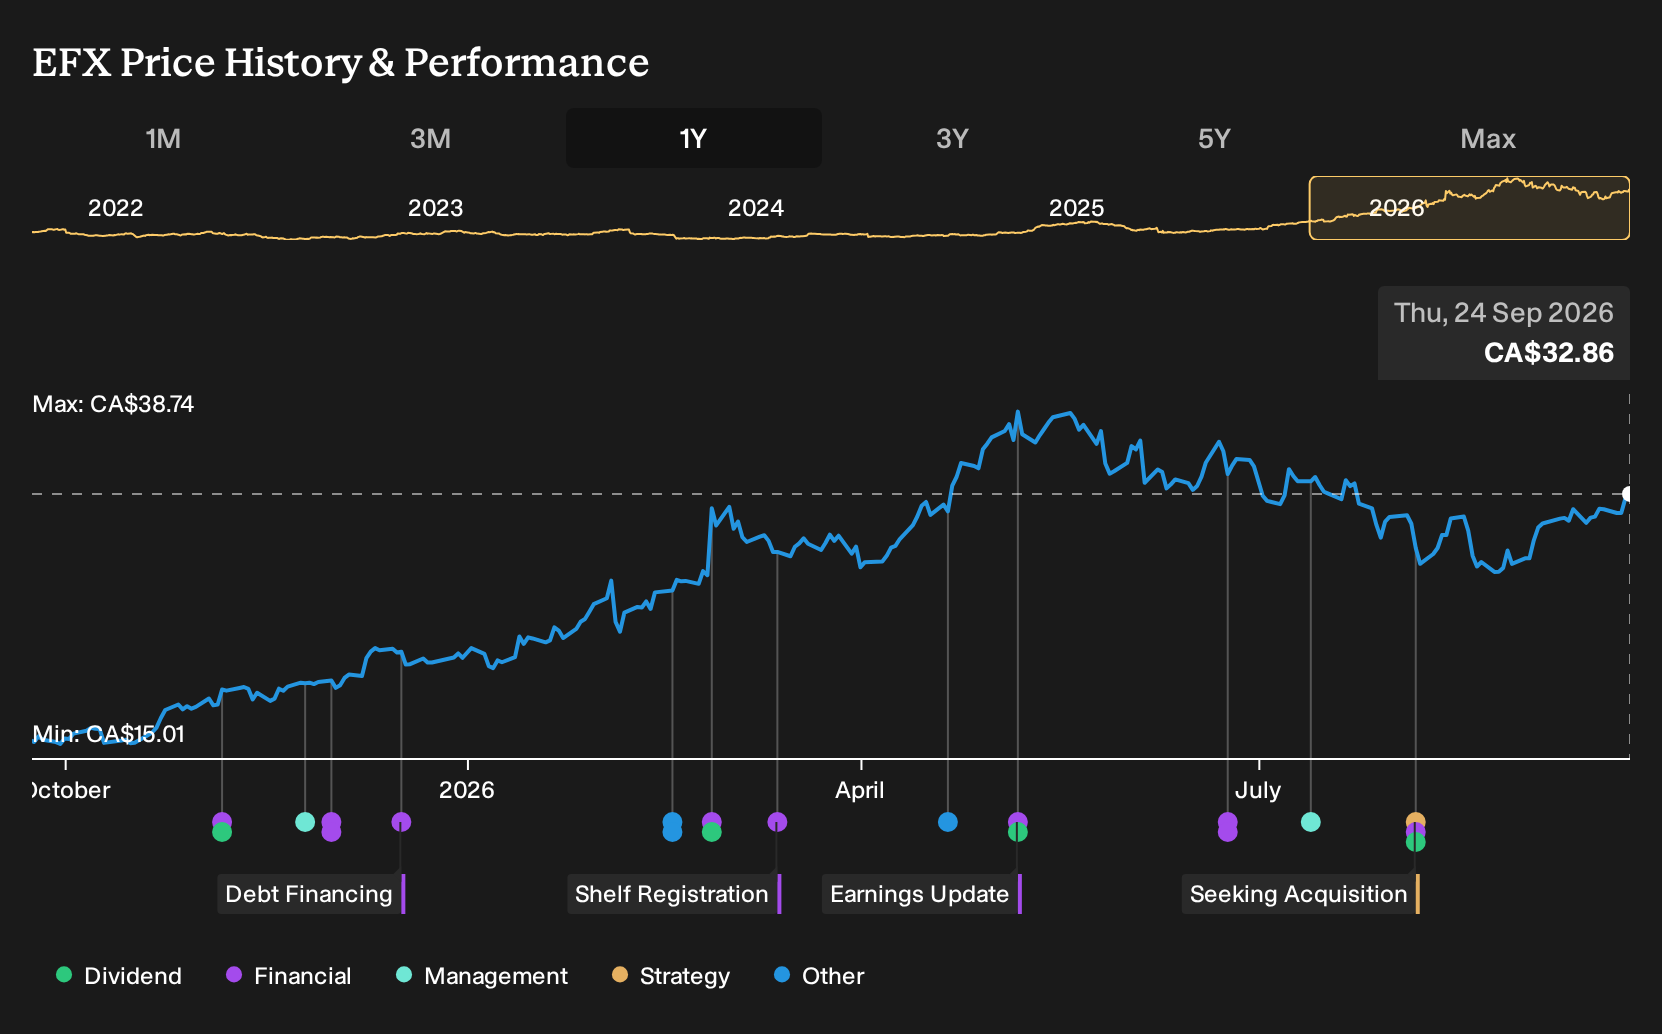
Exploring Other Perspectives
The most bearish analysts lean hard into execution risk on Enerflex’s huge capital plan. They were only pencilling in roughly flat revenue and about $204.1 million of earnings by 2029, compared with the consensus $259.1 million. That sets up a much cooler story. The fresh US$1.5b backlog could nudge those expectations, so it is worth comparing both narratives yourself.
Explore 3 other Enerflex fair value estimates, including one that suggests it could be worth just CA$42.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Enerflex research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enerflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerflex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Enerflex?
After weighing Enerflex against your own expectations, it can help to widen the lens and scan other companies with different return and risk profiles using the Simply Wall St Screener.
- If value is your priority, consider rounding out your watchlist with a 5 high quality undervalued stocks that combine strong fundamentals with pricing that screens as potentially attractive.
- If balance sheet strength matters most to you, review a list of solid balance sheet and fundamentals (7 results) that can help you focus on businesses with cleaner debt profiles and sturdier financial footing.
- If you prefer ideas that are off the beaten path, broaden your opportunity set with a 9 high quality undiscovered gems that may not yet be widely followed but still show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com