
Is Precigen (PGEN) Above Fair Value After The FDA Platform Nod?
Precigen has delivered very strong share price gains in recent years, and with the story now shaped by its sales and pipeline, investors are asking whether the current valuation still lines up with the underlying revenue base.
- Over the past 3 years the stock has climbed about 442%, which puts a lot of weight on whether the present share price can be supported by the company’s sales performance and prospects.
- The recent FDA platform technology designation for Precigen’s AdenoVerse immunotherapeutic platform may support expectations for future product launches and revenue, which matters a great deal when you are assessing a business that is still building out its commercial sales profile.
- The analysts covering Precigen have run their own numbers. See what analysts think Precigen's shares could be worth.
The stock's next move may depend on whether Precigen's current share price is well supported by the level and potential growth of its sales.
If you want more ideas with a similar focus on whether current prices line up with underlying sales, a focused stock screen is a useful next step via 30 high quality undervalued stocks.
Has Precigen Run Too Far on Sales?
P/S works better for Precigen than P/E because the business is still loss making and investors are mainly paying for access to its revenue and pipeline rather than current profits.
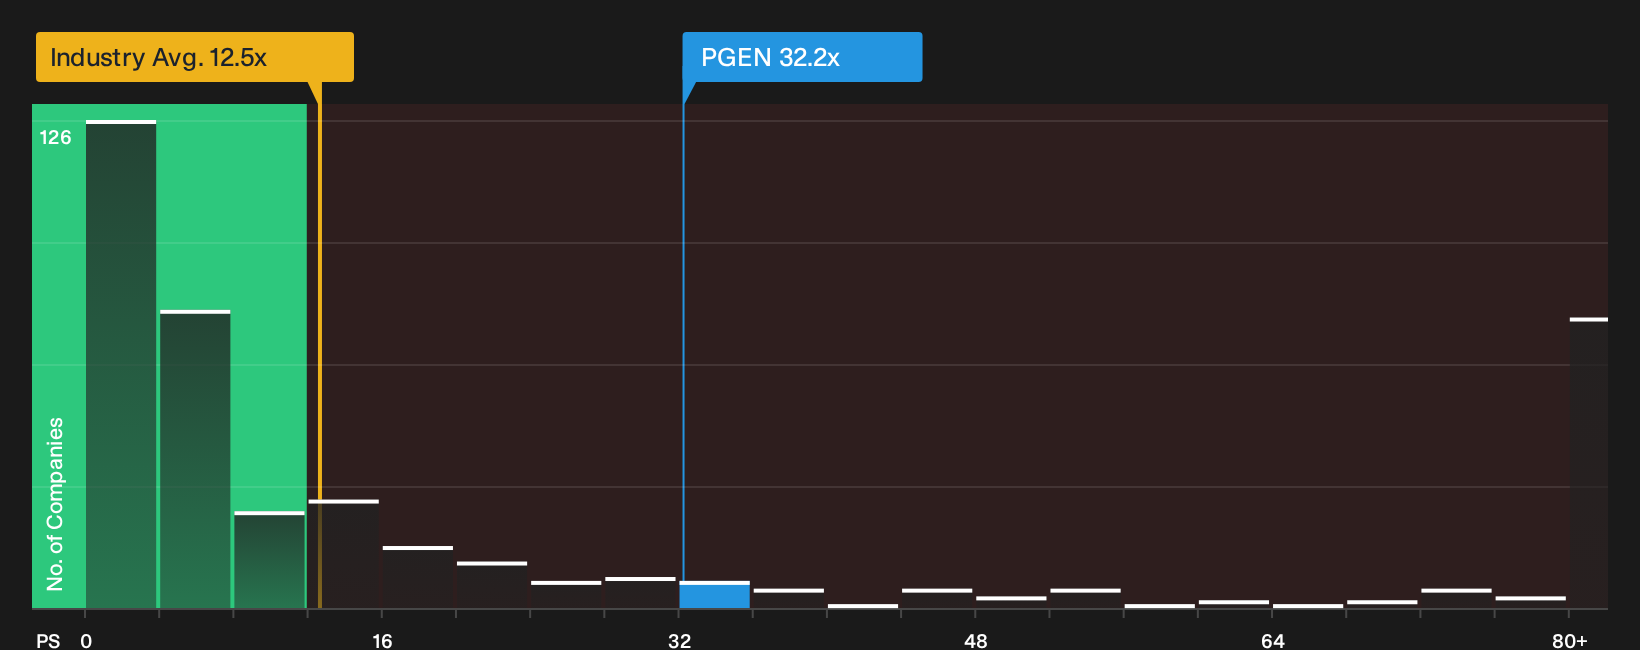
Despite the recent FDA platform technology designation for the AdenoVerse platform, the stock trades on a P/S ratio of about 32.2x, which is far above both the biotech industry average of 12.5x and the peer group at roughly 9.9x. The current figure also sits well above the multiple suggested by a more tailored fair value model that factors in Precigen’s growth profile, margins, size and risk. That model heavily penalises the company’s current losses, so the gap looks more like a warning flag than a precise target. That leaves you weighing whether the existing sales base and product pipeline justify paying such a steep revenue multiple today, or whether expectations have run ahead of what the business is currently delivering. Explore the numbers behind Precigen's P/S valuation.
The Precigen Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Precigen pick up where this valuation puzzle leaves you by spelling out which assumptions on growth, margins and future earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each narrative treats Precigen's inferred fair value as a thesis about the business that can be tracked over time, rather than a one-off snapshot.
One of the top community narratives on Precigen: 47% undervalued
"Bullish analysts see the seven years of FDA orphan-drug market exclusivity for Papzimeos in adult recurrent respiratory papillomatosis as a key support…"
Discover why this Narrative puts Precigen at 47% undervalued.
One more Precigen check that belongs beside the price tag
Valuation only tells part of the story, because Simply Wall St’s broader checks on Precigen also flag specific concerns that investors often weigh carefully before committing fresh capital. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com