
Is Generac Holdings Stock Underperforming the Nasdaq?
Generac Holdings Inc. (GNRC), headquartered in Waukesha, Wisconsin, designs, manufactures, and distributes various energy technology products and solution. With a market cap of $11.7 billion, the company offers generators to serve the residential, commercial, industrial, and telecommunications markets.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and GNRC definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the specialty industrial machinery industry. A leader in North American power generation with growing global reach, GNRC’s brand is built on engineering expertise and a broad lineup from standby to mobile units. Strategic acquisitions have evolved it from a backup generator firm into a diversified industrial tech company focused on energy resilience.
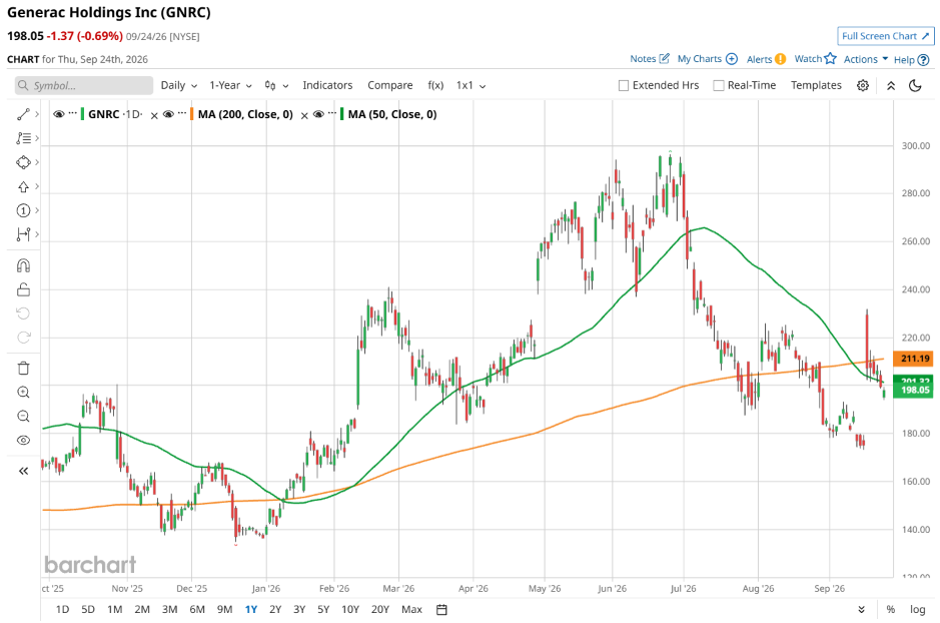
Despite its notable strength, GNRC slipped 33.2% from its 52-week high of $296.44, achieved on Jun. 25. Over the past three months, GNRC stock fell 30.3%, underperforming the Nasdaq Composite’s ($NASX) 6.2% gains during the same time frame.
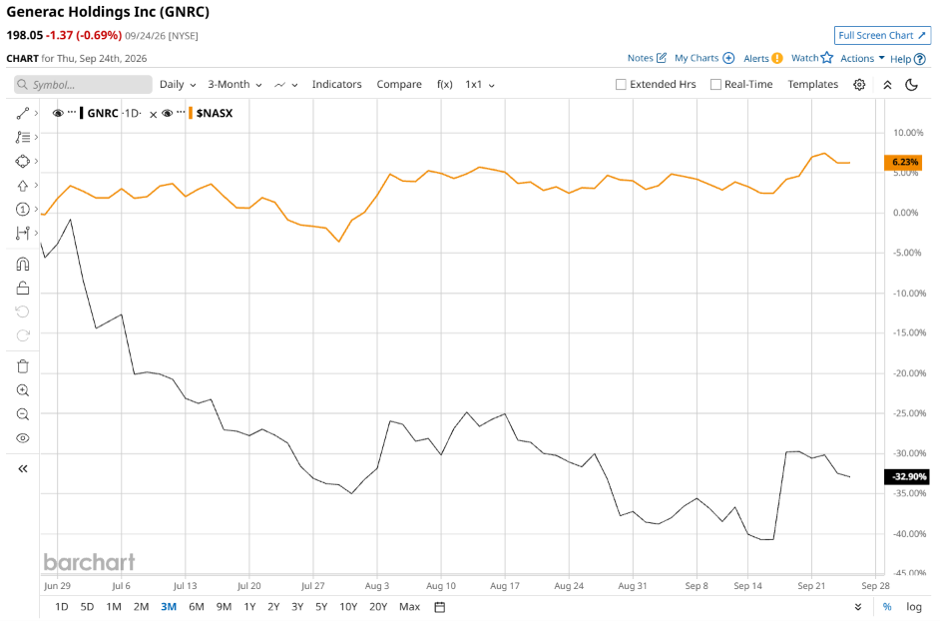
In the longer term, shares of GNRC rose 45.2% this year, outperforming NASX’s YTD gains of 15.9%. However, the stock climbed 18.3% over the past 52 weeks, underperforming NASX’s 20.4% returns over the same time frame.
To confirm the bearish trend, GNRC has been trading below its 50-day moving average since early July, with slight fluctuations. The stock is trading below its 200-day moving average since late July, with some fluctuations.
While GNRC has gained strong momentum in its Commercial & Industrial segment from hyperscale data center demand and multiyear generator backlogs, the stock has underperformed due to structural weakness in its core residential business. A mild power outage environment sharply reduced consumer urgency for home standby generators, driving a 23% decline in residential sales and creating unfavorable product mix shifts and operating deleverage. Furthermore, high interest rates and affordability headwinds dampened broader residential energy adoption, while Wall Street penalized earnings misses, elevated capital expenditures required to scale megawatt production, and execution complexity ahead of those data center commitments fully converting to bottom-line profit.
On Jul. 29, GNRC shares closed down marginally after reporting its Q2 results. Its adjusted EPS of $2.91 exceeded Wall Street expectations of $1.95. The company’s revenue was $1.17 billion, falling short of Wall Street forecasts of $1.18 billion.
In the competitive arena of specialty industrial machinery, Cummins Inc. (CMI) has lagged behind GNRC, with 2.1% gains on a YTD basis and 24.7% returns over the past 52 weeks.
Wall Street analysts are reasonably bullish on GNRC’s prospects. The stock has a consensus “Moderate Buy” rating from the 20 analysts covering it, and the mean price target of $295.69 suggests a notable potential upside of 49.3% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.