
What First Resources (SGX:EB5) Trade Truce Extension Means For Shareholders
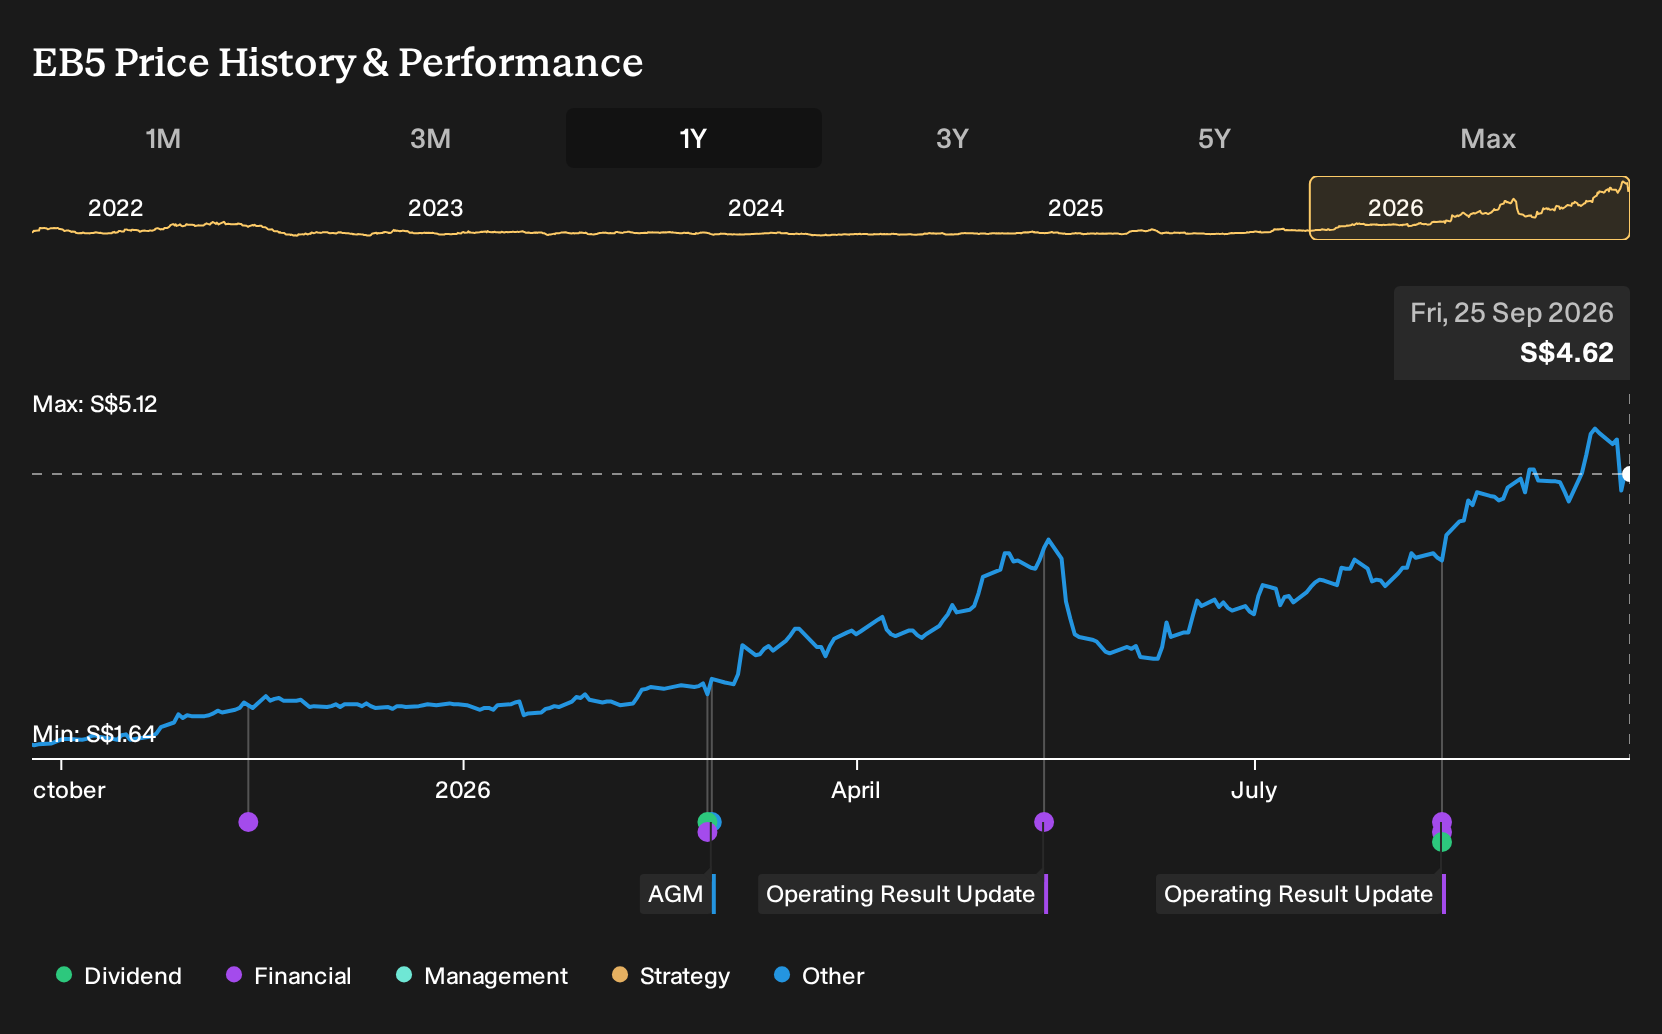
- First Resources emerged as the top gainer in the iEdge Singapore Next 50 Index, with the stock price at S$4.66 after a 5% move on the day regional markets ended lower ahead of the Trump-Xi summit, as investors assessed the extended US China trade truce to January 10, 2027.
- Investor interest in First Resources appeared linked to a friendlier US China trade backdrop, which can influence sentiment toward regional commodity producers that rely on predictable cross border demand and relatively stable trading conditions.
- Next, the focus will be on how First Resources' investment narrative interacts with this extended US China trade truce and the shift in sentiment.
Scan for other commodity plays reacting to the same US China trade truce by reviewing our curated list of solid balance sheet and fundamentals (202 results) that could handle cross border volatility more predictably.
What Is First Resources' Investment Narrative?
To own First Resources, you need to be comfortable with a real asset story that lives and dies by palm oil operations, pricing and capital discipline. The group runs plantations, mills and downstream processing, so utilisation rates, extraction yields and product spreads across CPO, palm kernel and refined products matter more than short term market noise. Earnings growth of 51.5% over the past year and 15.9% per year over five years points to solid execution, helped by high quality earnings and a Return on Equity of 27.8%. The extended US China trade truce mostly feeds into sentiment and cross border demand visibility rather than reshaping this core operating engine in the near term.
The bigger swing factors right now sit in how First Resources balances capital intensive estates and refining assets with a high level of debt and 100% higher risk funding sources, while revenue growth is forecast at only 0.5% per year and earnings at 1.4% per year. A share price of S$4.62 that is viewed as trading well below some fair value estimates, yet on a P/E of 12.7x that is richer than local peers but below the wider Asian food group, adds another layer of complexity. The truce extension may ease fears around export disruption and pricing shocks, but it does not directly solve the most important issue that sits underneath the recent rally.
Even so, there is a specific pressure point in the First Resources story that could matter more than the trade truce if ...
There's only one way to know the right time to buy, sell or hold First Resources. Head to Simply Wall St's company report for the latest analysis of First Resources's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from S$2.50 to about S$15.11 for First Resources, which shows how far apart retail views can be. These figures were set before the extended US China trade truce, so you are comparing older forecasts with a fresh macro backdrop that could reshape future expectations.
Explore 2 other First Resources fair value estimates, including one that suggests as much as 46% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Resources research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for First Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Resources' overall financial health at a glance.
Looking For More Ideas Beyond First Resources?
If you want to pressure test your view on First Resources or simply widen the opportunity set, using the Simply Wall St Screener can help you quickly spot other businesses that fit your risk and return preferences.
- If you are hunting for mispriced quality, scan for companies that combine strong balance sheets with appealing valuations through the 178 high quality undervalued stocks.
- For investors who care most about consistency and capital preservation, filter for companies with steadier profiles by checking the 227 resilient stocks with low risk scores.
- Income focused readers who want yield with fundamentals can zero in on payout heavy opportunities using the 159 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com