
TSX Growth Companies With High Insider Ownership September 2026
As the Federal Reserve's recent rate hike signals a modestly more hawkish stance, Canadian markets are closely watching the implications for their own economic landscape. In this environment of tightening monetary policy, growth companies with high insider ownership on the TSX may present intriguing opportunities, as insider confidence often aligns with strong fundamentals and potential resilience in fluctuating market conditions.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 47.9% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Let's take a closer look at a couple of our picks from the screened companies.
Vireo Growth (CNSX:VREO)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Vireo Growth Inc. is a cannabis company involved in the cultivation, manufacturing, processing, and distribution of medical and adult-use cannabis products across several U.S. states, with a market cap of CA$793.35 million.
Operations: Revenue Segments (in millions of $): null
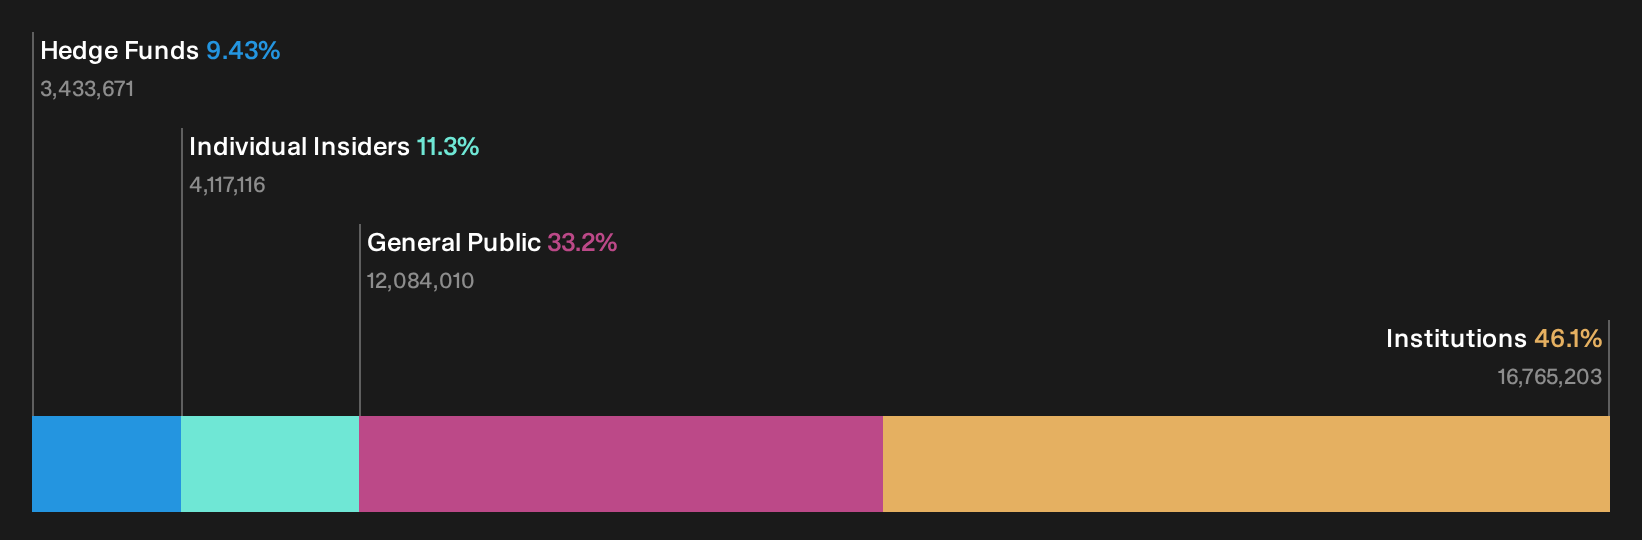
Insider Ownership: 11.3%
Revenue Growth Forecast: 24% p.a.
Vireo Growth demonstrates potential as a growth company with high insider ownership. Its revenue is expected to grow 24% annually, outpacing the Canadian market's average. Despite past shareholder dilution, Vireo is trading at a significant discount to its estimated fair value and plans to become profitable within three years. Recent strategic moves include securing an $85 million credit facility and initiating a share repurchase program, reflecting confidence in its financial health and future growth prospects.
- Get an in-depth perspective on Vireo Growth's performance by reading our analyst estimates report here.
- The analysis detailed in our Vireo Growth valuation report hints at an deflated share price compared to its estimated value.

Anaergia (TSX:ANRG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Anaergia Inc. operates with its subsidiaries to offer renewable energy generation and waste-to-resource conversion solutions across various regions including Italy, North America, Europe, the Middle East and Africa, and the Asia Pacific, with a market cap of CA$427.68 million.
Operations: Anaergia Inc.'s revenue is primarily derived from Capital Sales (CA$211.26 million), supplemented by O&M Services (CA$17.93 million) and Build, Own, and Operate activities (CA$13.00 million).
Insider Ownership: 24.3%
Revenue Growth Forecast: 14.3% p.a.
Anaergia shows promise with insider ownership and strong growth prospects. The company recently turned profitable, reporting Q2 sales of C$63.91 million, up from C$32.26 million a year ago, and net income of C$0.37 million compared to a loss previously. Earnings are forecast to grow 63% annually over the next three years, outpacing the Canadian market's average growth rate. Anaergia's recent contract in Australia further underscores its expansion efforts in renewable energy solutions.
- Delve into the full analysis future growth report here for a deeper understanding of Anaergia.
- Insights from our recent valuation report point to the potential overvaluation of Anaergia shares in the market.

Total Energy Services (TSX:TOT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Total Energy Services Inc. is an energy services company operating in Canada, the United States, Australia, and internationally with a market cap of CA$1.32 billion.
Operations: The company's revenue segments consist of Well Servicing at CA$130.72 million, Contract Drilling Services at CA$362.27 million, Compression and Process Services at CA$634.50 million, and Rentals and Transportation Services at CA$78.79 million.
Insider Ownership: 11.3%
Revenue Growth Forecast: 13.1% p.a.
Total Energy Services demonstrates robust growth potential with earnings forecast to grow at 23.1% annually, surpassing the Canadian market's average. Recent earnings reports show a significant increase, with Q2 sales reaching C$328.96 million and net income at C$26.69 million. The company trades well below its estimated fair value and maintains good relative value compared to peers. Despite no substantial insider buying recently, insider ownership remains high, reflecting confidence in future performance amidst strategic board changes and dividend affirmations.
- Dive into the specifics of Total Energy Services here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Total Energy Services is priced lower than what may be justified by its financials.
Where To Now?
- Take a closer look at our Fast Growing TSX Companies With High Insider Ownership list of 49 companies by clicking here.
- Want To Explore Some Alternatives? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com