
Is Clorox (CLX) Cheap Following Its Dividend Reaffirmation And Recent Slide?
Clorox (CLX) reaffirmed its dividend policy, with the board declaring a regular quarterly payout of $1.25 per share, payable on November 13, 2026, to shareholders of record as of October 28.
The reaffirmed dividend comes amid a weak price backdrop, with Clorox’s share price down 22.04% over the past 30 days and 18.89% year to date, while the 1-year total shareholder return has declined 30.23%. This points to fading momentum despite the steady payout.
Spot opportunities beyond Clorox's recent slump and compare this payout profile with a hand picked group of 8 dividend fortresses.Clorox now offers a higher yield on a lower share price, which leaves a blunt question on the table: Is the recent slide telling you something new about the business, or mostly about sentiment resetting around it before valuation catches up?
Most Popular Narrative: 18.8% Undervalued
On the latest numbers, the most followed narrative pegs Clorox’s fair value at $100.76, well above the recent $81.80 close. This puts the recent selloff against a story that leans heavily on margins and health and hygiene growth rather than short term price action.
The full-scale implementation of a modern ERP system is now moving from stabilization into optimization. Clorox has indicated that late FY27 and FY28 should see better demand fulfillment, lower inventories and more automation in order-to-cash and back-office functions, which would primarily support net margin and earnings.
See why 44 investors see Clorox as 19% undervalued.
Result: Fair Value of $100.76 (UNDERVALUED)
Still, the Clorox narrative can crack if sluggish category demand lingers or if rising input and supply chain costs squeeze margins more than expected.
Find out about the key risks to this Clorox narrative.
Another Look At Clorox’s Valuation Using P/E
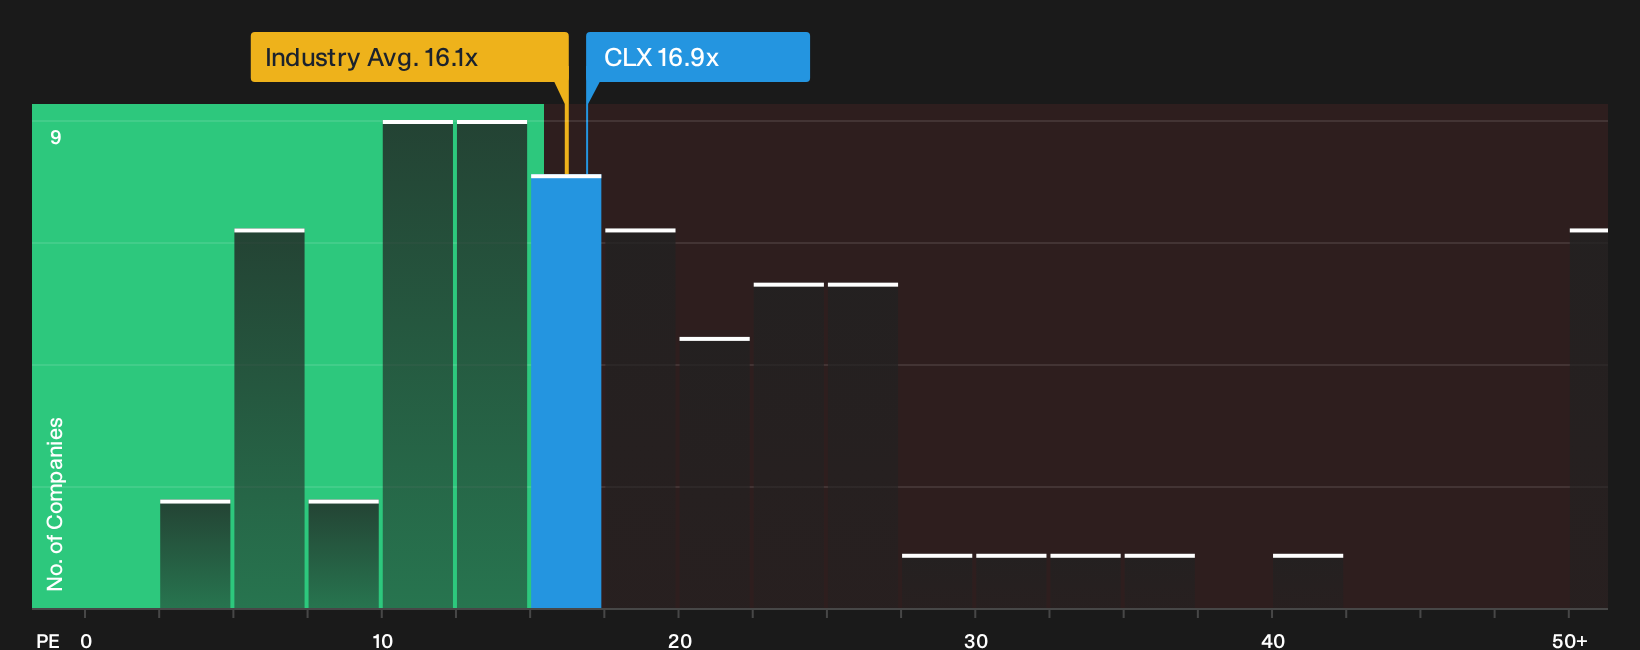
The DCF work suggests Clorox is significantly undervalued, yet the P/E picture is less extreme. The stock trades on 16.9x earnings, only slightly higher than the global household products group at 16.1x, and below an estimated fair ratio of 19.4x. That gap hints at some upside, but also signals that a lot depends on whether earnings forecasts hold up.
To pressure test that view further, it is worth asking how comfortable you are with paying a small premium to the sector today in exchange for the possibility that the share price moves closer to that fair ratio over time, or whether you prefer to wait for more evidence on margins before leaning on this kind of valuation gap.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Clorox is clearly mixed, with fresh price pressure sitting beside a steady dividend and a valuation story that still looks supportive to some investors. Act quickly, review the forecasts in detail, and weigh both sides of the ledger by checking the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Clorox?
Do not park everything in Clorox alone. Broaden your watchlist with a few focused idea lists that target different strengths and risk profiles.
Use the Simply Wall St screener to quickly surface fresh candidates that match your priorities before the next market move passes you by.
- Pinpoint potential mispriced opportunities early by scanning a curated set of 16 high quality undiscovered gems that pair quality fundamentals with quieter market attention.
- Dial back portfolio stress with 30 resilient stocks with low risk scores that emphasize resilient financials and calmer return profiles when volatility picks up.
- Build a dependable income stream around 8 dividend fortresses that combine robust payouts with balance sheets designed to support regular distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com