
How Investors May Respond To Photronics (PLAB) Earnings Beat
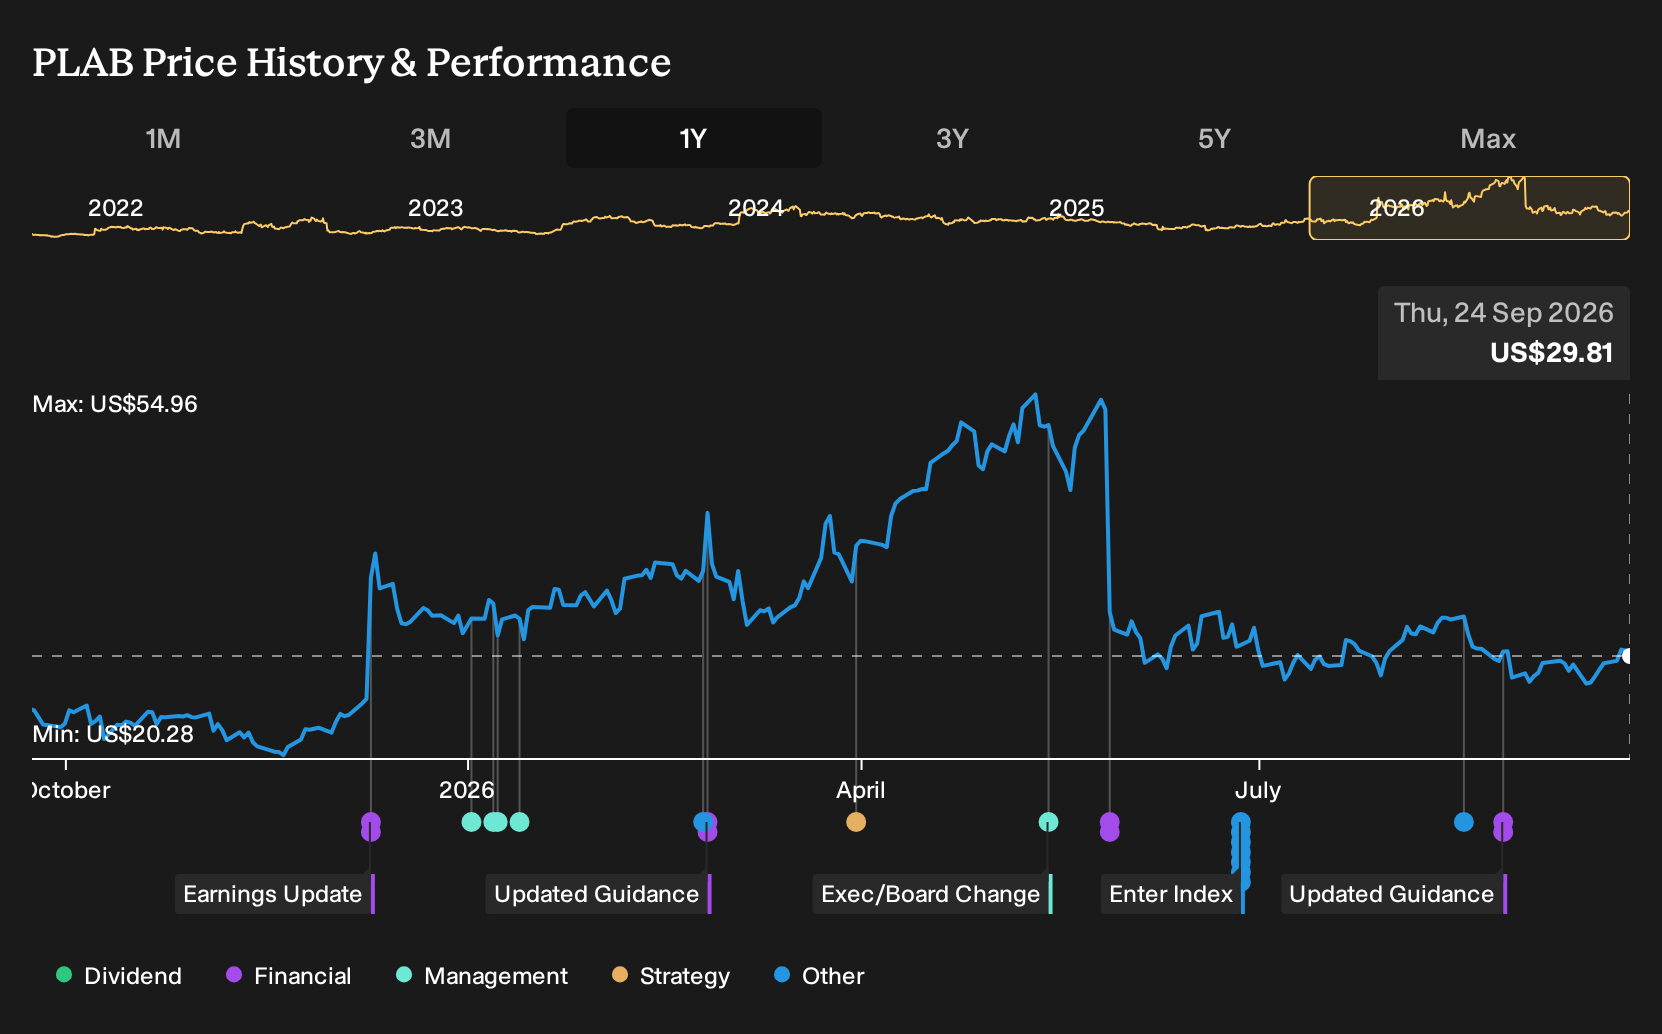
- Photronics reported Q3 FY26 earnings with EPS of 0.50 and earlier Q2 revenue of US$216 million that both surpassed analyst estimates, alongside commentary on strong fab utilization and active investments in the U.S. and Korea.
- The earnings beat sits alongside management highlighting a recovery in previously delayed semiconductor design releases, which points to healthier near term demand for Photronics’ photomask services.
- This article examines how Photronics' better than expected Q3 FY26 earnings performance could influence its broader investment narrative.
Scan how Photronics’ earnings surprise fits into the broader chip supply chain by comparing it with our curated 84 AI infrastructure stocks that are helping power semiconductor and AI fabrication capacity.
Photronics Investment Narrative Recap
To own Photronics, you need to believe that its photomask capacity, technology upgrades and global footprint keep it connected to steady chip and display design activity, even when orders arrive in short bursts. The Q3 EPS beat and earlier Q2 revenue strength support that view in the near term, since they point to healthy fab utilization and recovering design releases.
The key short term catalyst is whether that recovery in delayed semiconductor designs persists long enough to support high capital spending in the U.S. and Korea. The biggest risk is that demand proves choppy, given limited backlog visibility and customer concentration in Asia, which could stress cash flow while investment remains elevated.
The most relevant recent data point is the Q2 revenue line of US$216 million, which came in ahead of expectations and was paired with higher EPS and operating income than analysts projected. That operational outcome, followed by the Q3 EPS beat, suggests Photronics is currently executing well against its own spending and utilization plans.
Chairman and CEO George Macricostas also pointed to a recovery in temporarily delayed design releases and strong fab utilization, as well as ongoing investments in the U.S. and Korea. For investors, those comments connect the near term beat directly to longer term catalysts around advanced node exposure and reshoring, while also highlighting the execution risk if end demand slows before those new tools fully contribute.
Photronics' analyst narrative projects US$930.0 million in revenue and US$81.2 million in earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings decline of US$77.9 million from US$159.1 million today.
Discover why Photronics' fair value indicates a 44% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$33.64 and US$43 per share, so private investors are already assigning a fairly tight but varied range to Photronics. When you set those views against unresolved trade restrictions and heavy capex demands, you can see why opinions may diverge sharply. Explore the full spread of community views before forming your own stance.
Explore 2 other Photronics fair value estimates, including one that suggests as much as 44% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Photronics research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Photronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Photronics' overall financial health at a glance.
Looking For More Ideas Beyond Photronics?
If Photronics has sharpened your interest in semiconductor related opportunities, it can help to widen the lens and compare it with other businesses that match your preferred risk, income, or balance sheet profile. The Simply Wall St Screener is built for that kind of side by side work, so you can stress test your thesis rather than rely on a single stock.
- For investors who care most about resilient businesses, start with a curated group of companies that score well on financial strength and stability using the 30 resilient stocks with low risk scores.
- If income is a priority, you can focus on companies that combine higher yields with balance sheets that look built to sustain them over time through the 8 dividend fortresses.
- Readers hunting for opportunities that are less picked over by the market may want to scan a hand picked 16 high quality undiscovered gems with solid fundamentals and room for the story to develop.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com