
Iridium (IRDM) Stock May Trade At A 41% Discount On Cash Flow
Iridium Communications has delivered a powerful run over the past year, and the latest share price puts a lot of weight on what its future cash flows can support. With the valuation lens focused squarely on those cash flows, the question now is how much of that performance is already embedded in today's price.
- The stock has returned 186.3% over the past 12 months. This puts fresh pressure on whether the current market value lines up with what the business can earn in cash terms.
- The company relies on capital intensive satellite infrastructure, so expectations for how efficiently that network converts revenue into cash may drive how sustainable the present valuation is.
- Prefer to judge Iridium Communications on earnings? See why Iridium Communications's 55.5x P/E tells a different valuation story.
The issue now is whether today's Iridium Communications share price is adequately supported by the cash flows implied by its intrinsic value estimate under the Discounted Cash Flow (DCF) approach.
Before examining whether Iridium Communications' 186.3% one-year return is supported by its cash flows, it can be useful to compare that narrative with a focused screen of 30 high quality undervalued stocks.
Is Iridium Communications Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) method looks at what Iridium Communications’ future cash generation could be worth in today’s money. On this model, the latest twelve month Free Cash Flow sits at about $308.0 million, with the projections assuming that free cash flow continues to grow from this level rather than reset sharply lower.
Those cash flow forecasts stay in a fairly tight band a few years out, which implies a business that the DCF treats as building on its current satellite footprint, not one needing a complete reinvention. Because the DCF projections put Iridium Communications' estimated intrinsic value substantially above the current share price of $48.89, the model suggests the market is not fully reflecting those projected cash flows in the current quote. Find out what Iridium Communications could be worth using our Discounted Cash Flow (DCF) estimate.
The Iridium Communications Narrative: What Would Justify Today's Price?
Iridium Communications' recent share price strength raises a simple question that Narratives try to unpack for you. Narratives act as a bridge from the DCF puzzle to concrete expectations, by spelling out what kind of growth, margins and earnings path would need to play out for the stock to be worth meaningfully more or meaningfully less than today, and each one focuses on the assumptions behind its fair value so you can later compare them with actual results on Simply Wall St's Community page.
Iridium Communications splits opinion, with one group seeing more upside left in the story while another views it as closer to fully priced.
Bull case: 9% undervalued
"With its capital expenditure cycle winding down and a deleveraging path already underway, Iridium is set for rapid free cash flow growth and meaningful shareholder returns…"
Discover why this Narrative puts Iridium Communications at 9% undervalued.
Bear case: 16% overvalued
"The rapid advances and aggressive rollouts of competing low-earth orbit mega-constellations, such as Starlink and Amazon Kuiper, have the potential to outpace Iridium's capabilities on price and data bandwidth…"
Explore why this Narrative puts Iridium Communications at 16% overvalued.
One more Iridium Communications signal that could change how you read this chart
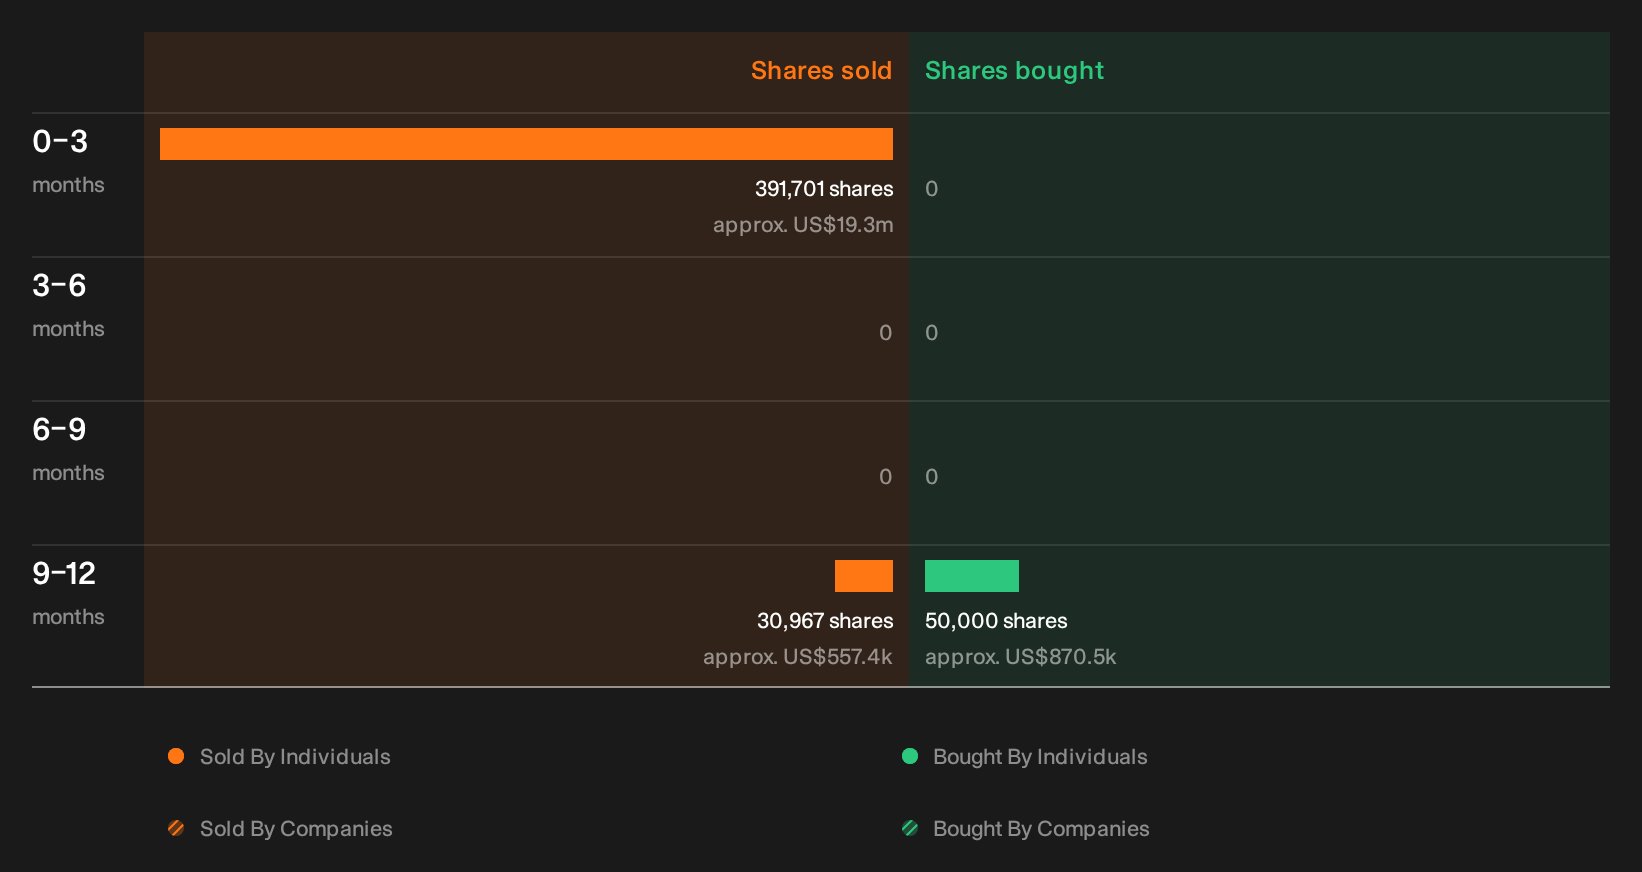
There is one loose thread that the cash flow work does not touch: the pattern of recent insider share sales and what those trades might say about confidence inside the business. See the recent insider selling flagged for Iridium Communications.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com