
Customer Expansion Might Change The Case For Investing In Agilysys Stock (AGYS)
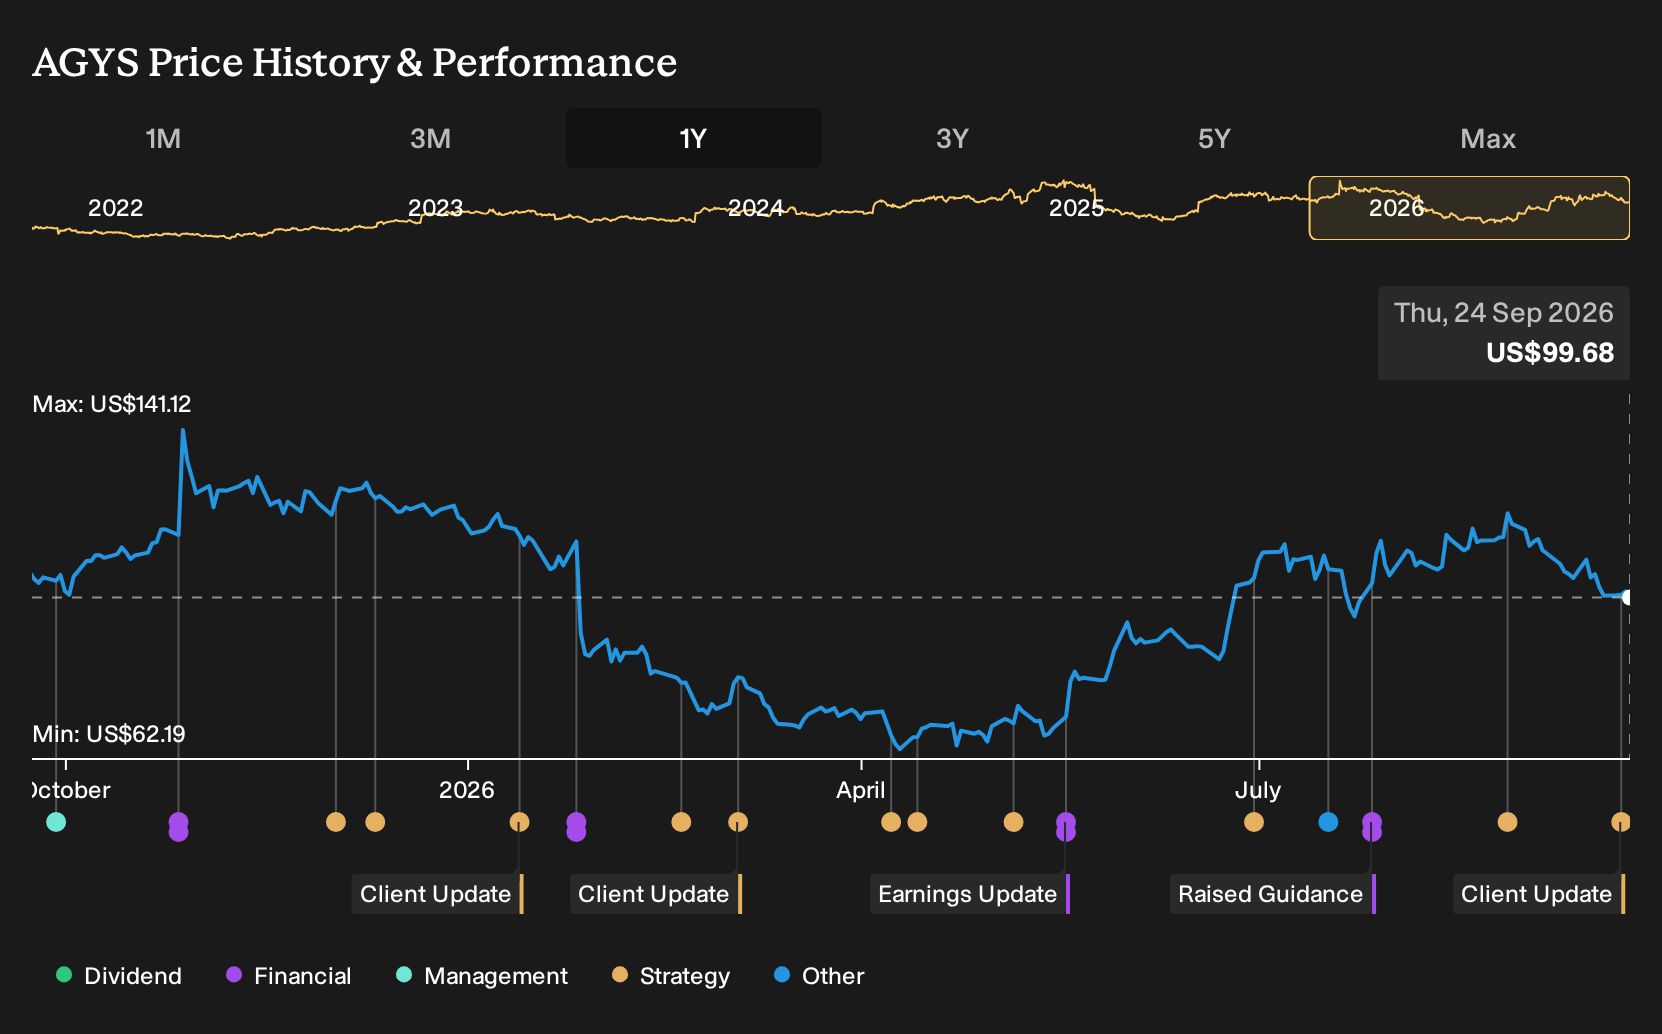
- On 22 September 2026, Agilysys reported that Angel of the Winds expanded its use of the Agilysys hospitality ecosystem across property management, online booking and food and beverage point of sale, including InfoGenesis 12UX, IG OnDemand and IG Kiosk for poolside service.
- The rollout at Angel of the Winds highlights how a single customer can adopt multiple Agilysys modules, which can deepen product stickiness, support cross selling and reduce training complexity for hospitality staff.
- We will now look at how Agilysys' investment narrative is shaped by this deeper Angel of the Winds ecosystem deployment.
Scan how hospitality tech plays out across the market by comparing Agilysys with a curated group of operators in the list of solid balance sheet and fundamentals (24 results).
Agilysys Investment Narrative Recap
To own Agilysys, you need to buy into a simple idea. Hospitality operators keep replacing patchwork legacy systems with a unified software stack that runs property management, booking and food and beverage on one platform. The Angel of the Winds expansion fits this thesis, but on its own it does not change near term expectations in a material way.
The key short term swing factor remains execution on the SaaS and ecosystem story at scale, not a single customer case study. The biggest risk is still heavy reliance on cyclical hospitality spending, where a weaker travel backdrop or tighter budgets could slow new deals and lengthen sales cycles even if existing sites deepen adoption.
The most relevant recent item alongside the Angel of the Winds rollout is Agilysys presenting at the Piper Sandler Growth Frontiers Conference on 14 September 2026. That appearance puts management in front of institutional investors immediately after showcasing a complex, multi module deployment at a high profile resort property.
For you, the link between the conference and this customer news is about credibility on the core catalysts. The firm is emphasizing a high margin SaaS mix, deeper product integration and a record implementation pipeline. Investors are weighing those positives against richer P/E multiples, concentrated hospitality exposure and rising operating spend on product and sales capacity.
Agilysys' current analyst narrative points to forecast revenue of $523.9 million and earnings of $91.9 million by 2029, built on an assumed 16.6% yearly revenue growth rate and an earnings increase of about 2.1x from $42.9 million today.
Uncover how Agilysys' fair value indicates a 34% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One contrasting angle focuses on cybersecurity and compliance costs. The most cautious Agilysys analysts worry these outlays could eat into profitability, even with ecosystem wins like Angel of the Winds. They were modeling about $509.5 million of revenue and $98.8 million of earnings by 2029, so their fair value view stayed tighter. Those expectations were set before this customer expansion, which is why it can be useful to compare several narratives and decide whether this kind of deployment might eventually shift them.
Explore 3 other Agilysys fair value estimates, including one that suggests as much as 80% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis when forming an investment view.
- A great starting point for your Agilysys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agilysys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilysys' overall financial health at a glance.
Looking for more Agilysys-like investment ideas?
If Agilysys has sharpened your view on what you want from a hospitality tech position, it can help to widen the lens and compare it with other businesses that fit your risk, income and quality preferences using the Simply Wall St Screener.
- If you prefer quality at a discount and a margin of safety on price, then scan a curated set of 30 high quality undervalued stocks that may line up better with your expectations.
- If resilience matters more than excitement, filter for companies with steadier profiles and review a 30 resilient stocks with low risk scores that might suit a more cautious approach.
- If you are interested in earlier stage potential with tighter fundamentals, you can hunt through a 8 elite penny stocks with strong financials and see which stories you find compelling.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com