
Disco Stock And 2 Other Japanese Quality Stocks
Japanese government bond yields recently reached a 30-year high as part of a broader global bond selloff, putting borrowing costs back in the spotlight. When debt gets pricier and more volatile, investors often pay closer attention to businesses with strong balance sheets and solid returns on equity. This article looks at three Japan stocks from a quality-focused screener that filters for robust finances and consistent fundamentals.
The stocks in the list below are just a sample, as the full solid balance sheet and fundamentals screen surfaced 19 more companies with equally compelling stories that are not covered here. If you want to identify and analyze those high conviction ideas alongside the ones in this article, head straight to the Solid Balance Sheet and Fundamentals screener.
Disco (TSE:6146)
Disco is a precision equipment maker that supplies cutting, grinding and polishing machines for semiconductor manufacturing, along with consumable tools that keep this high margin activity recurring. The business generated about ¥461.3b from precision processing systems and has a market value of roughly ¥5.8t.
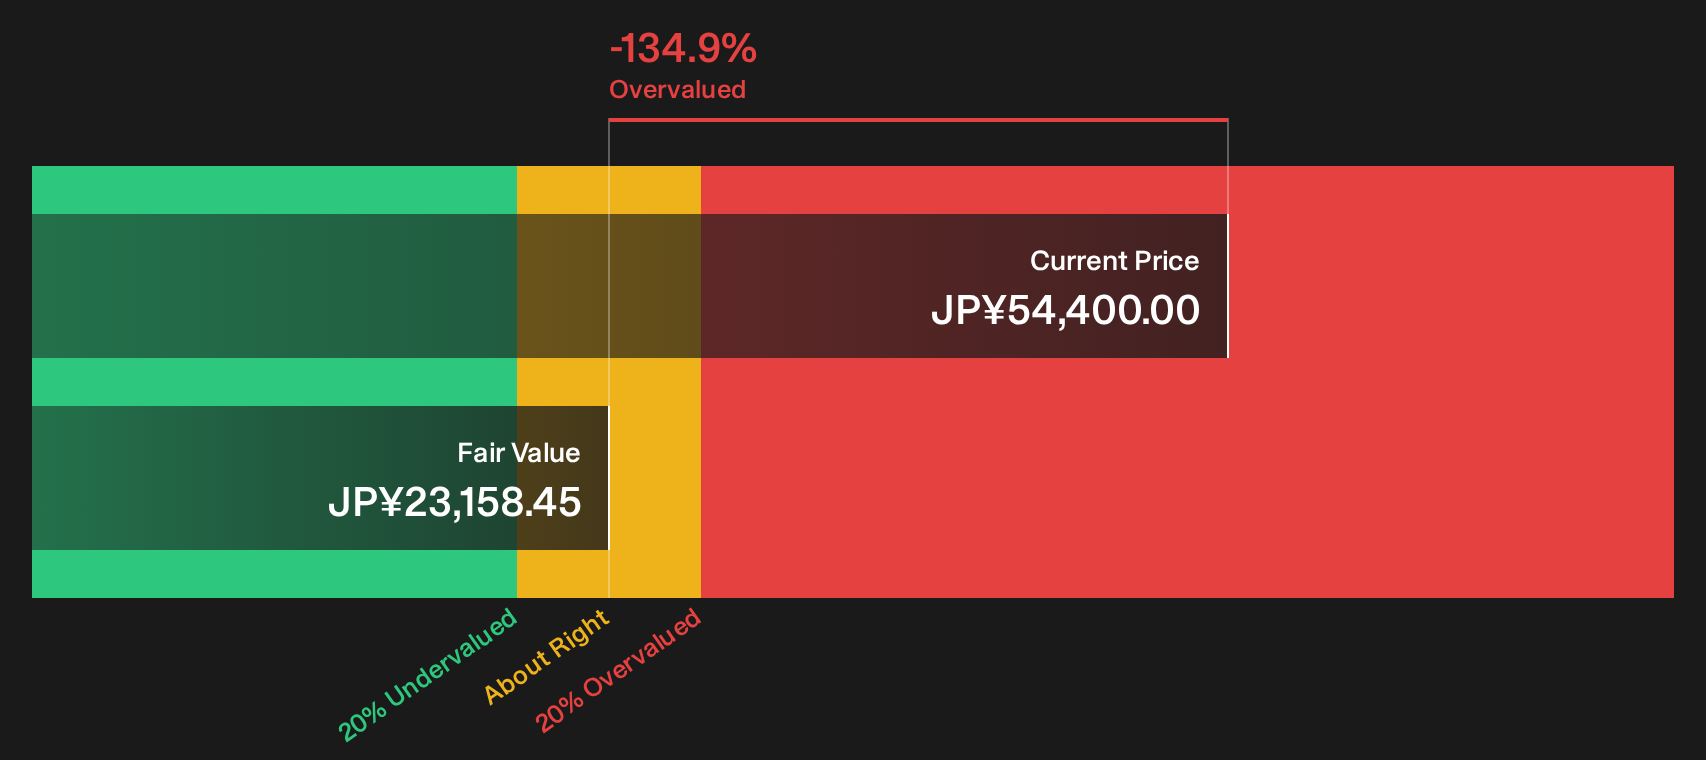
High return on equity of about 25% paired with net profit margins above 30% places Disco in the solid balance sheet and fundamentals camp. The trade off is a rich 40.4x P/E and a share price above estimated cash flow value. This keeps future returns sensitive to how one unseen pressure plays out.
To see how that pressure could reprice Disco’s rich multiple, review the 3 key rewards and 1 important major warning sign and identify what the headline numbers might be masking.
ASICS (TSE:7936)
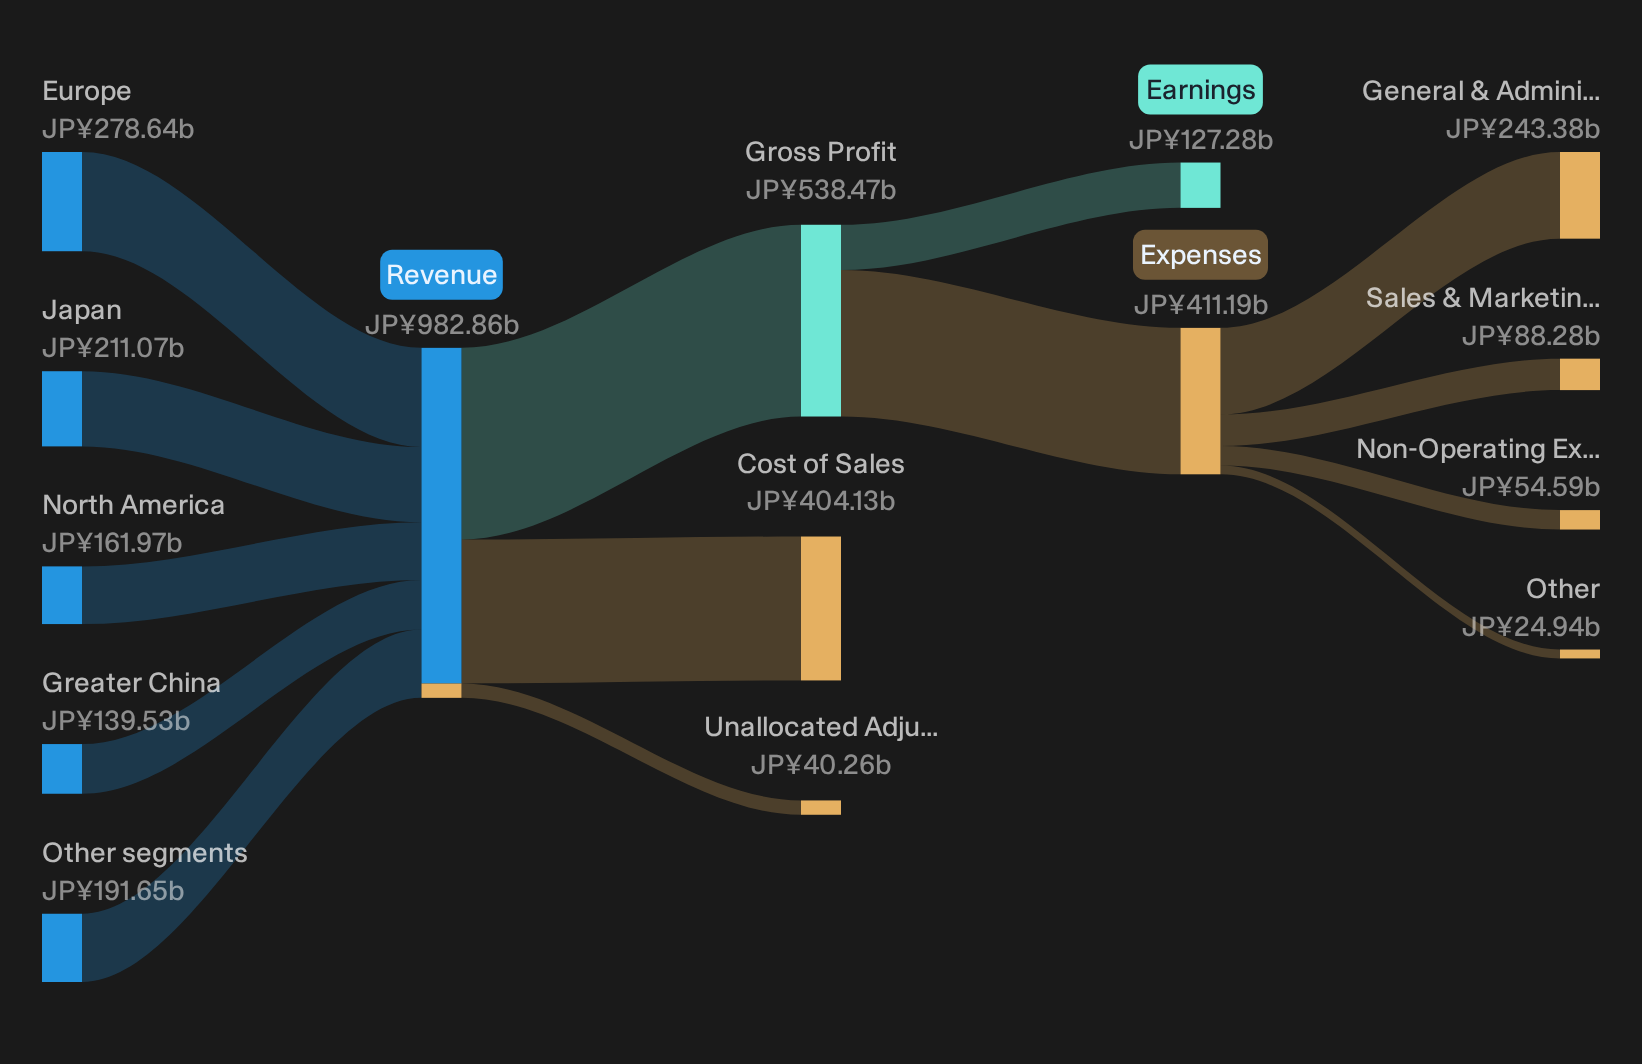
ASICS is a global athletic footwear and apparel group best known for its running shoes and performance sportswear, which anchor its fit with the solid balance sheet and fundamentals theme. It generated about ¥211.1b in Japan, ¥278.6b in Europe and ¥162.0b in North America, with smaller contributions from other regions. The company’s market cap is roughly ¥2.9t.
High quality fundamentals are front and center for ASICS. Return on equity sits around 35.4% and net profit margin is 13.5%, supported by strong running and performance lines that help keep pricing firm and cash generation healthy. Recent buybacks and dividend lifts underline that balance sheet strength. However, a single shift in demand or brand momentum could quickly change how secure those margins feel.
A shift like that can happen fast, so review the 4 key rewards and 1 important warning sign to see where ASICS’ strong metrics could start decoupling from sentiment.
Recruit Holdings (TSE:6098)
Recruit Holdings runs a mix of HR technology platforms, staffing operations and marketing services, with online matching tools like Indeed and Glassdoor driving the high return on equity profile that fits this screener. HR Technology contributes about ¥1,572.1b of revenue, staffing adds roughly ¥1,750.5b, and marketing matching a further ¥569.7b, against a market cap near ¥22.3t.
Recruit Holdings’ online HR platforms give the business a scalable, recurring fee engine that lines up neatly with the solid balance sheet and fundamentals theme, especially as hiring moves further online and data becomes a bigger edge.
"Recruit Holdings' unique access to large volumes of proprietary matching and conversational data, combined with advanced vertical AI development for specialized HR processes, positions the company to create best-in-class, defensible user experiences that will attract and lock in both employers and job seekers globally. This supports multi-year engagement growth and significant revenue upside."
What happens to Recruit Holdings’ earnings power if a single key assumption about how efficiently that data can be monetised starts to shift?
If that assumption starts to shift, read the full narrative for Recruit Holdings to see how Recruit Holdings’ data engine could either accelerate or stall the next phase of its story.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move from quiet to breakout while investors hesitate and watch momentum fly without them. Spot ideas still under the radar for now and act now.
- Target income streams that aim to keep paying even when sentiment drops by scanning curated 15 dividend fortresses built around durability and consistency.
- Chase early upside in future materials demand by reviewing carefully filtered 17 top copper producer stocks that could benefit if long term infrastructure spending gains momentum.
- Track new waves in automation before they get fully priced by assessing hand picked 93 robotics and automation stocks powering factories, logistics and next generation industrial systems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com