
Fiserv (FI) Stock May Be Below Fair Value On CEO Monetization Push
Fiserv has seen a steep reset in its share price over the past year, and the scale of that decline puts a spotlight squarely on whether the current valuation is still aligned with the earnings power of the business. With investors watching the company’s reshaping efforts, the key issue is how much of its profit story is already reflected in the stock.
- The share price has fallen 64.5% over the past year, which puts pressure on the question of what the market is now assuming about Fiserv’s earnings profile.
- Management’s plan to better monetize core operations while selling standalone units may support a sharper focus on higher margin segments, which can influence what investors are prepared to pay for each dollar of profit.
- The analysts covering Fiserv have run their own numbers. See what analysts think Fiserv's shares could be worth.
The stock’s next move may depend on whether today’s price fairly reflects what Fiserv is currently earning and is expected to earn in the future.
If you want a wider view alongside Fiserv, a focused screener of 30 high quality undervalued stocks.
Does Fiserv Look Undervalued on Earnings?
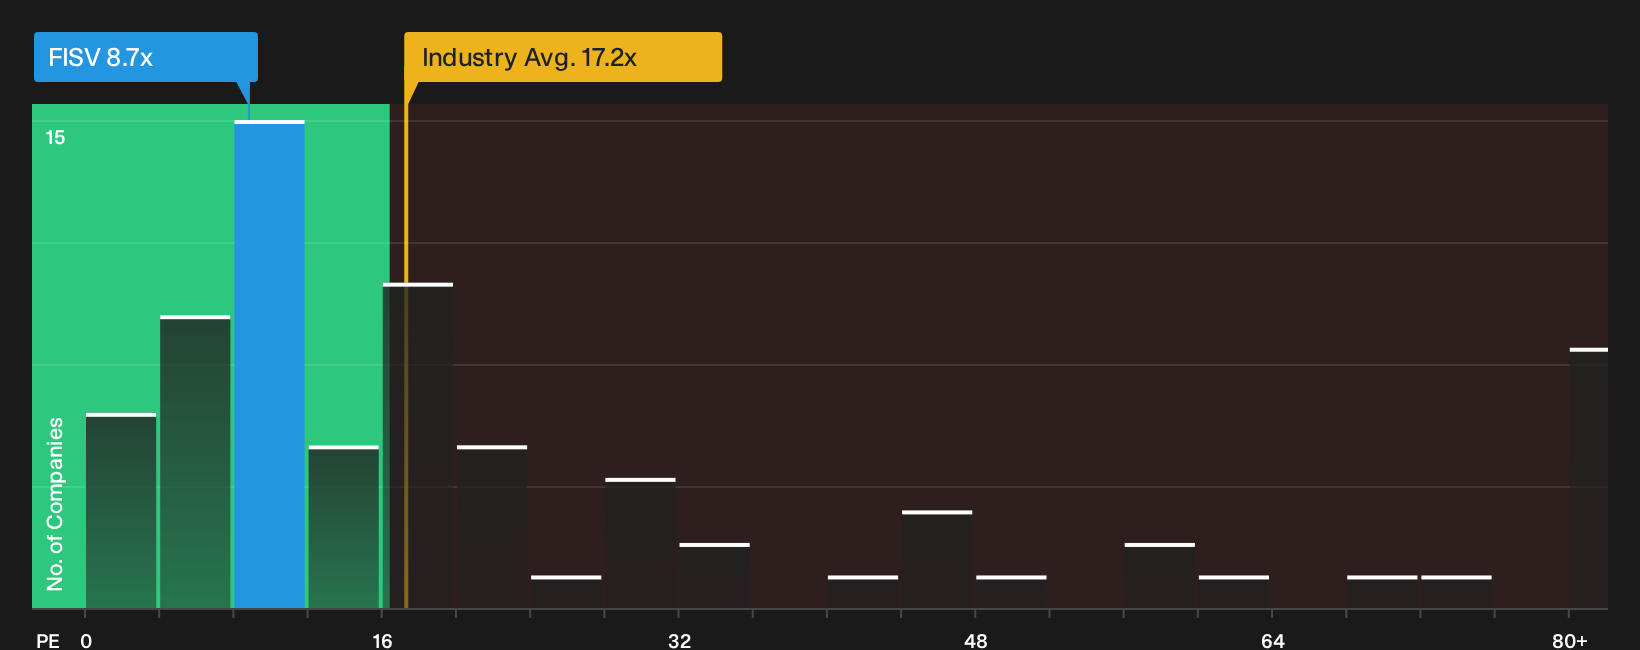
P/E suits Fiserv because earnings are a key focus for investors in established financial infrastructure providers. The stock currently trades on a P/E of 8.7x, which is well below the Diversified Financial industry average of 17.2x and also under the broader peer group on 20.8x. On this yardstick, the market is paying much less for each dollar of Fiserv’s earnings than for many comparable financial companies.
The fair-value model, which adjusts for factors such as expected profitability and risk, points to a higher P/E than where Fiserv trades today, so the shares screen as undervalued on this framework. Because management is reviewing standalone units and pushing harder to monetize core products, the current discount suggests investors are not paying up for that potential at this stage. Despite this refocus under the CEO’s plan, the earnings multiple still prices Fiserv at a material gap to what the tailored model implies. Explore the numbers behind Fiserv's P/E valuation.
The Fiserv Narrative: What Would Justify Today's Price?
Fiserv’s Simply Wall St Narratives pick up from this valuation puzzle and spell out which combinations of future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or materially less than today’s share price. Each narrative sets out Fiserv’s implied fair value as a thesis about how the business could perform over time, so you can track whether that story holds up as new information arrives.
The Fiserv community splits between investors who see a reset opportunity and those who focus on technology and execution risks that could cap what the stock is worth.
Bull case: 62% undervalued
"But underneath the surface, we believe the new management team is taking the right steps to transform itself into one of the highest-quality financial technology franchises in the world..."
Discover why this Narrative puts Fiserv at 62% undervalued.
Bear case: 15% overvalued
"Intensifying competition from technology giants such as Apple, Google, and Amazon expanding aggressively into payments and fintech services, as well as the proliferation of low-cost and alternative real-time payment networks, could significantly erode Fiserv's market share and pricing power..."
Explore why this Narrative puts Fiserv at 15% overvalued.
Fiserv’s valuation story leaves one crucial issue unresolved
Price and profit are only part of the puzzle for Fiserv, because separate red flags in the background could change how comfortable you feel with the whole picture. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com