
Cipher Digital (CIFR) Extends Barber Lake Leases, Is The Stock Cheap?
Why Cipher Digital’s Barber Lake deal matters now
Cipher Digital (CIFR) just reshaped its Barber Lake data center economics by doubling the contracted lease term to 20 years and lifting total contracted revenue from US$3.8b to more than US$9b.
Cipher Digital’s Barber Lake update comes at a time when the share price has risen 10.97% over the past 30 days and 11.73% year to date, yet is still down 30.22% over three months. The 1-year total shareholder return of 55.23% and the very large 3-year total shareholder return of about 7x suggest that long-term momentum has been strong even as shorter-term sentiment has cooled.
Scan how Cipher Digital compares with other data center and AI infrastructure plays by reviewing the hand picked 84 AI infrastructure stocks shaping this build out trend.
Cipher Digital now trades almost 30% below its US$30.74 analyst target after a sharp three month pullback. Is that discount a margin of safety, or a warning that the market’s caution on Barber Lake risk is justified?
Most Popular Narrative: 43% Undervalued
On the most followed view of Cipher Digital, a fair value of $31.78 sits well above the recent $18.10 close, which puts Barber Lake’s long lease and contracted revenue squarely in focus for valuation debates.
The rapid expansion and optimization of production capacity, notably through adding Black Pearl Phase 1 and the upcoming Phase 2, along with fully funded next-generation miner deployments, positions Cipher to significantly increase its hash rate and Bitcoin output, directly supporting future top-line revenue growth.
Industry-wide demand for large-scale, flexible, and energy-rich data center sites, driven by accelerating institutional and mainstream adoption of digital assets and AI, aligns with Cipher's strategy to develop infrastructure that can quickly pivot between Bitcoin mining and high-performance computing (HPC), creating upside potential for both revenue diversification and earnings stability.
See why 89 investors see Cipher Digital as 43% undervalued.
Result: Fair Value of $31.78 (UNDERVALUED)
Still, Cipher Digital’s heavy reliance on Bitcoin mining and the long timeline around ERCOT’s Batch Zero approvals could both derail the fair value narrative if conditions turn less favorable.
Find out about the key risks to this Cipher Digital narrative.
Another View: Cipher Digital Through The Revenue Lens
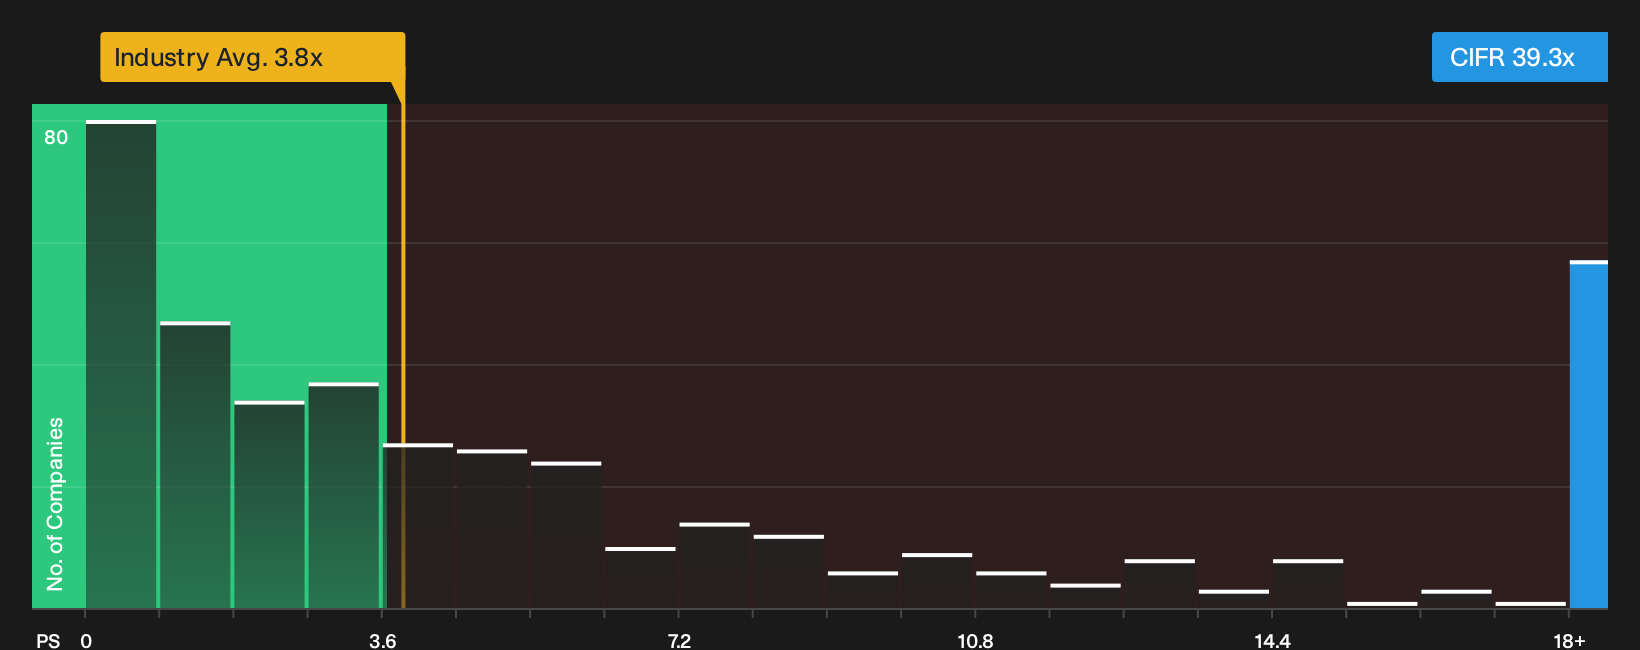
Cipher Digital may look cheap against the $31.78 fair value narrative, yet its current P/S ratio of 39.3x tells a very different story. That multiple is far above the US Software sector average of 3.8x and a peer group level of 16.5x.
The fair ratio sits at 3.7x, which is a big step down from where Cipher Digital trades today and signals valuation risk if sentiment or growth expectations cool. The question for you is simple: is this pricing power, or pressure waiting to show up in the share price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Cipher Digital’s valuation and risk profile can be confusing, so review the data for yourself, move efficiently, and weigh the 1 key reward and 2 important warning signs
Looking for more Cipher Digital style ideas?
If Cipher Digital’s setup has you thinking about your next move, do not stop here. Broaden your watchlist with focused screens that surface clear, data backed opportunities other investors might overlook.
- Target potential mispricings by scanning companies that combine strong fundamentals with appealing valuations through the 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with resilient cash flows and yields using the 8 dividend fortresses.
- Prioritize resilience by filtering for companies with robust finances and lower risk profiles in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com