
Is Williams Companies (WMB) Stock Already Priced Close To Fair Value?
Williams Companies has delivered a powerful multi year share price run, which puts a spotlight on whether the current valuation is still grounded in its earnings. With the stock now trading at US$70.58, the key issue is how much of the pipeline operator's profit profile is already reflected in that price.
- Over the past 5 years the share price has risen 238.9%, which raises the question of how much of Williams Companies' earnings power is already embedded in the valuation.
- The business generates income from fee based energy infrastructure, which can support relatively visible earnings and places extra focus on how reliably those profits convert into cash that justifies the equity valuation.
- The analysts covering Williams Companies have run their own numbers. See what analysts think Williams Companies's shares could be worth.
The stock's next move may depend on whether Williams Companies' current price is adequately supported by the earnings it produces today and is expected to generate in the future.
If you are weighing whether Williams Companies' earnings justify its recent run, it can help to compare that picture with a focused list of 30 high quality undervalued stocks as a fresh research starting point.
Does Williams Companies Look Fairly Valued on Earnings?
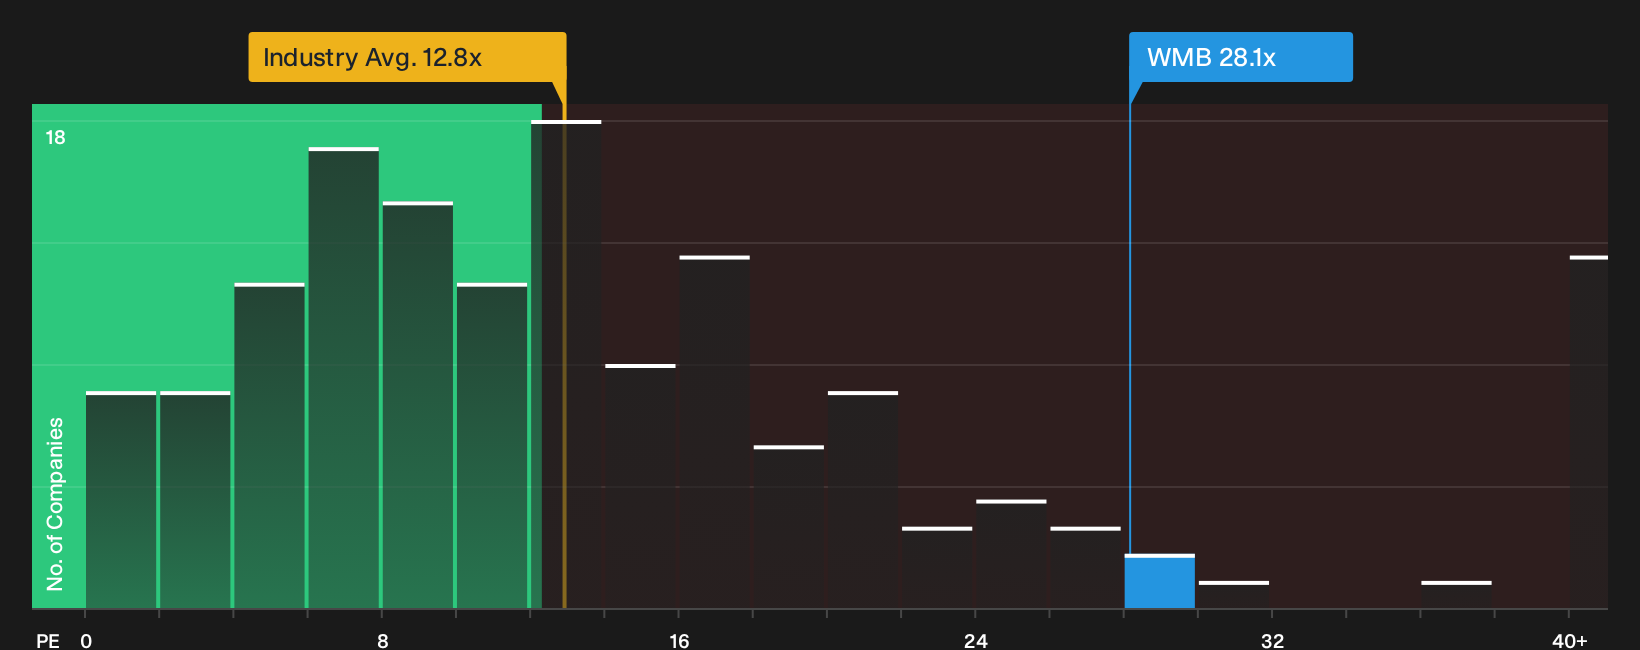
The P/E ratio is a useful yardstick for Williams Companies because earnings remain the main anchor for how investors think about this type of fee based infrastructure business. At the current share price, Williams Companies trades on a P/E of 28.1x, which is higher than both the Oil and Gas industry average of 12.8x and the broader peer average of 14.8x.
The fair multiple implied by the tailored model that factors in Williams Companies' growth profile, profitability, scale and risk sits slightly below the current P/E. As a result, the shares screen only modestly above what that framework would suggest. That leaves the burden on future earnings delivery to keep supporting a valuation that already carries a premium to sector norms and to the peer set on this metric. Explore the numbers behind Williams Companies's P/E valuation.
The Williams Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Williams Companies pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the shares to be worth materially more or less than today. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of Williams Companies' story appears to be playing out on the Community page.
One of the top community narratives on Williams Companies: 17% undervalued
"Analysts have lifted the Williams Companies fair value estimate from $83.55 to $85.25, pointing to higher modeled revenue growth and profit margins..."
Discover why this Narrative puts Williams Companies at 17% undervalued.
The Williams Companies story also hinges on who is steering it
Price and earnings only tell part of the Williams Companies puzzle, because the track record, decisions and pay structure of the leadership team can heavily shape how those numbers evolve over time. See who runs Williams Companies and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com