
Flowserve (FLS) Names A New CFO, Is The Stock Still Cheap?
Flowserve (FLS) just reshuffled its senior finance bench. Longtime finance executive Brian Ezzell will take over as Chief Financial Officer on October 1, 2026, following Amy Schwetz’s planned departure.
Recent trading has been choppy for Flowserve, with the share price down 1.48% over the last day and 5.61% over 30 days. At the same time, the 1-year total shareholder return of 43.95% and 5-year total shareholder return of 141.56% point to momentum that has been building over time.
Scan across industrial flow and infrastructure plays with similar leadership storylines by checking our curated list of list of solid balance sheet and fundamentals (24 results), which might sit in a comparable risk bucket to Flowserve.
Flowserve’s recent pullback sits awkwardly next to its strong multi year shareholder returns and expanding earnings, which raises a simple question. Are investors reassessing the business, or just adjusting sentiment around the new finance leadership before price catches up with fundamentals?
Most Popular Narrative: 16% Undervalued
Flowserve’s most followed valuation narrative anchors on a fair value of $90, which sits above the last close at $76.04 and frames the CFO change against a broader earnings and cash flow story that investors are watching closely.
The company's disciplined capital allocation strategy, including potential share repurchases enabled by the recent $266M break fee, targeted M&A aligned with decarbonization and digitalization, and ongoing investments in R&D for differentiated, high-growth products, are positioned to accelerate earnings per share growth and support long-term shareholder value creation.
See why 34 investors see Flowserve as 16% undervalued.
Result: Fair Value of $90 (UNDERVALUED)
Still, the Flowserve narrative can be knocked off course if activist pressure around execution gains traction, or if integration issues in the Flow Control Division drag on margins.
Find out about the key risks to this Flowserve narrative.
Another View On Flowserve’s Valuation
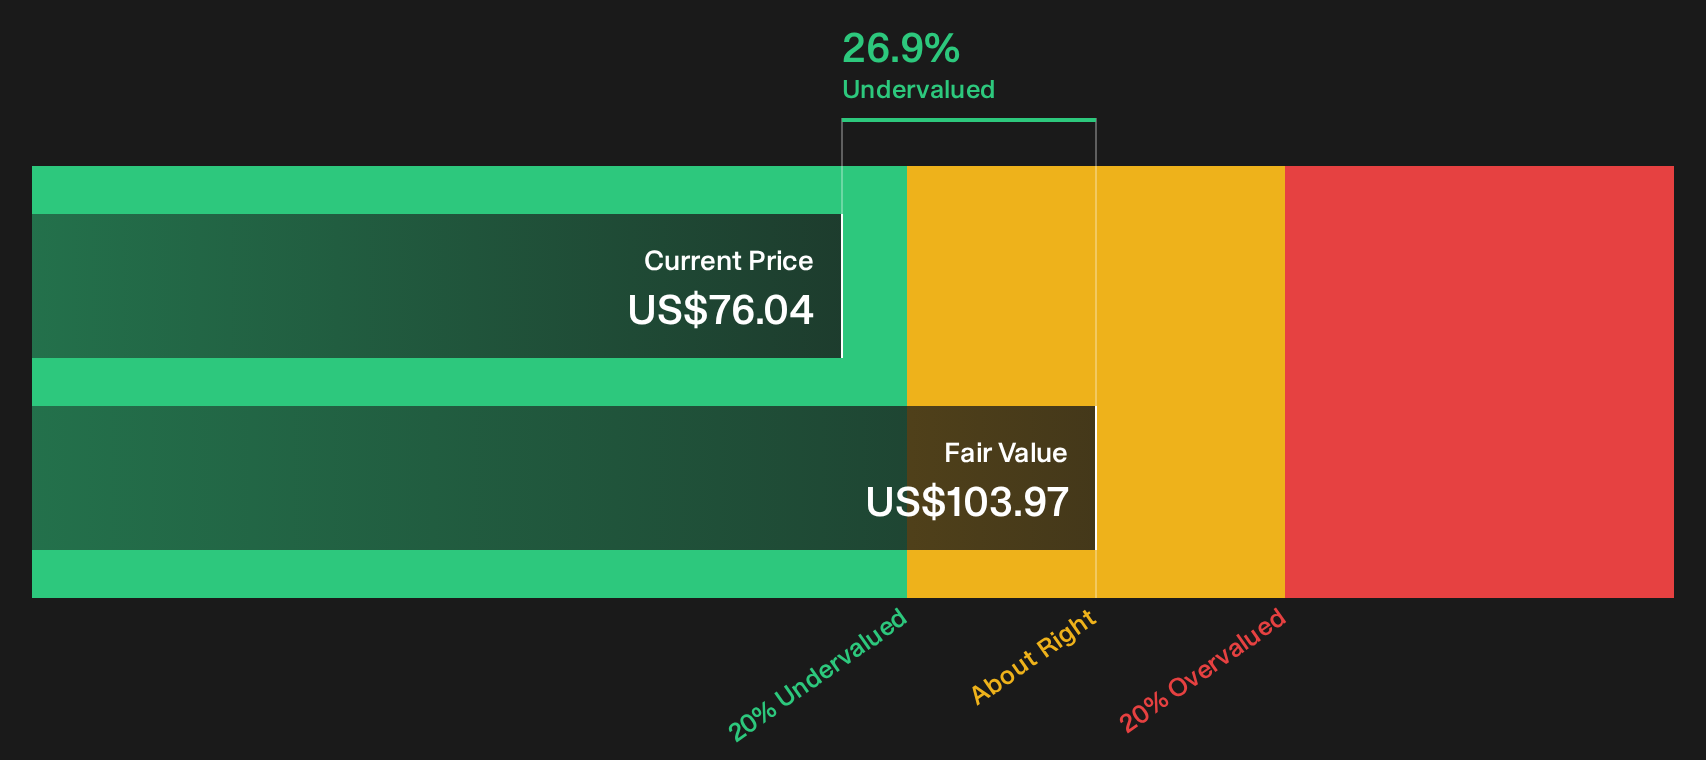
Flowserve screens as undervalued on the SWS DCF model, with a fair value estimate of $103.97 against the current $76.04 share price. That points to roughly 26.9% upside potential versus this cash flow view, even though the stock trades on a 26x P/E today. Which lens do you give more weight to?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Flowserve so far, so consider moving quickly to review the data, weigh the concerns and positives, and decide where you sit after reading the 3 key rewards and 2 important warning signs.
Looking for more Flowserve style investment ideas?
If Flowserve has you thinking harder about quality and valuation, do not stop here. Use the Simply Wall Street Screener to spot opportunities before others do.
- Hunt for mispriced quality by scanning our broader universe of potentially underappreciated companies through the 30 high quality undervalued stocks.
- Prioritize stability and sleep better at night by focusing on financially resilient businesses surfaced via the 30 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking smaller, overlooked candidates with strong fundamentals found in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com