
How Investors May Respond To Zuger Kantonalbank (SWX:ZUGER) CIO Appointment
- Zuger Kantonalbank appointed long-serving investment specialist Alexander Hunziker as Chief Investment Officer on 18 September 2026, promoting him from Deputy CIO after his leadership of the Fixed Income & Multi Asset portfolio management team within Wealth Management.
- The bank is deepening its investment focus by elevating an internal capital markets expert with Swiss National Bank and Credit Suisse experience. This underscores an emphasis on disciplined investment processes, governance and product design.
- The discussion will next explore how Zuger Kantonalbank's investment narrative could be influenced by Alexander Hunziker's promotion to Chief Investment Officer.
Scan how Zuger Kantonalbank’s CIO reshuffle compares with other institutions quietly tightening their investment process by filtering for 227 resilient stocks with low risk scores aligned with disciplined capital allocation and risk control.
What Is Zuger Kantonalbank's Investment Narrative?
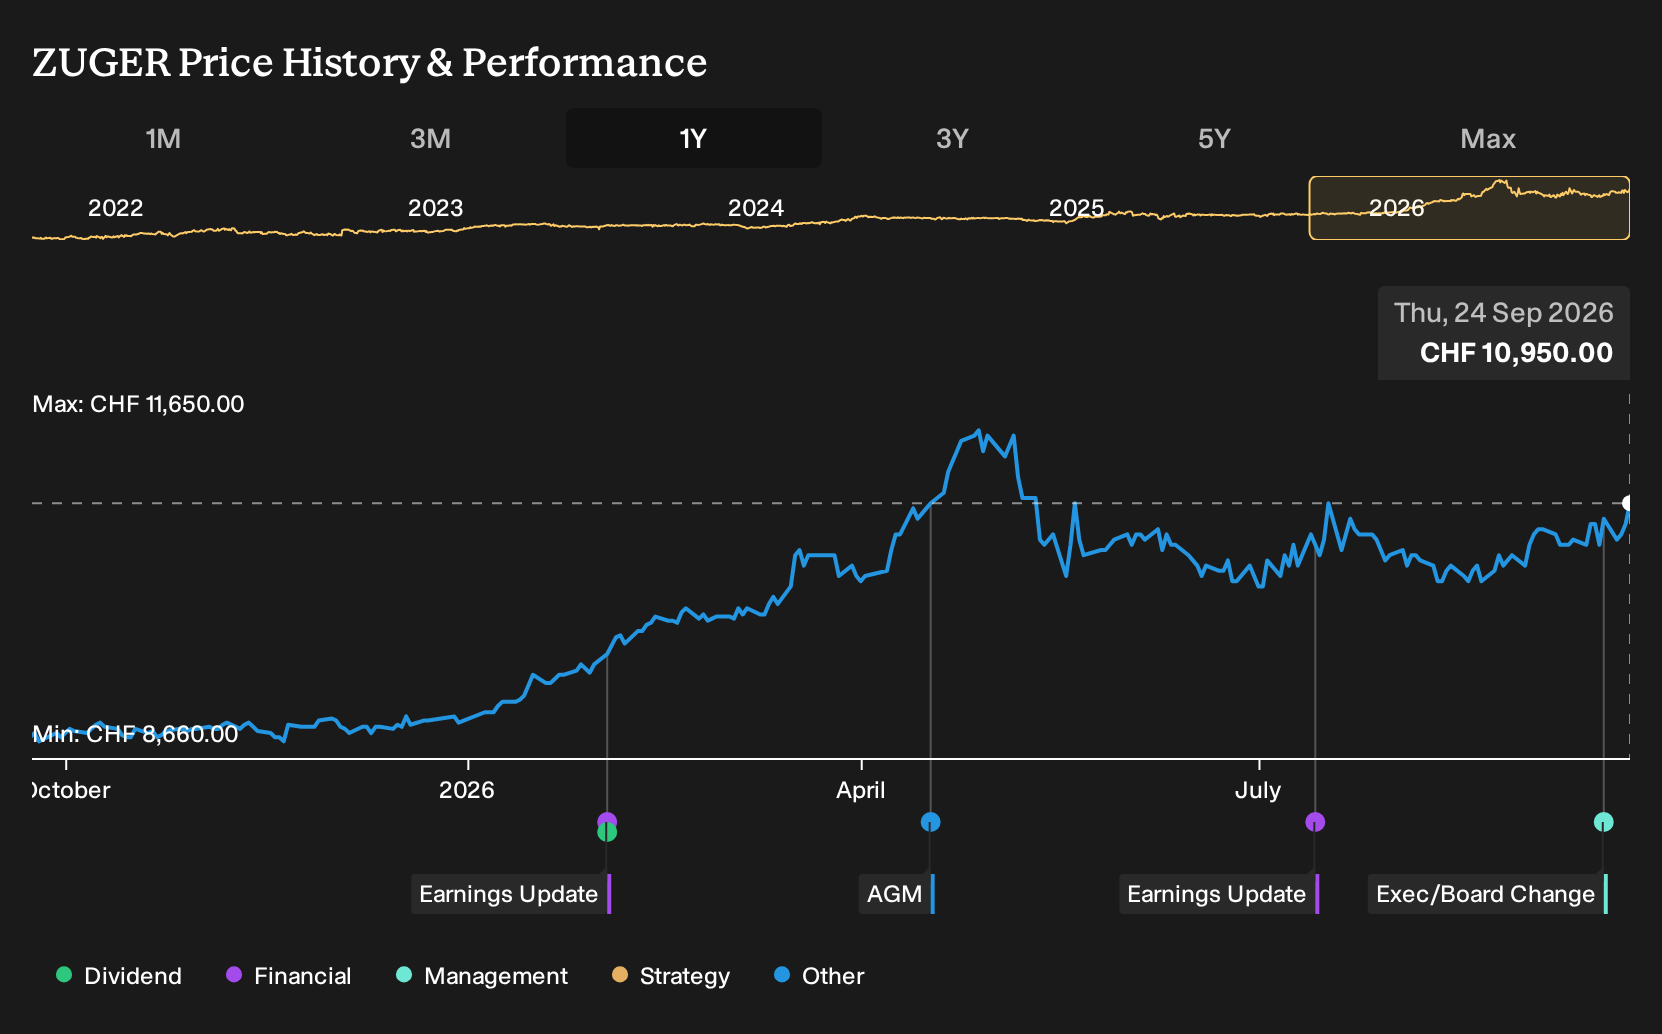
To own Zuger Kantonalbank, you need to be comfortable with a fairly traditional regional lender that leans heavily on steady fee income, disciplined risk culture and a long operating history in Zug. The stock has already delivered strong multi year total returns and trades on a P/E of 23.9x with a 2.1% dividend yield, so you are effectively paying up for stability, perceived quality of earnings and a focused Swiss footprint rather than a growth story.
The fresh piece today is the CIO handover to Alexander Hunziker, which speaks more to execution in the investment business than to sudden swings in profit. His background in fixed income, multi asset portfolios and central banking fits a bank that wants tight governance over its investment products and risk, especially with a low bad loan allowance of 66%. In the near term, the key questions are whether this continuity in the Investment Office supports stable fee income without adding risk, and how that squares with a relatively rich valuation and recent share price gains.
That said, there is a less comfortable angle to this story once you consider how that low bad loan allowance interacts with...
There's only one way to know the right time to buy, sell or hold Zuger Kantonalbank. Head to Simply Wall St's company report for the latest analysis of Zuger Kantonalbank's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zuger Kantonalbank research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zuger Kantonalbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zuger Kantonalbank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Zuger Kantonalbank?
Once you have a view on Zuger Kantonalbank, it can help to compare that thesis with other businesses that have very different drivers, risk profiles and income characteristics. The Simply Wall St Screener lets you scan across markets quickly so you can test your thinking against a wider opportunity set rather than anchoring on a single regional lender.
- If you want income to do more of the heavy lifting in your portfolio, consider high payout candidates by reviewing 159 dividend fortresses that combine yield with robust fundamentals.
- If capital preservation and resilience matter most to you, stress test your ideas against a list of solid balance sheet and fundamentals (202 results) and compare how they stack up on debt, cash, and interest coverage.
- If you are hunting for under followed stories with cleaner financials, widen your search to a 618 high quality undiscovered gems that might complement a more established position like Zuger Kantonalbank.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com