
How Investors Are Reacting To Panasonic Holdings (TSE:6752) Cash Dividend Declared
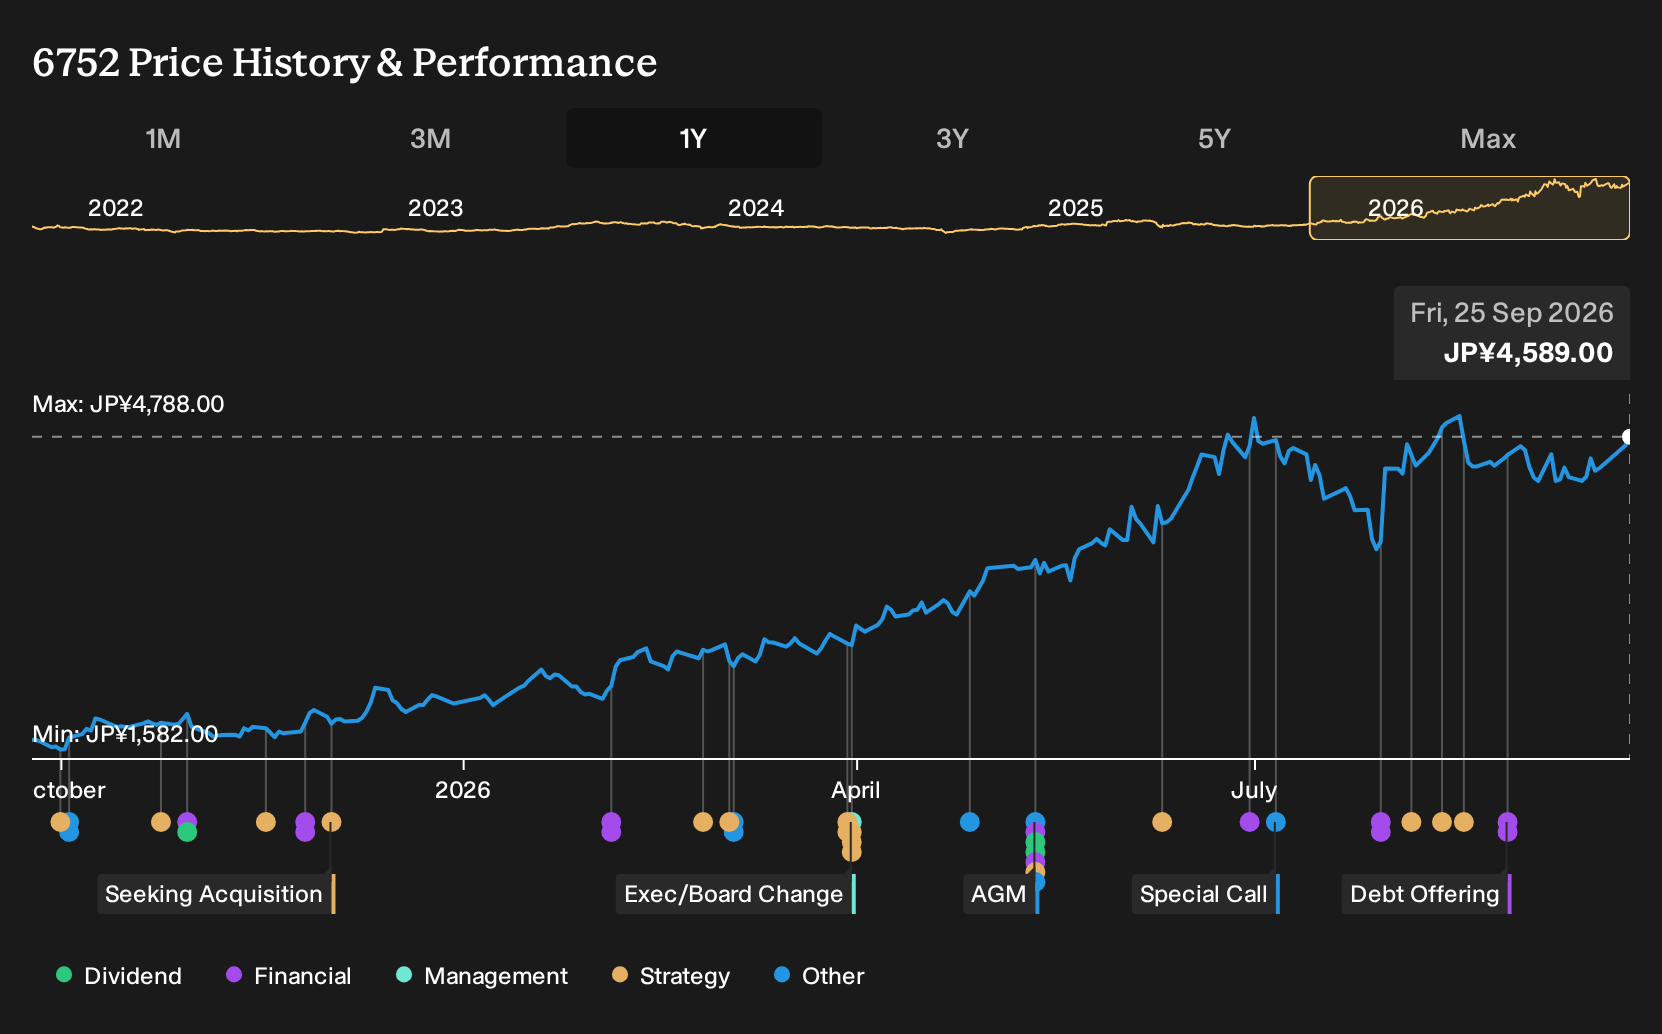
- Panasonic Holdings Corporation has announced a cash dividend of JPY 27.00 per share, with the ex dividend date set for 29 September 2026. This move reinforces its current capital return schedule for shareholders.
- The dividend decision highlights how Panasonic Holdings is balancing cash returns with ongoing investment demands across batteries, appliances, and broader electrical equipment operations.
- We will now look at how Panasonic Holdings' investment narrative could be influenced by this JPY 27.00 cash dividend announcement.
Scan opportunities beyond Panasonic Holdings by comparing this dividend move with curated 15 dividend fortresses that also prioritise shareholder cash returns.
Panasonic Holdings Investment Narrative Recap
For Panasonic Holdings, the core belief is that its energy storage, EV battery operations, and broader appliance and electrical equipment lines can produce steadier earnings over time despite cycles in EV and consumer demand. The JPY 27.00 dividend fits into that story as a capital return funded by a diversified group structure. It does not materially change the immediate business outlook.
The near term swing factor still sits in the North American battery build out and related demand uncertainty, especially with policy shifts and delayed factory ramp ups. The biggest risk remains execution on restructuring and portfolio clean up while margins sit at 3.1%, below last year, and one off items cloud recent profit quality.
Given the lack of other fresh corporate announcements around this dividend, the payout itself becomes the most relevant signal to focus on. It follows a period in which earnings were affected by a large one off loss of ¥244.0b, alongside a move in net profit margins from 4.5% to 3.1%. Against that backdrop, recurring cash distribution draws attention to underlying cash generation and balance sheet flexibility.
For you as a shareholder or potential investor, the key question is whether Panasonic Holdings can turn its expected 21.9% earnings growth per year into cleaner, less volatile profits while dealing with EV demand risks, tariffs, and restructuring delays. The dividend does not resolve those issues, but it offers a concrete data point on how management is currently weighing investment needs against returning cash.
Panasonic Holdings' narrative projects ¥8,901.1b revenue and ¥695.9b earnings by 2029. This assumes 2.9% yearly revenue growth and an earnings increase of about ¥442.7b from ¥253.2b today.
Uncover why Panasonic Holdings' fair value signals a 4% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view around Panasonic Holdings focuses less on EV uncertainty and more on bullish revenue potential from AI driven energy storage. The most optimistic analysts were already modeling ¥9,534.9b in 2029 revenue and ¥896.1b in earnings before this JPY 27.00 dividend news, so their narrative could shift further if they see the payout as confidence in cash generation.
Explore 3 other Panasonic Holdings fair value estimates, including one that indicates potential upside of up to 20% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Panasonic Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Panasonic Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Panasonic Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Panasonic Holdings?
If this Panasonic Holdings dividend update has sharpened your thinking, it could be a good moment to widen the lens and line up a few alternatives using the Simply Wall St Screener.
- If you prefer potential bargains with strong fundamentals and room for a re rating, then scan through 18 high quality undervalued stocks that fit those filters.
- If balance sheet strength matters most for your peace of mind, focus on companies in our list of solid balance sheet and fundamentals (22 results) and see which ones match your risk tolerance.
- If you want something a bit less crowded by attention, then shortlist opportunities from our 74 high quality undiscovered gems and compare their stories against Panasonic Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com