
Chaparral Aircraft Order Could Be A Big Deal For Bristow Group Stock (VTOL)
- Elroy Air announced that Bristow Group expanded its early delivery reservations for the Chaparral autonomous cargo aircraft, adding 10 more early positions for a total of 15 within a broader pre-order framework of up to 100 units.
- This deeper commitment to Chaparral, which is designed to move more than 500 pounds of cargo up to 450 miles without runways or charging infrastructure, points to Bristow Group testing lower-footprint logistics options for remote operations where traditional helicopter support can be costly or constrained by facilities.
- We will look at how Bristow Group's investment narrative is affected by its larger Chaparral autonomous cargo aircraft reservation commitment.
Scan other logistics and VTOL plays that are moving in the same direction as Bristow Group by focusing on our hand picked 93 robotics and automation stocks for this theme.
Bristow Group Investment Narrative Recap
To own Bristow Group, you need to be comfortable with a helicopter and government services operator that is trying to layer in next generation aircraft while managing heavy capital needs, supply chain friction and exposure to oil and gas activity. The Chaparral reservation expansion fits that story, but does not change the near term focus on contract execution and utilization.
The key short term swing factor remains how efficiently Bristow transitions and ramps large search and rescue and offshore contracts without letting training, repair and subcontractor costs eat into margins. The biggest near term risk is that high capex and elevated operating expenses persist, which could strain cash generation even if demand holds up.
The fresh Chaparral news ties most directly to Bristow Group's broader push into next generation vertical lift platforms, including eVTOL initiatives referenced in its partnerships and advanced air mobility work. The Elroy Air deal adds an autonomous cargo angle, which sits alongside those projects rather than replacing the core helicopter fleet.
For catalysts, the meaningful drivers still sit in ramping long term government search and rescue agreements in Ireland and the UK and in deploying aircraft into high utilization offshore routes in places like Africa and Brazil. Chaparral reservations reinforce that Bristow is actively exploring lower footprint logistics options, but the operational and financial impact depends on successful certification, production and integration over time.
Bristow Group's analyst narrative points to revenue of US$1.9b and earnings of US$229.0 million by 2029, based on an assumed 6.8% yearly revenue growth rate. That path implies earnings rising by about US$114.2 million from current earnings of US$114.8 million to the 2029 consensus level.
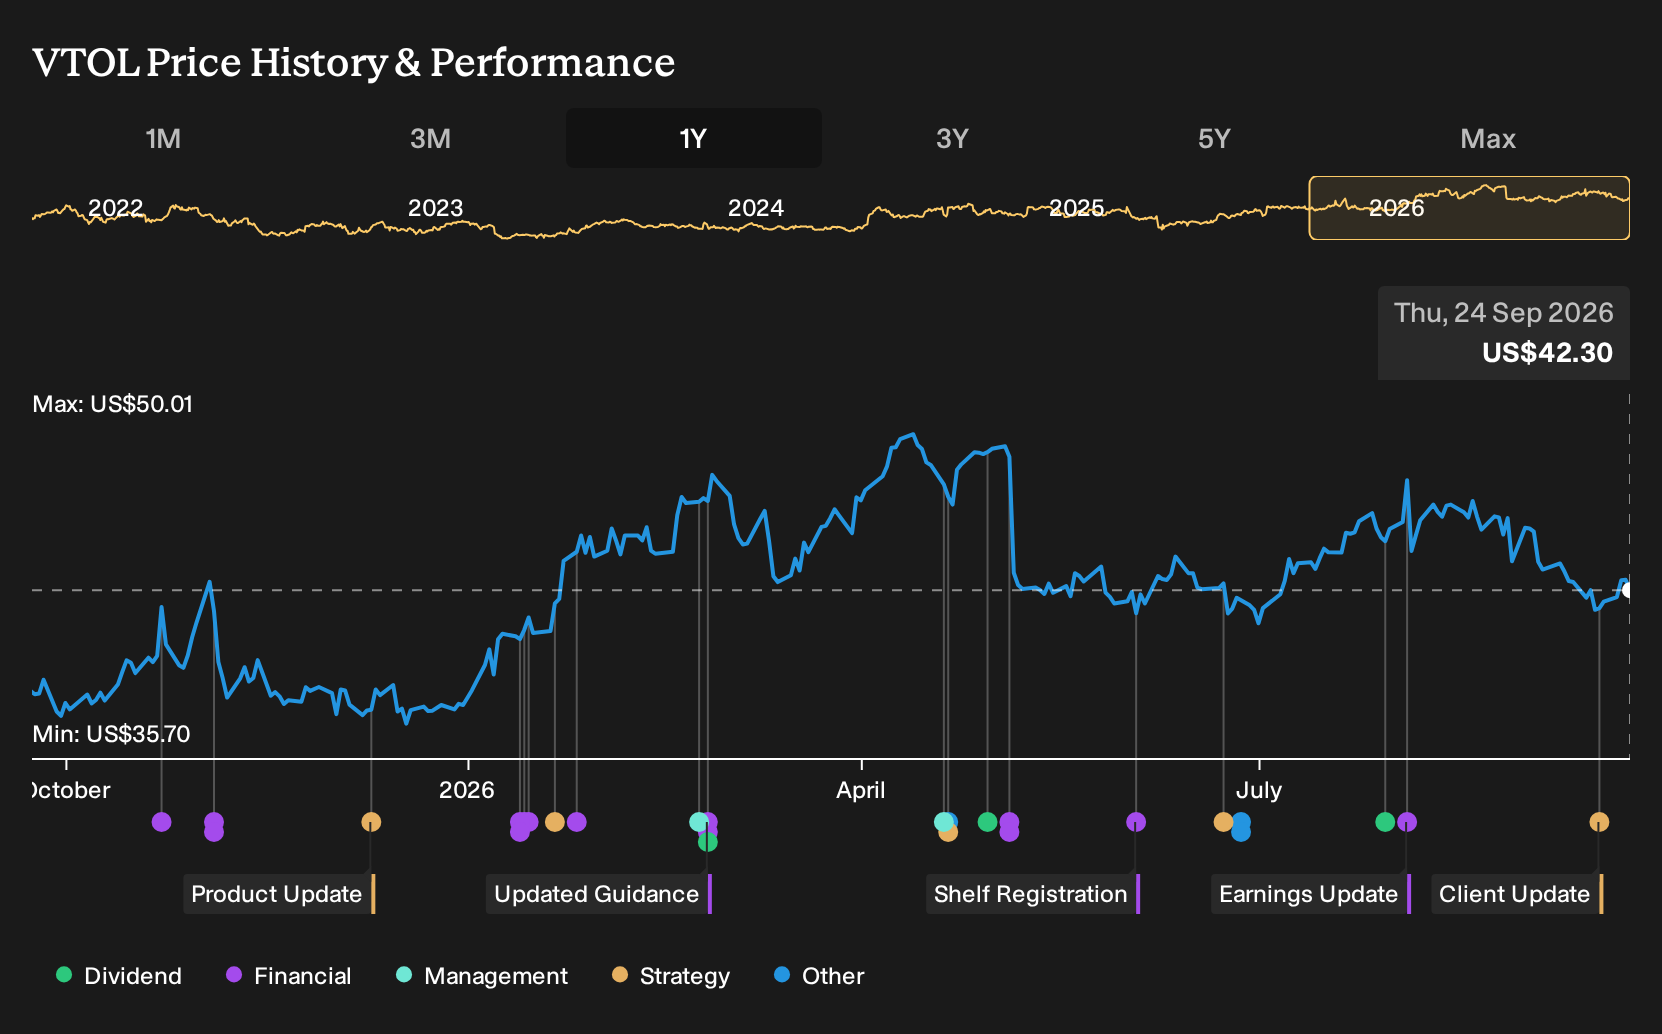
Uncover why Bristow Group's fair value indicates a 47% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate angle on Bristow Group leans hard into margin risk. The most cautious analysts assume earnings reach about US$207.1 million on roughly US$1.9b of revenue by 2029, which is below the consensus earnings path. Those projections already predate the Chaparral news, so your view may shift as assumptions get refreshed.
Explore 2 other Bristow Group fair value estimates, including one that suggests it could be worth just $62.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bristow Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bristow Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bristow Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bristow Group?
If you want to cross check the Bristow Group thesis against other opportunities, the Simply Wall St Screener can help you line up different types of stocks side by side and pressure test where you want to focus next.
- For investors who care most about protection on the downside, scan a curated set of companies that screen as resilient using our 30 resilient stocks with low risk scores.
- If income is your priority, compare businesses offering higher yields and assess how robust those payouts look through our 8 dividend fortresses.
- To widen your watchlist with lesser known opportunities, surface underfollowed companies with solid fundamentals using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com