
What CNX Resources Stock's CFO Change Means For Shareholders
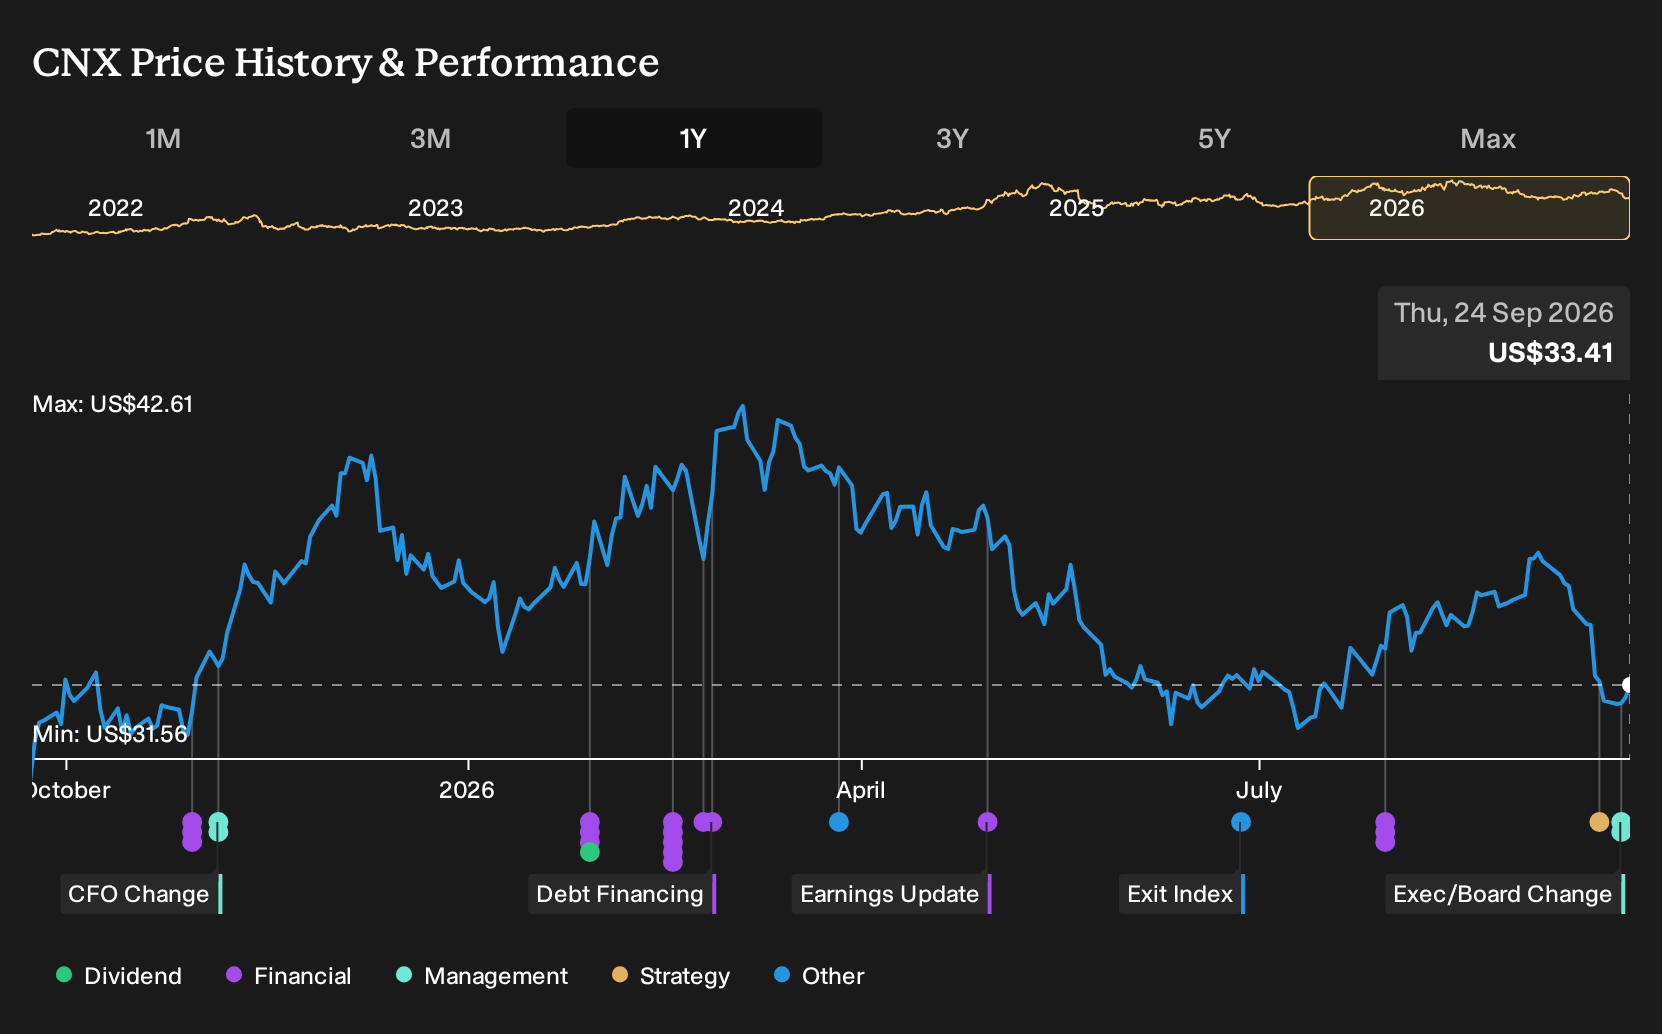
- CNX Resources reshaped its finance leadership after September 2026, naming long-time insider Ravi Srivastava as CFO and principal financial officer and elevating Melissa Long to principal accounting officer, while former CFO Everett Good shifts into a short-term consulting role.
- The expanded Radical Transparency program, with continuous third-party radiation monitoring and real-time public disclosure, ties CNX Resources' environmental commitments directly to day-to-day field operations and regulatory scrutiny.
- We will now look at how CNX Resources' refreshed finance leadership and radiation monitoring push could influence the broader investment narrative.
Scan how CNX Resources fits into the wider gas and infrastructure story by reviewing a hand-picked 39 power grid technology and infrastructure stocks positioned for the next leg of energy system upgrades.
CNX Resources Investment Narrative Recap
To own CNX Resources, you need to be comfortable with a concentrated Appalachian gas producer that leans on capital discipline, environmental attribute revenues and efficiency in Marcellus and Utica to support cash generation while headline earnings are forecast to decline over the next few years. The near term swing factor remains how smoothly CNX manages production lulls from its one rig program and sequencing of new wells.
The biggest current risk is that weaker in basin demand or regulatory outcomes around credits like 45Z and RMG reduce expected cash flow from environmental attributes. The CFO transition to Ravi Srivastava and promotion of Melissa Long look operationally relevant but not obviously transformative for these core drivers, unless execution around capital allocation or hedging meaningfully changes.
The most relevant announcement alongside the leadership changes is CNX Resources expanding its Radical Transparency program to continuous radiation monitoring and broader public disclosure of waste surveys. This sits directly on the operational and regulatory front line where natural gas producers face scrutiny over environmental performance and data quality, with CNX opting into third party monitored, real time sharing of radiation readings.
For catalysts, that monitoring framework could matter in two ways. It may help CNX keep projects moving through permitting and community review, which is important when the growth story leans on in basin demand and potential premium pricing for lower carbon or “attribute rich” gas products. It also adds incremental compliance and reputational risk if public data reveal issues or if critics successfully argue that voluntary monitoring is not sufficient, which investors need to weigh against the potential upside from differentiated environmental positioning.
CNX Resources Earnings And Revenue Set Up
Analysts outline a CNX Resources path that leans on modest top line expansion and a compressed profit pool. The sell side assumes revenue grows at about 1.3% a year over the next three years, while earnings move from US$1.2b today to US$499.8m by 2029 as margins shift from 52.7% to 21.5%.
CNX Resources' narrative projects US$2.3b revenue and US$499.8m earnings by 2029. That profile rests on 1.3% yearly revenue growth and an earnings change of roughly US$700m from US$1.2b today.
Those estimates also incorporate a higher valuation multiple on a smaller earnings base. The consensus view assumes CNX could trade on a P/E of 13.1x on 2029 earnings, compared with about 4.2x on current earnings, while the number of shares on issue is expected to stay broadly flat. In simple terms, the story that underpins the current analyst framework is less profit in absolute dollars, paired with a higher price tag on each dollar of that profit.
Forecasts such as US$2.3b of revenue and just under US$500m of profit depend on the margin reset and the shift toward environmental attribute income aligning with the Street view. Smaller or more delayed credit receipts from programs such as 45Z, or a different outcome from markets for renewable natural gas and related products, would leave the earnings bridge from today to 2029 looking very different.
Uncover how CNX Resources' fair value indicates a 13% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Some of the most optimistic analysts see CNX Resources' environmental credit business as the real swing factor. Before this CFO and radiation monitoring news, that bullish group was penciling in about US$2.7b of revenue and US$894.8m of earnings by 2029. You can compare that to the consensus US$2.3b and US$499.8m and decide which storyline feels closer to your view, knowing both were written before these announcements and may shift as the new data and leadership are incorporated.
Explore 2 other CNX Resources fair value estimates, including one that suggests as much as 269% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CNX Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CNX Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNX Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond CNX Resources?
If CNX Resources has sharpened your interest in where to allocate capital next, use the Simply Wall St Screener to line up a broader watchlist that matches your risk profile and income goals.
- If capital preservation sits high on your list, start with a set of 30 resilient stocks with low risk scores that may better fit a steadier approach to market swings.
- For investors focused on strong finances, filter for companies with robust balance sheets and healthy fundamentals using a list of solid balance sheet and fundamentals (24 results) to stress test your next ideas.
- If you prefer to hunt for overlooked opportunities, sift through a curated 16 high quality undiscovered gems where quality metrics point to businesses the wider market may not be watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com