
Could Sakarya Contract Extension Change The Bull Case For Subsea 7 Stock?
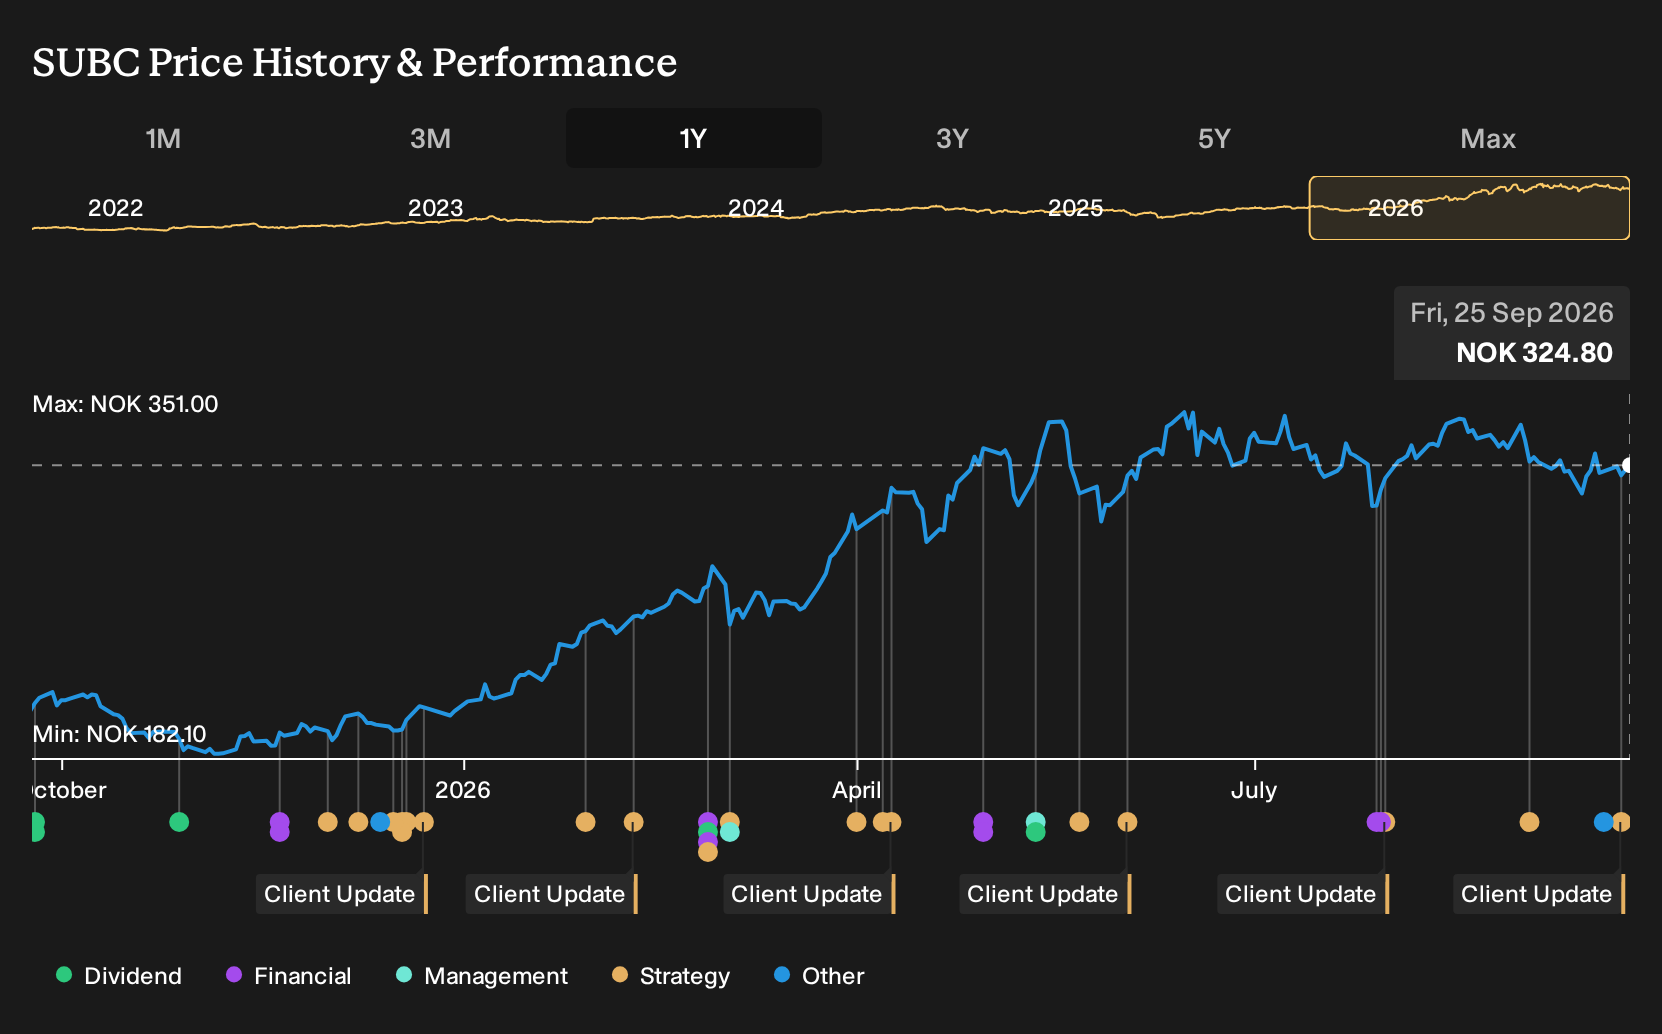
- Subsea 7 S.A. reported that Turkish Petroleum Offshore Technology Center awarded a sizeable Sakarya Phase 3 contract extension in the Black Sea, worth between US$50 million and US$150 million, alongside its recent inclusion in the FTSE All-World Index and new long term incentive share awards to senior management.
- The Sakarya extension concentrates new work in Subsea 7’s Istanbul office, which reinforces local execution capacity and adds medium term offshore workload visibility around the 2028 floating production unit commissioning.
- We now examine how Subsea 7’s investment narrative interacts with this sizeable Sakarya extension and the company’s growing project backlog.
Scan how Subsea 7’s Black Sea contract and index inclusion fit into the wider energy infrastructure story by reviewing the hand picked 39 power grid technology and infrastructure stocks now.
Subsea 7 Investment Narrative Recap
To own Subsea 7, you need to be comfortable with a project driven offshore contractor that leans on a large backlog, high vessel utilization, and disciplined bidding to support earnings. The core belief is that complex subsea work and selected renewables projects keep order intake healthy enough to justify ongoing capital spend and the proposed Saipem merger.
Right now the key near term swing factor is project execution and margin quality on the sizeable backlog, especially as competition in regions like Brazil can squeeze pricing. The Sakarya Phase 3 extension adds incremental visibility rather than a step change. It does not materially alter the biggest short term risk, which remains utilization and margin pressure if awards slow.
The Sakarya Phase 3 extension looks most relevant because it directly feeds into Subsea 7’s order book and workload planning. A US$50 million to US$150 million scope for towing, mooring and connection around the 2028 floating production unit fits the firm’s focus on technically demanding, long cycle projects that can support vessel activity over several years.
Work led from the Istanbul office ties into the broader narrative around operational depth and local execution as the business pursues larger, more complex developments and a potential Saipem combination. For you, the contract mainly reinforces existing catalysts around backlog and earnings quality, while the familiar risks around capital intensity, competition and project delivery remain in place.
Subsea 7's narrative projects US$7.9b revenue and US$779.2m earnings by 2029, based on analysts' assumption of 2.5% yearly revenue growth and an earnings increase of about US$286m from US$493.0m today.
Uncover why Subsea 7's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on backlog health and more on decarbonization risk. Under that lens, the lowest analysts saw Subsea 7’s revenue shrinking about 2.4% a year and earnings sliding from US$613.0m to US$477.3m by 2029. The takeaway is simple: opinions differ sharply, and this Sakarya news could yet reshape those narratives.
Explore 4 other Subsea 7 fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Subsea 7 research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Subsea 7. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Subsea 7's overall financial health at a glance.
Looking For More Ideas Beyond Subsea 7?
If this Subsea 7 update has sharpened your thinking about project driven businesses, it can help to widen the lens and compare it with other stocks that fit different risk and income profiles. The Simply Wall St Screener offers several curated sets you can use to pressure test your portfolio and spot opportunities that match your own criteria.
- For investors who care most about quality at a reasonable entry point, scan a carefully filtered group of companies that appear attractively priced on fundamentals through the 180 high quality undervalued stocks.
- If balance sheet strength and resilience matter more to you than headline growth stories, focus on businesses with stronger financial footing by reviewing the list of solid balance sheet and fundamentals (202 results).
- Those hunting for potential income ideas can zero in on higher yielding opportunities by checking the 158 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com