
How Return To Profit Will Impact AnaptysBio (ANAB) Investors
- AnaptysBio reported fourth quarter 2026 net income of US$183.88 million versus a net loss a year earlier, with basic earnings per share from continuing operations at US$6.06 and diluted earnings per share at US$4.93, and six month net income at US$131 million.
- The shift from loss per share in the prior year to basic earnings per share of US$6.28 in the quarter and US$4.52 over six months highlights the impact of earnings from continuing operations on AnaptysBio’s overall profit profile.
- This raises the question of how AnaptysBio’s move to profitability and higher earnings per share may influence the broader investment narrative.
What Is AnaptysBio's Investment Narrative?
For AnaptysBio, the big picture is about whether you believe a royalty driven model on partnered drugs like Jemperli and Quimilza can keep translating into real cash earnings rather than just accounting profit. The sharp swing to US$183.88 million in fourth quarter net income and US$131 million over six months shows what a fully ramped licensing portfolio can look like on the income statement. The debate is how repeatable those figures are and how much is tied to one off or non cash items flagged in prior risk work.
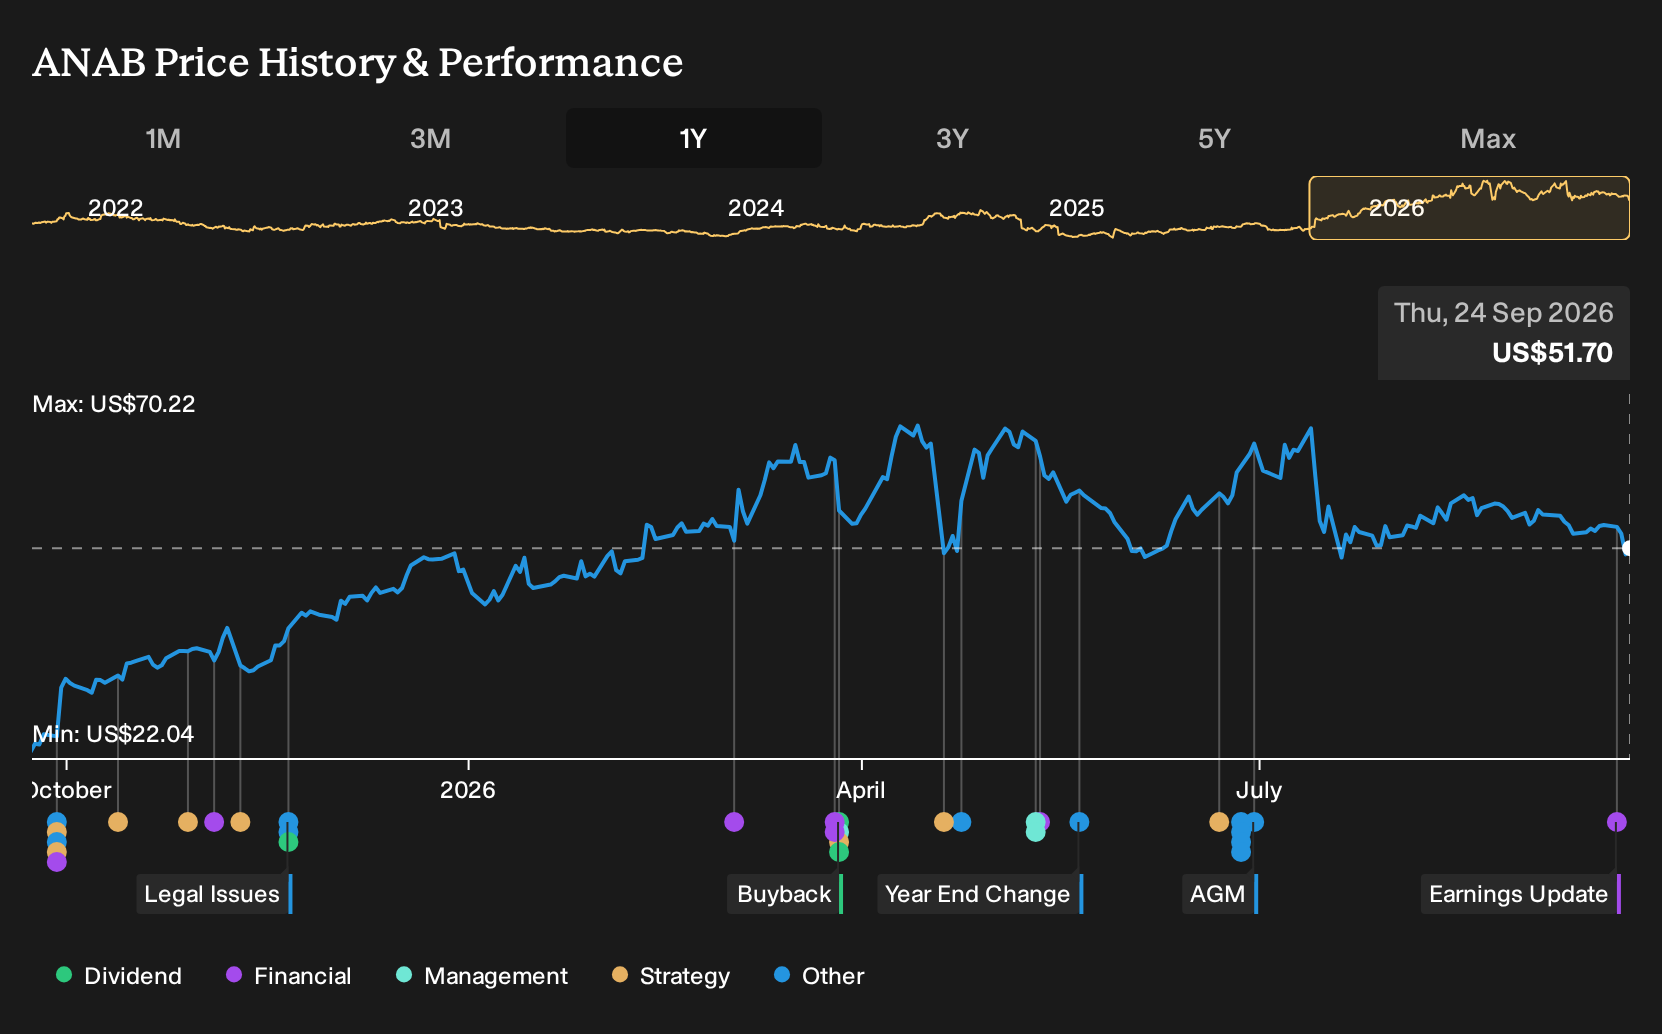
In the short term, the latest results feed straight into the key catalysts investors watch. That includes how sustainable current royalty levels are, whether any milestone payments recur and how much debt service pressure eases if earnings stay elevated. The recent move in the share price, which is up strongly over one year but has fallen over the past 90 days, suggests the market is still sorting out how to price that earnings mix next to forecasts that point to revenue growth but softer profit expectations. Execution on collaborations and capital discipline matter more than ever with interest costs not comfortably covered by earnings, especially if future quarters look less dramatic than this headline print.
Yet there is a lingering tension that sits between this profitability story and one specific pressure point that only really becomes clear when you look at ...
There's only one way to know the right time to buy, sell or hold AnaptysBio. Head to Simply Wall St's company report for the latest analysis of AnaptysBio's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from US$88.50 to about US$1,280.76, an extremely wide spread that shows how differently retail investors are modelling AnaptysBio. Those figures were set before the June 2026 earnings swing to profitability, so you are seeing sentiment that has not processed that profit shift yet.
Explore 2 other AnaptysBio fair value estimates, including one that suggests it could be worth just $88.50!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AnaptysBio research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AnaptysBio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AnaptysBio's overall financial health at a glance.
Looking For More Investment Ideas Beyond AnaptysBio?
If AnaptysBio has sharpened your focus on earnings inflection points, it can be useful to widen the lens and line up a few other candidates for your watchlist using the Simply Wall St Screener.
- If you want businesses that the data suggests combine quality with a gap between price and fundamentals, take a look at 30 high quality undervalued stocks that might warrant a closer review.
- If capital strength matters most to you, scan our list of solid balance sheet and fundamentals (24 results) to find companies where liquidity and leverage metrics look more resilient.
- If sleeping well at night ranks above chasing every price swing, filter for 30 resilient stocks with low risk scores that align better with a more cautious approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com