
What First Merchants (FRME)'s $100 Million Debt Raise Means For Shareholders
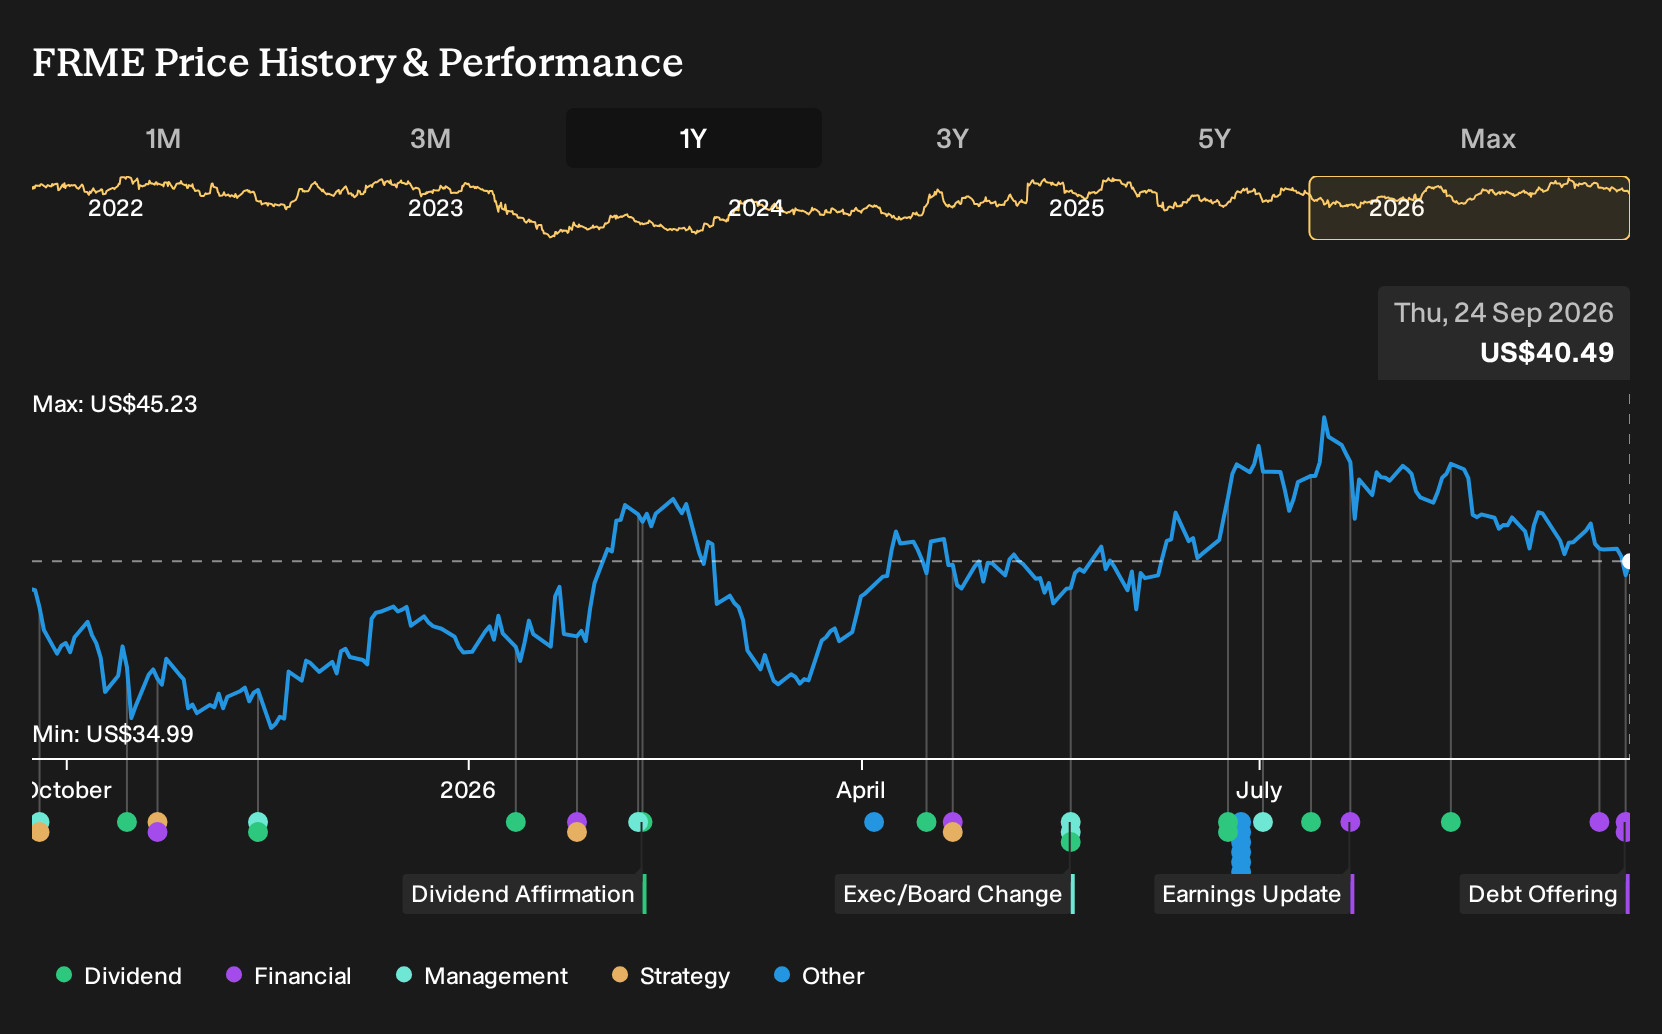
- First Merchants Corporation recently completed and announced a $100 million fixed to floating rate subordinated, unsecured note offering due October 1, 2036, with callable, variable rate features and a 1.25% discount to investors.
- This fresh layer of subordinated debt adds a new funding source for First Merchants Corporation, which may influence its future capital mix, interest expense profile, and flexibility in managing regulatory capital requirements.
- This article reviews how First Merchants Corporation's investment narrative is affected by this new $100 million fixed to floating debt raise.
Scan how First Merchants is refinancing with subordinated notes, then compare it with banks using similar funding playbooks through our hand picked list of solid balance sheet and fundamentals (24 results)
What Is First Merchants' Investment Narrative?
To own First Merchants, you need to believe in a fairly straightforward story. This is a regional bank with a community banking base, a full suite of commercial and consumer products, and a management team that has kept earnings quality high while still paying a 3.66% dividend. Earnings are forecast to grow 23.1% a year, which, if achieved, would sit against a current P/E of 13.8x that is below an estimated fair P/E of 15.5x.
The new $100 million fixed to floating subordinated notes and the recent omnibus shelf registration both point to a focus on flexible funding rather than a radical shift in the business model. Subordinated, unsecured debt can support regulatory capital and may inch up interest expense, but it does not rewrite the near term thesis around loan demand, deposit pricing, or execution in its Indiana, Ohio, and Michigan footprint.
Even so, one structural issue around how First Merchants earns that future profit growth could turn into a much bigger conversation if ...
There's only one way to know the right time to buy, sell or hold First Merchants. Head to Simply Wall St's company report for the latest analysis of First Merchants's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Merchants research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for First Merchants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Merchants' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Merchants?
Once you have a view on First Merchants, it can help to cross check that thinking against other opportunities using the Simply Wall St Screener. That way you can see how this regional bank compares with very different ways of putting capital to work.
- If you want potential value with quality in mind, scan through 30 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- If income is your focus, line up First Merchants' yield against 8 dividend fortresses built around higher payout profiles and robust track records.
- If capital preservation matters most, stress test your watchlist by comparing it with 30 resilient stocks with low risk scores that score better on financial resilience and risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com