
Manchester United (MANU) Climbed, But What Is Driving Attention Now?
Manchester United (MANU) has swung into focus after reporting a larger fourth quarter net loss alongside fresh revenue guidance for fiscal 2027, leaving investors weighing record full year sales against ongoing UEFA-related income pressure.
Recent trading tells a mixed story for Manchester United. The share price has climbed 2.20% over the past day and 5.01% across the last week, yet remains down 12.27% over 30 days and 8.64% over 90 days. This pullback follows the record revenue headline, enlarged loss and fresh guidance. Even so, the share price is still up 32.70% year to date, and the 1 year total shareholder return of 38.22%, alongside a 5 year total shareholder return of 9.52%, suggests long term holders have seen moderate gains while short term momentum has recently faded on earnings related uncertainty.
Compare Manchester United's mixed momentum with a hand picked group of clubs and media businesses by scanning the 16 high quality undiscovered gems for ideas that are still flying under most radars.
Record revenue, alongside a deeper loss and a share price still up strongly this year, puts Manchester United in an awkward middle ground. Does that mix still justify taking on the risk at today’s valuation?
Most Popular Narrative: 11% Undervalued
On the most widely followed view, Manchester United carries a fair value of $23.65 against a last close of $20.94. This frames the current pullback as a potential discount rather than a verdict on the business. That narrative leans heavily on the idea that careful squad rebuilding and tighter transfer discipline can eventually turn today’s losses into healthier long term earnings power.
The planned midfield overhaul at Manchester United, including planned additions such as Carlos Baleba, Andrey Santos and Manu Kone, is intended to address structural weaknesses in the squad ahead of Champions League campaigns and could support future matchday and broadcasting revenue if performances stabilize.
The shift toward targeting players like Sander Berge and Joaquin Seys when higher priced options are deemed too expensive signals tighter discipline on transfer spending, which can help protect net margins and earnings over future windows.
See why 2 investors see Manchester United as 11% undervalued.
Result: Fair Value of $23.65 (UNDERVALUED)
Still, the Manchester United story can unravel quickly if high wage contracts remain hard to shift or key injuries continue to affect results on the pitch and related income.
Find out about the key risks to this Manchester United narrative.
Another View: Manchester United On Cash Flows
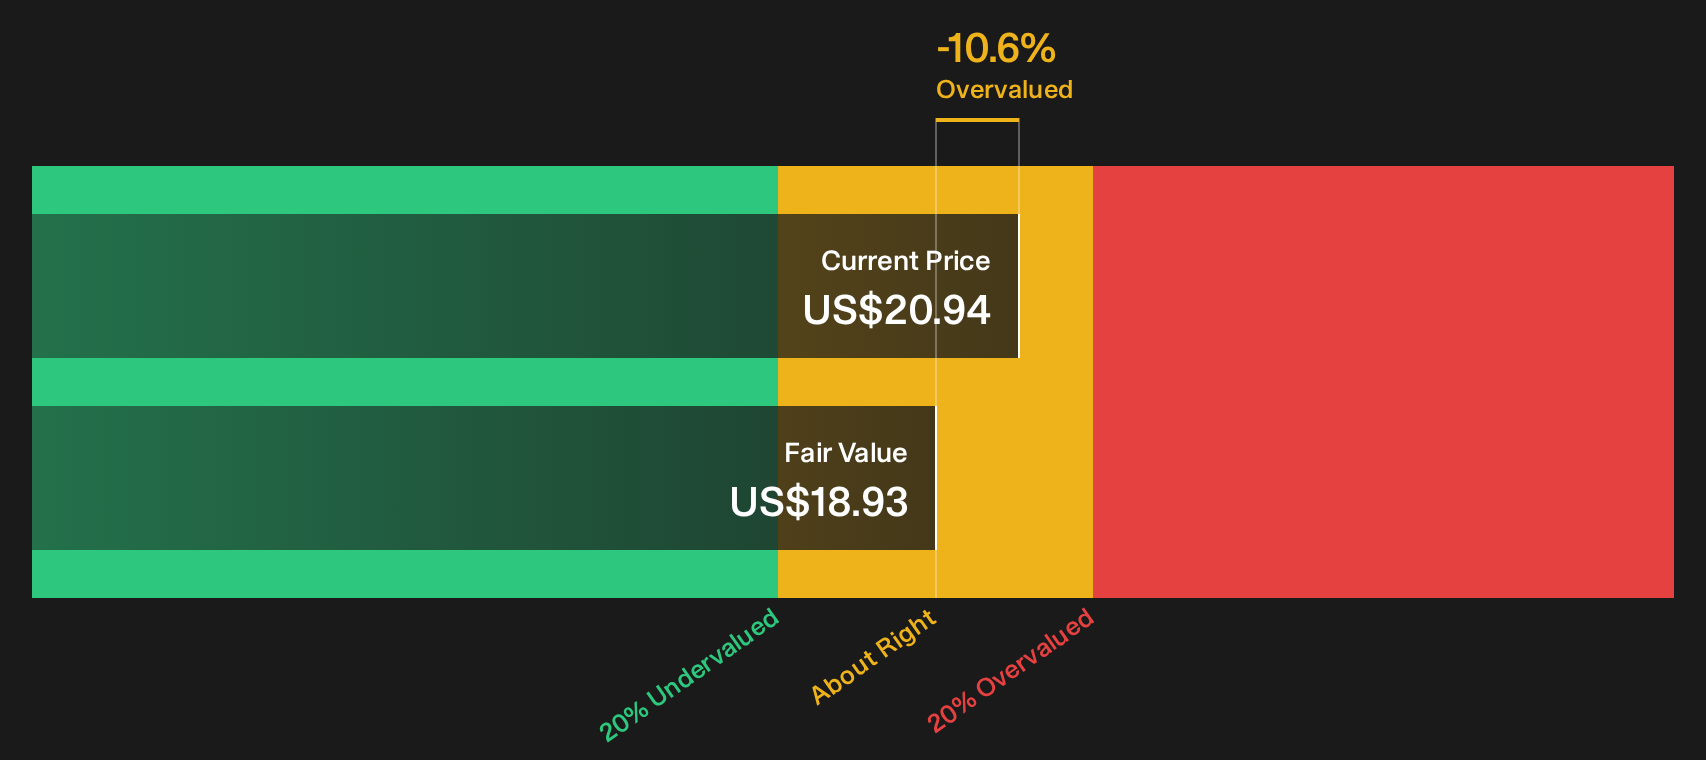
The analyst narrative leans on a fair value of $23.65 for Manchester United, yet Simply Wall St's DCF model points the other way. On that approach, the future cash flow value sits at $18.93 while the shares trade at $20.94, which implies the stock looks overvalued rather than discounted.
Both methods rest on long range assumptions about profitability that are far from settled. Which story do you trust more when the next few seasons on and off the pitch start to test those forecasts: the multiple-based optimism, or the cash flow caution signal?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Manchester United for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals run through the Manchester United story right now, so act promptly and review the data yourself, then weigh both sides before deciding how it stacks up against the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Manchester United?
If Manchester United has you rethinking where to put fresh capital, do not stop with a single ticker. Use the Simply Wall St screener to size up other options that better match your risk, income, and value priorities.
- Target income resilience by scanning companies that have paid-out heavy yields in the past with the help of the 8 dividend fortresses.
- Hunt for quality at a discount by lining up businesses with strong fundamentals against their implied worth using the 30 high quality undervalued stocks.
- Dial back risk by shortlisting financially robust businesses with cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com