
Railcar Orders Might Change The Case For Investing In Greenbrier Stock (GBX)
- Greenbrier Companies reported that it received orders for 3,400 new railcars worth about US$600 million in its fiscal fourth quarter ended 31 August 2026, spanning multiple car types and customers including Saudi Arabian government-owned SAR.
- The SAR contract extends a relationship dating back to 2015 and includes Greenbrier’s first intermodal units for this client. This highlights how export-oriented manufacturing in Mexico and U.S. steel sourcing feed into international freight and infrastructure projects.
- We will look at how Greenbrier Companies' investment narrative is influenced by securing 3,400 new railcar orders across diverse end markets.
Greenbrier Companies Investment Narrative Recap
To own Greenbrier Companies, you need to be comfortable with a cyclical manufacturer that leans on a sizeable order book, a leasing operation, and cost control to smooth a choppy railcar market. The 3,400 unit, US$600 million win supports that order visibility in the near term but does not remove exposure to softer demand, especially where European rationalization and lower profit margins are already in focus.
Right now, the key short term swing factor is how efficiently Greenbrier Companies turns its backlog into earnings while managing steel and other input costs in the face of trade and tariff risk. The biggest operational risk remains slower new orders or delayed secondary market activity, which could matter more for cash flow than this single but sizable contract.
The SAR contract sits closest to the existing thesis because it links several moving parts that already matter for Greenbrier Companies. It touches North American manufacturing in Mexico, U.S. steel sourcing, and export demand. All of these feed into how well the business uses its footprint and keeps plants running at steady rates.
For catalysts, the interesting angle is how export projects like SAR interact with Greenbrier Companies’ focus on efficiency and facility optimization. If management executes cleanly on complex international deliveries while still working through European rationalization and a weaker leasing secondary market, investors get a real time test of how resilient that margin improvement and backlog story can be when conditions are mixed.
Greenbrier Companies' current earnings of $148.3 million compare with analyst consensus earnings of $95.4 million by 2029. This implies an earnings decline of about $52.9 million alongside forecast revenues of $2.8 billion in that same year, while revenue is expected to remain fairly flat over the period.
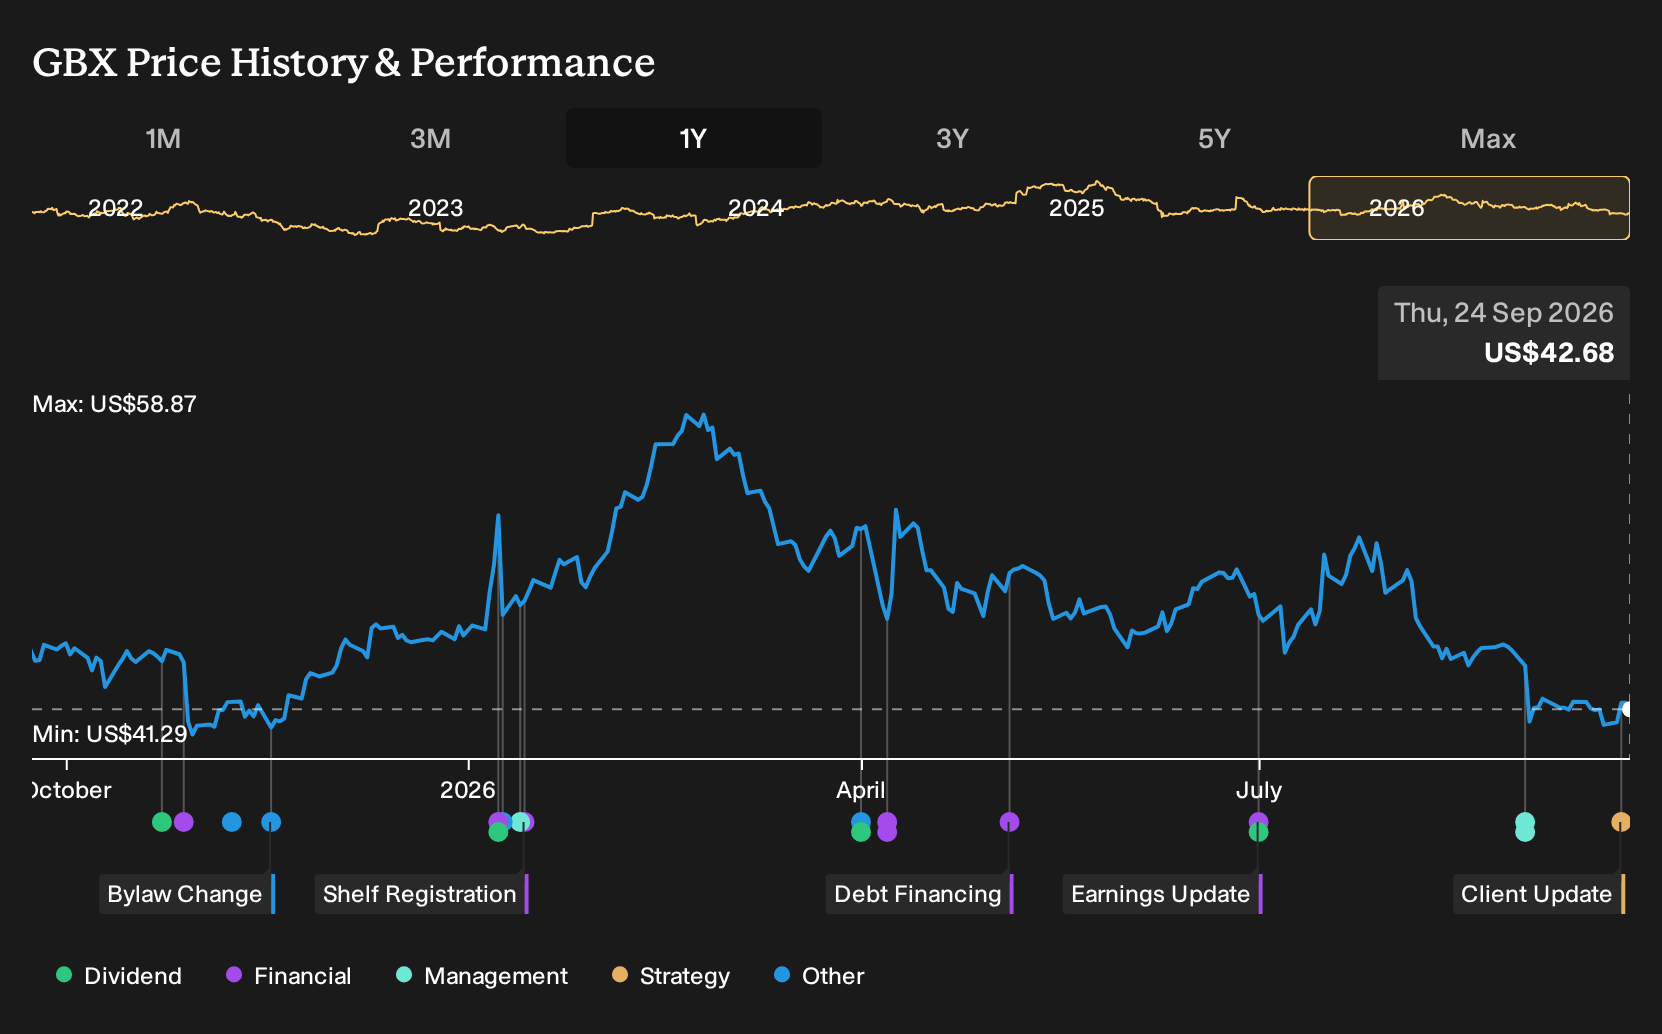
Uncover why Greenbrier Companies' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Greenbrier Companies focuses less on new contracts and more on the risk that order momentum fades again. The most cautious analysts were already modeling roughly flat revenue around US$3.1b by 2029 and earnings of US$106.4 million. That is a more restrained view that could shift as you weigh this fresh SAR order and other updates.
Explore another Greenbrier Companies fair value estimate, including one that suggests as much as 92% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Greenbrier Companies research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Greenbrier Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Greenbrier Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Greenbrier Companies?
If Greenbrier Companies has sharpened your focus on where risk and reward can intersect, you might want to widen the net and compare it with other businesses that fit very different profiles. Using the Simply Wall St Screener, you can quickly scan for companies that match the balance sheet strength, income profile, or valuation characteristics that matter most to you.
- If you want potential mispricing with quality fundamentals, take a look at our 30 high quality undervalued stocks that blend solid cash flows with supportive balance sheets.
- For investors who care most about capital preservation and steadier risk profiles, filter for companies in the 30 resilient stocks with low risk scores and see which ones align with your comfort level.
- When you want to focus on financial resilience first and growth second, head to the list of solid balance sheet and fundamentals (24 results) and compare options against Greenbrier Companies on debt, cash, and assets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com