
Accenture And 2 Other Dividend Stocks To Own
Global bond yields are climbing, mortgages cost more, and the 30 year US Treasury sits at its highest level since 2004. Cash parked in low yielding accounts now faces a tougher hurdle. Reliable income from shares that already pay more than a 3% dividend, and have room to keep those payouts steady, looks far more interesting. This article highlights three such dividend heavyweights that may merit a closer look.
The three income ideas below are just a starting sample, because the full Dividend Powerhouses screen surfaced 171 more companies with yields above 3% and equally compelling payout stories that are not covered here.
If you want to identify and analyze high conviction dividend candidates that fit your own risk and income targets, head straight into the Dividend Powerhouses (3%+ Yield) screener
Accenture (ACN)
Accenture is central to this dividend screen because its consulting and technology services, especially in systems integration and cloud work, generate the cash that supports a higher-yielding payout profile investors can count and plan around.
"AI could reduce the need for traditional consulting, coding, testing, documentation, support, and outsourcing roles."
What happens to that dividend story if one unseen pressure on Accenture’s cash generation quietly shifts the balance on margins and contracts?
That quiet pressure is exactly what the full narrative for Accenture unpacks, revealing where Accenture’s cash engine could be accelerating, stalling, or quietly decoupling from expectations.

Kaspi.kz (KSPI)
Kaspi.kz runs a super-app that blends payments, online shopping, and consumer finance. Its higher yielding dividend potential leans heavily on recurring cash flow from everyday transactions rather than one-off deals or financial engineering.
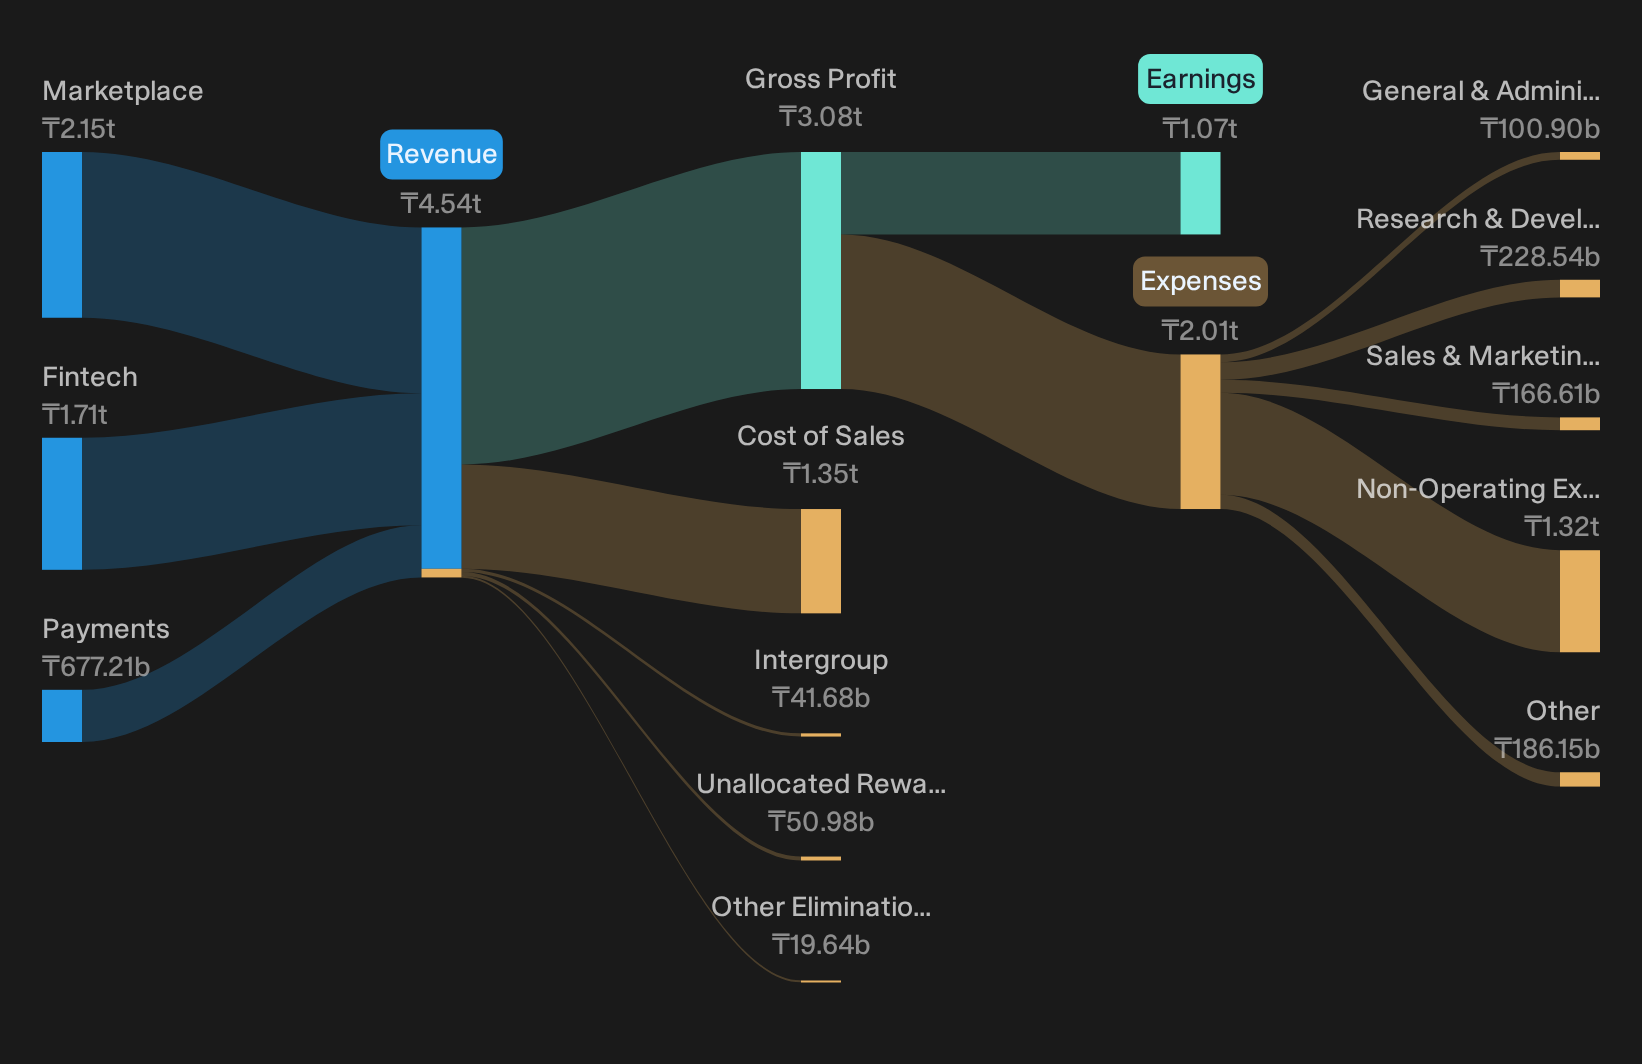
Kaspi.kz generates revenue across Marketplace at KZT 2.15t, Fintech at KZT 1.71t, and Payments at KZT 677.21b, with intergroup and reward adjustments trimming reported totals, and carries a market value of about US$17.84b.
"The rollout and success of higher-yield deposit products are accelerating customer acquisition and bringing new funds onto the platform, positioning Kaspi.kz to benefit from greater transaction flow and, once interest rates decline, a significant rebound in fintech margins and earnings."
What happens to Kaspi.kz’s dividend profile if one unresolved pressure on its funding mix quietly tilts the balance between yield, risk, and growth?
That quiet tilt in Kaspi.kz’s funding mix is exactly what the full narrative for Kaspi.kz unpacks, highlighting where accelerating deposits may be masking fresh income risks and upside.
VICI Properties (VICI)
VICI Properties owns casinos, hotels and other leisure venues and earns rent from operators through long term triple net leases. This helps underpin a 3%+ style dividend profile built on predictable payments rather than short term trading or fee income.
VICI Properties generates about US$4.1b from real estate investment activities in the United States and has a market value of roughly US$26.1b.
For income investors, VICI Properties offers a way to tap into Las Vegas Strip icons and broader experiential real estate through long term rental contracts. The durability of that cash stream is central to how its dividend can be maintained and potentially expanded over time.
"Given the historical data presented, my assumption is that the company will be able to growth its revenues ~3.5-4.5% during Year 1 and ~3.5-5.5% each year from Year 2-5."
The real tension for VICI’s dividend story sits in how one unresolved pressure on funding and debt service shapes the cash left for payouts.
That funding squeeze is exactly what the full narrative for VICI Properties unpacks, showing where VICI Properties’ rental stream, leverage and dividend ambitions may be quietly accelerating or stalling.

Seeking Alternatives Before Others Catch On
Fresh ideas move first, slow research comes last. Spot potential breakout stories while the data is still under the radar for now. Do not delay, get in early.
- Consider riding early momentum in smaller stories by scanning curated 16 high quality undiscovered gems before other investors start focusing on the same opportunities.
- Position for shifting demand in essential materials by tracking a focused 17 top copper producer stocks that filters for producers with meaningful scale and quality assets.
- Monitor potential upside as automation spending changes by zeroing in on a hand-picked 93 robotics and automation stocks that filters for established players, not story-only tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com