
HPE (HPE) Stock May Be 31% Undervalued Following Record AI Server Orders
Hewlett Packard Enterprise has seen its share price deliver very strong gains in recent years, which naturally raises a sharper question for you as an investor. Are the company’s underlying cash flows solid enough to justify where the stock trades today, especially after such a powerful run?
- Over the past 5 years the stock has returned about 410.5%, so a lot of future cash generation is now effectively being priced into Hewlett Packard Enterprise.
- The recent focus on AI servers and the collaboration with QuEra Computing may support expectations for higher future cash flows and could influence how quickly those cash flows show up for shareholders.
- What if you looked at Hewlett Packard Enterprise through its earnings instead? See what Hewlett Packard Enterprise's 31.5x P/E says about the price.
The issue now is whether Hewlett Packard Enterprise’s current price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
If you want more ideas tied to AI infrastructure and cash flow potential, a focused screen of 85 AI infrastructure stocks is a clear way to expand your research beyond Hewlett Packard Enterprise.
Is Hewlett Packard Enterprise Still Cheap on Cash Flow?
The Discounted Cash Flow model here projects the value of Hewlett Packard Enterprise based on the cash it could return to shareholders over time. On the latest twelve month numbers, the group generated about $3.8b of free cash flow, and the forecast path assumes that this pool of cash keeps growing rather than shrinking.
Analysts and modelled estimates see Hewlett Packard Enterprise’s free cash flow rising into the 2030s, which helps support an intrinsic value that sits substantially above the current share price of $63.52. News of record AI server orders and the quantum collaboration with QuEra is relevant here, because those commitments help explain why the cash flow projections baked into the DCF are as optimistic as they are. Find out what Hewlett Packard Enterprise could be worth using our Discounted Cash Flow (DCF) estimate.
The Hewlett Packard Enterprise Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hewlett Packard Enterprise pick up where the DCF puzzle leaves off. They spell out which paths for Hewlett Packard Enterprise's growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today’s price. They also turn a single valuation output into a set of concrete future checkpoints that you can monitor over time.
Community views on Hewlett Packard Enterprise are split between those who see more upside left in the AI and cloud story and those who think expectations already look full.
Bull case: roughly fairly valued
"HPE's transition to an as-a-service model continues to succeed, annualized recurring revenue and software/services ARR both rose sharply…"
Discover why this Narrative puts Hewlett Packard Enterprise at roughly fairly valued.
Bear case: 22% overvalued
"The Department of Justice's lawsuit to block HPE's acquisition of Juniper Networks introduces uncertainty and risk regarding expected synergies of $450 million…"
Explore why this Narrative puts Hewlett Packard Enterprise at 22% overvalued.
One more Hewlett Packard Enterprise signal to check before you move on
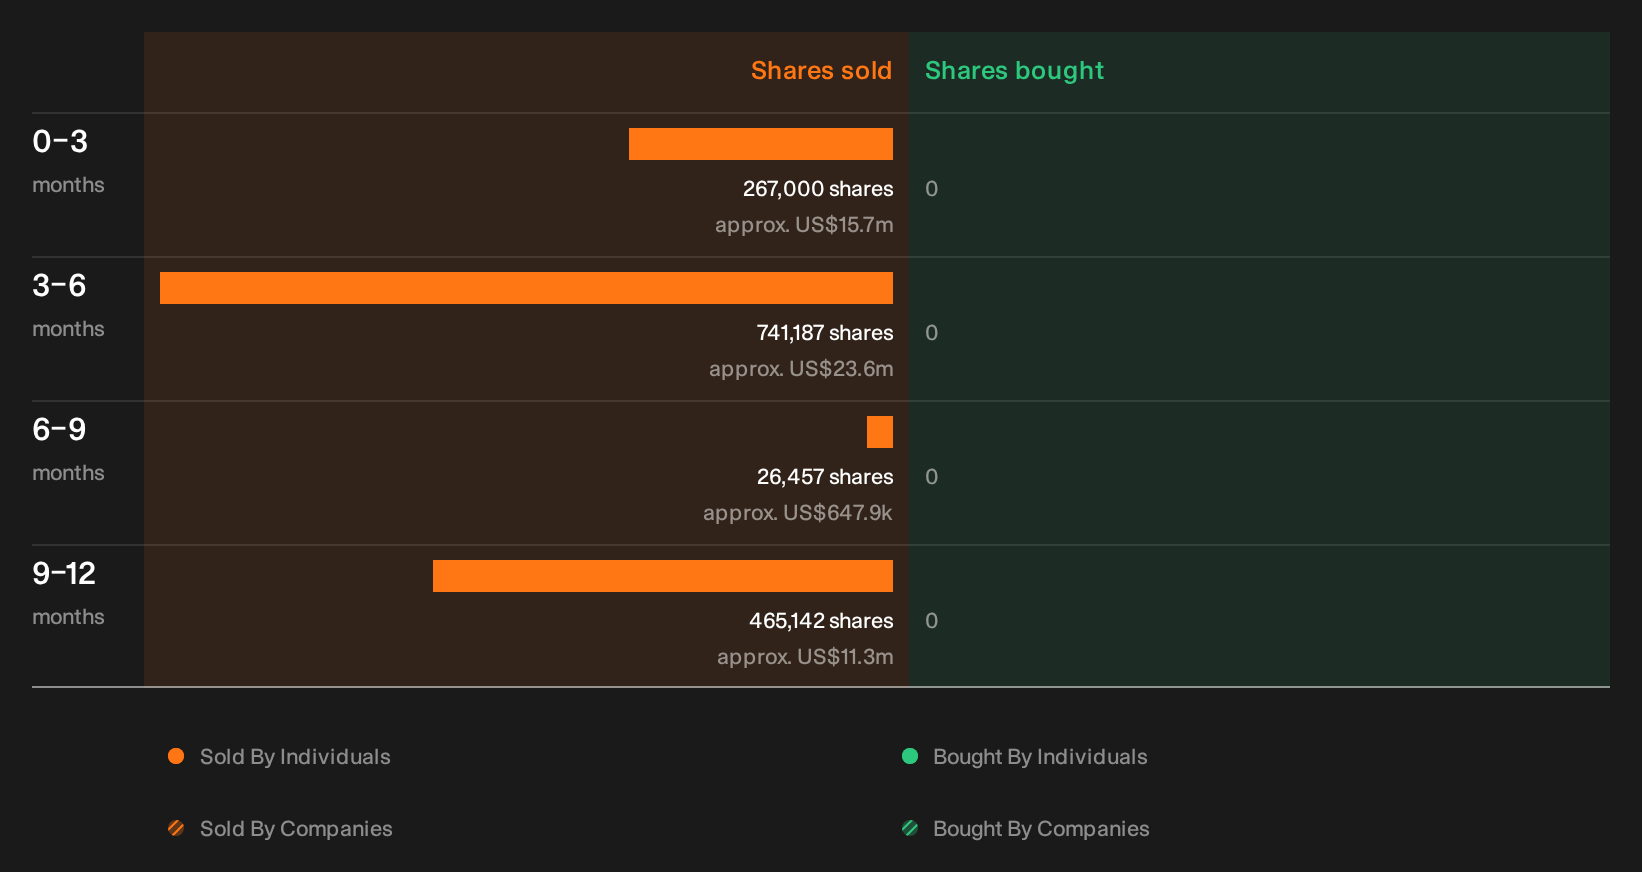
Before acting on any view of Hewlett Packard Enterprise, it is worth checking what recent insider share activity looks like, who has been involved, and how meaningful those trades might be for your thesis. See the recent insider selling flagged for Hewlett Packard Enterprise.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com