
How Fiduciary Duty Probe At Onto Innovation Stock Has Changed Its Investment Story
- Levi & Korsinsky, LLP has opened an investigation into potential fiduciary duty breaches by certain Onto Innovation officers and directors, focusing on their management and oversight responsibilities.
- The focus on boardroom conduct at Onto Innovation puts corporate governance and risk oversight in the spotlight. This matters directly to how shareholders judge the durability of the business model.
- This article will explore how Onto Innovation's long term investment narrative intersects with a new investigation into possible fiduciary duty breaches.
Compare how Onto Innovation fits into the broader semiconductor story by scanning a curated set of 85 AI infrastructure stocks that could face similar boardroom or oversight pressures.
Onto Innovation Investment Narrative Recap
To own Onto Innovation, you need to be comfortable with a story built on demand for process control tools in advanced packaging and leading edge nodes, plus the Semilab integration and regional manufacturing build out. The big near term swing factor is how quickly customers step up orders in AI packaging and advanced nodes. The law firm investigation, as described, does not directly touch that operating setup.
The more immediate business risk still sits in customer spending timing, geopolitical exposure and tariff costs, and execution on integrating Semilab without distracting management. Any perceived governance gaps from the Levi & Korsinsky review could add noise around board focus, but based on what is public today, the operational thesis remains centered on demand cycles and product adoption.
Among recent items, the Levi & Korsinsky investigation is the clearest link to the current news flow. It targets potential fiduciary duty breaches by certain Onto Innovation officers and directors, which puts board oversight, disclosure quality, and risk management under a microscope. For you as a shareholder, that speaks directly to how confidently you can underwrite long duration capital spending cycles at the business.
The key question is whether this review affects execution on catalysts such as the Semilab acquisition, regional manufacturing projects, or product rollouts in AI packaging and advanced nodes. Any distraction at the leadership or board level could complicate integration work and long sales cycles, while a clean resolution would help refocus attention on operational delivery rather than governance scrutiny.
Onto Innovation's current analyst narrative points to revenues of US$2.4b and earnings of US$827.0m by 2029, based on an assumed 29.3% yearly increase in revenue and an earnings increase of about 6x from US$132.6m today.
Uncover how Onto Innovation's fair value indicates a 39% potential upside to its current price before the market closes that gap.
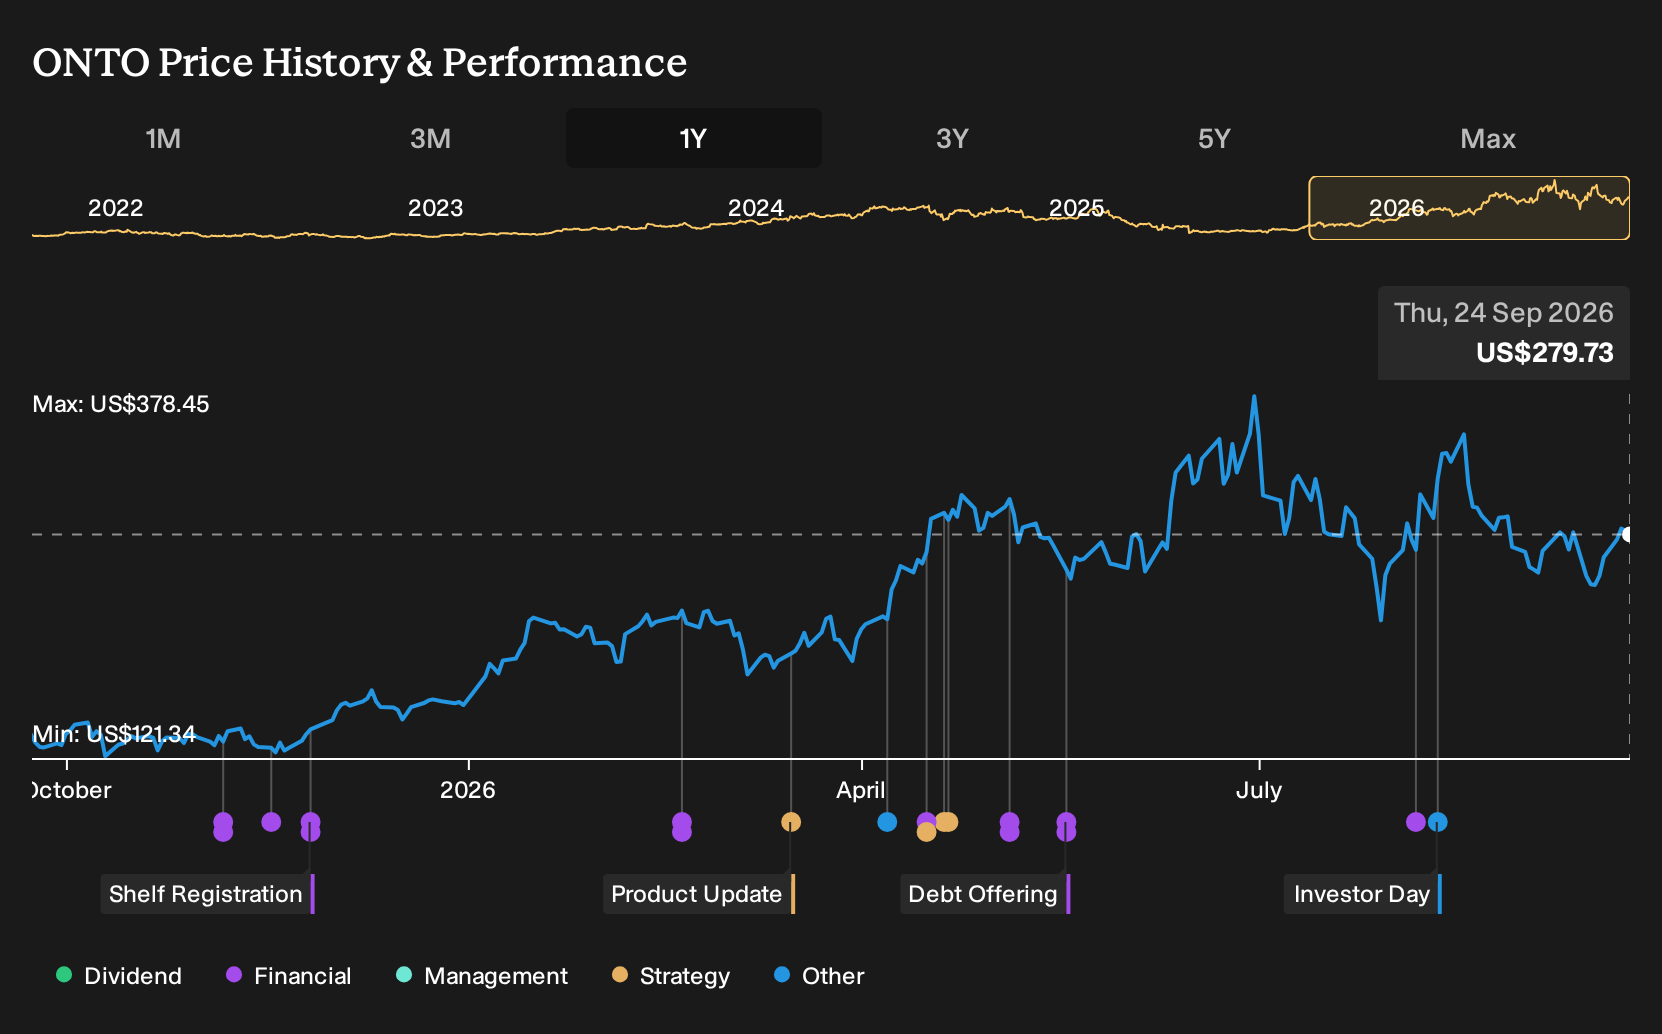
Exploring Other Perspectives
One alternate view on Onto Innovation leans hard into governance risk. You can see that in the more cautious use of future numbers. The lowest analysts were penciling in around US$2.3b of revenue and US$801.4m of earnings by 2029, which is already below consensus. Those estimates came before this investigation, so opinions may shift.
Explore 4 other Onto Innovation fair value estimates, including one that suggests it could be worth just $283.40.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Onto Innovation research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Onto Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Onto Innovation's overall financial health at a glance.
Looking for more Onto Innovation investment ideas?
If the Onto Innovation story has you thinking about portfolio upgrades, use the Simply Wall St Screener to pressure test your thesis against other businesses with different risk and return profiles.
- If capital preservation sits high on your list, scan a 30 resilient stocks with low risk scores that score well on resilience and risk metrics.
- For investors who care most about balance sheet strength, filter for companies with net cash positions and healthy fundamentals using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under-the-radar opportunities, run a search focused on 16 high quality undiscovered gems with strong underlying financials and less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com